

Understanding the taxation of life insurance in 2021 is essential to making informed decisions, optimising the taxation of its investments and anticipating the consequences of a takeover or transmission. This dossier reviews the main tax systems in force, details the rates applicable, the discounts, the exemption mechanisms and the practical cases encountered by life insurance holders.
Social contributions from life insurance in 2021
The Social contributions life insurance rose to 17.2% in 2021. They consist of the CSG (9.2%), the CRDS (0.5%) and a solidarity levy (7.5%). These contributions relate only to earnings, not the initial capital, and their method of deduction differs according to the contract:
- On Euro funds, the deduction is annual, invoiced by the insurer when the interest is credited. It is therefore taken from the water.
- On Multisupport contracts (UC), the social contributions are applied at the time of redemption (total or partial) or at the end of the period, on the capital gain realized.
In the case of units of account, any losses may decrease the basis for taxing earnings, thereby reducing taxation when performance is irregular across all media.
| Type of contract | Method of sampling | Time of taxation |
|---|---|---|
| Euro funds | Interest retained each year | Annual interest credited |
| Multisupport (UC) | On capital gains realized | On redemption or maturity |
Calculation of taxable interest on a redemption
Only the earnings are taxed on a buyback. The calculation formula is: Taxable interest = (Amount of redemption x Total gains) / Total contract value. For total redemption all gains are taxed, while for partial redemption only a proportional share is taxed. Taking into account the timing of payments is essential, as the rules vary:
- Payments prior to September 27, 2017: PFL (a flat-rate exemption) or progressive income tax scheme depending on the duration.
- Later payments: choice between PFU (flat tax) 30 % (12.8% DIR + 17.2% Social contributions) or progressive scale.
Example: for a contract with 30,000 € value (20 000) € investment, 10,000 € a partial redemption of 9,000 € gives a taxable base of 3,000 €.
Tax on payments before September 27, 2017
These payments are subject to declining LFP rates depending on the length of time:
| Contract duration | PFL rate | Reduction |
|---|---|---|
| Under 4 years | 35 % | None |
| 4-8 years | 15 % | None |
| Over 8 years | 7,5 % | 4 600 € (single person), 9 200 € (couple) |
For example, with 8,000 € interest and a contract over 8 years held by a single person, 4 600 € are exempted and 3,400 € Taxed at the reduced rate.
Tax on payments after September 27, 2017
Interest on such payments shall be subject to PFU 30% (under 8 years). After 8 years, and subject to premiums below 150,000 € (single person, 300,000) € for one couple), the rate drops to 7.5% on the relevant band, otherwise full PPU beyond. This mechanism simplifies the calculation and sometimes offers notable gains for mature contracts.
Examples of rates after 2017
| Contract duration | PFU (flat tax) | Progressive scale |
|---|---|---|
| < 8 years | 30% (of which 17.2% PS) | TMI + 17.2% PS |
| > 8 years, premiums ≤ 150 000 € | 7,5 % + 17,2 % PS | TMI + 17.2% PS |
| > 8 years, premiums > 150 000 € | 30 % on excess fraction | TMI + 17.2% PS |
Tax reductions and optimisation after 8 years
After 8 years, the annual interest allowance applies to: 4 600 € for one person alone, 9 200 € for a couple. It offers the possibility to program its buybacks so as not to be taxed on earnings, except social levies. For any mature contract, staggering withdrawals by staying below the discount often remains the most effective strategy.
Attention: social levies remain systematically due, at the rate of 17.2%, whatever the situation.
Tax exemptions in certain cases
The exemption on life insurance buybacks mainly concerns:
- Termination and loss of proven income
- Recognized disability (2nd or 3rd category)
- Early retirement imposed
- Certain contracts entered into before 1983 (subject to conditions)
Supporting documentation will be required when applying for each situation.
Taxation of retirement income
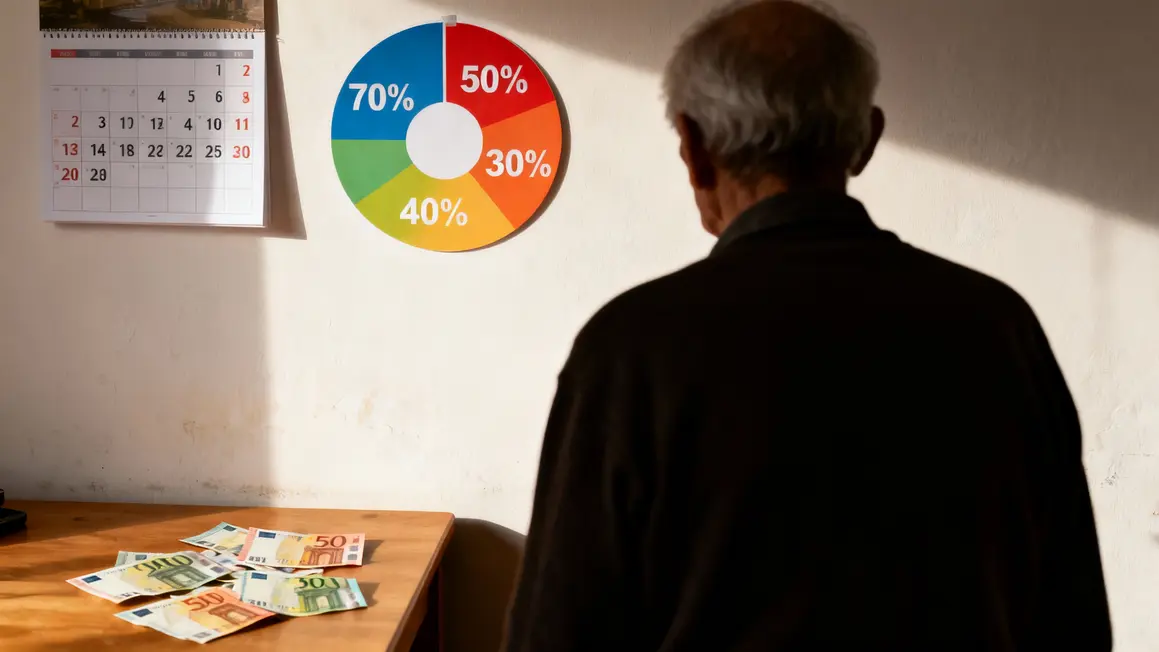
If the capital is converted into a lifetime annuity, only a fraction defined by the age of the beneficiary is taxable:
- 70 % for under 50 years
- 50 % 50 to 59 years
- 40 % 60-69 years
- 30 % 70 years old
| Age at beginning of pension | Taxable fraction |
|---|---|
| Under 50 years | 70 % |
| 50 to 59 years | 50 % |
| 60 to 69 years | 40 % |
| 70 years and over | 30 % |
Example: for an annual annuity of 10,000 € At age 65, the tax covers only 4 000 €, excluding social contributions.
Transmission and inheritance taxation
Life insurance is an optimized heritage vehicle:
- On the premiums paid before age 70, each beneficiary obtains a reduction of 152 500 €. Beyond that, the rate is 20% and 31.25 per cent for the very large sums.
- After 70 years, the reduction falls to 30,500 € all beneficiaries combined, but the interest generated remains exempt.
- Some contracts « Life Generation » allow a further reduction of the taxable base.
Planning the choice of beneficiaries and the amounts paid by age maximizes the estate benefit.
Life insurance contract and IFI liability
Only real estate carriers embedded in life insurance (SCPI, SCI, OPCI) are included in the real estate tax base (IFI). Contracts consisting solely of euro funds or non-real estate units are totally excluded. The certificate issued by the insurer specifies each year the taxable value of the units held.
For a better understanding of the taxation applicable during a transmission, see our full guide onlife estate insurance: taxation, discounts and advice to optimize transmission.
Investing in SCPI in life insurance: fiscal balance, return and transmission can be an effective strategy to optimize taxation while diversifying its wealth.
To better understand the tax impacts of a buyback, discover Remove money from life insurance: conditions, modalities and fiscal consequences.
For holders close to the IFI threshold, it is important to arbitrate non-life insurance real estate investments to limit taxation.
Comparison of schemes and advice to optimize taxation
The choice between PFU, PFL or IRR scale depends on the duration of the contract, the date of payment and the marginal tax rate:
- PFU : competitive for high IMTs, simple (source sampling)
- IR scale: relevant for low or low annual MITs
- PFL: reduced rate after 8 years for old payments
| Situation | Optimal speed | Justification |
|---|---|---|
| Contract > 8 years, post-2017 payments, TMI 30% | 7.5 % PPU | Minimum rate and annual allowance |
| Low income < 25,000 €/year | IR scale | 11 % range |
| Contract < 4 years | PFU | Avoids 35% FLP |
Programming your buybacks to take advantage of the discounts each year reduces long-term taxation. It should also be noted that some unit-of-account media offer options for tax deferral of capital gains.
Author Fabien Durand, Heritage Analyst, specializing in personal investment taxation since 2012.
Have you encountered special cases or would like to bring your experience? Respond to comments and share your tax optimizations or difficulties! If this article has been helpful to you, think about sharing it on your social networks to benefit other people.
What tax strategy have you adopted on your life insurance? Did you prefer the PPU or the progressive scale? Tell us about your choices and see how the 2021 tax could have influenced your decisions.
Sources:
Public service – Taxation life insurance
Impots.gouv.fr – Tax and life insurance