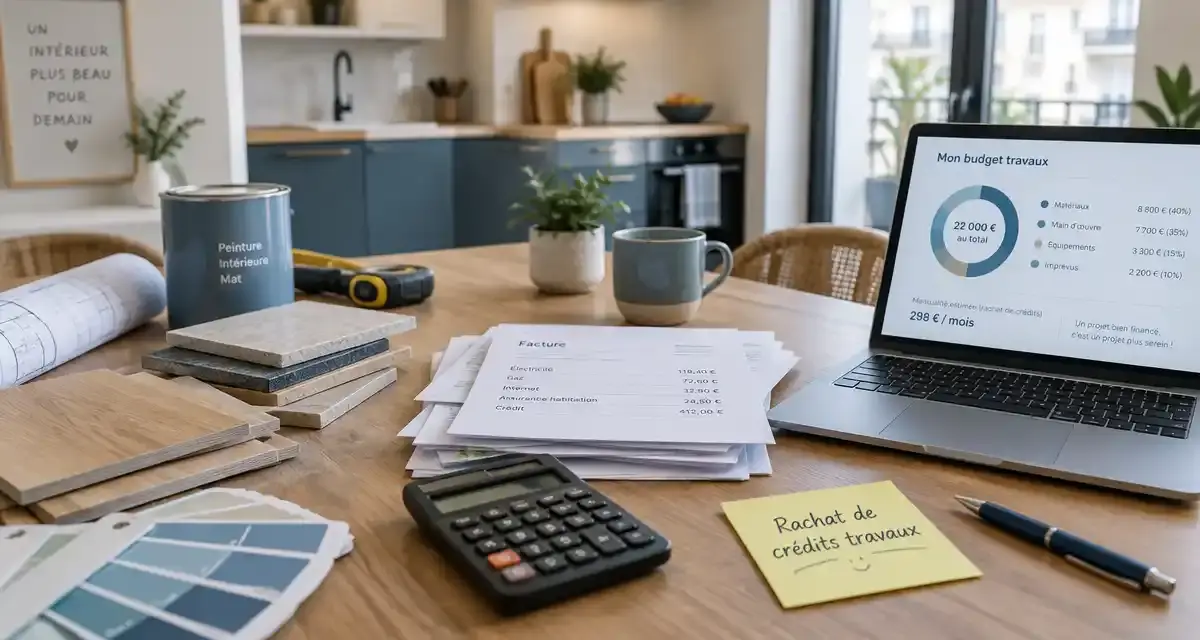
Financing an energy renovation when the budget is already charged does not necessarily require a separate new credit. One buyback of works appropriations can group the loans in progress, integrate a cash dedicated to the works and reorganize the monthly payments around a more comfortable rest to live.
Regrouping appropriations to provide work
The principle is simple: several debts are replaced by a new single loan, with a single monthly payment and a new term. In a repurchase of creditsIt is possible to include real estate credit, consumer credit and certain private debts. For an energy renovation project, the interest is to add a Treasury works to finance insulation, heating or other improvements, without multiplying the levies.
This solution is aimed primarily at households who already have large repayments and who want to avoid adding an additional line of credit. The monthly payment may fall if the duration is longer, but this immediate comfort has a counterpart: the Total cost of credit generally increase. The arbitration thus concerns three concrete points: monthly breathing, repayment period and final cost.
For energy works, the issue is not just banking. A more isolated home can improve thermal comfort and reduce the pressure on bills, but funding must remain sustainable from the first month.
What the BestRates simulation allows
Meilleurtaux offers a free, fast and commitmentless credit buyout simulator. It gives an immediate estimate of the New monthly payment, duration and TAEG. The results are flexible: the borrower can adjust the duration or monthly payment to measure the impact on its monthly budget and the total cost.
At the time compare different credit buyback solutions, this approach helps not only look at the monthlyity displayed. Empruntis, Cafpi and Youfinance are also among the known players in the brokerage, but Meilleurtaux offers a readable simulation and a study of the file by a network of partner banks, with the accompaniment of advisers.
You have to reason like when you choose a window for a renovation: the purchase price is not enough, you also have to look at the exposure, the heat loss, the actual use of the room and the comfort expected over several years. For a purchase of work credits, monthly payments are the most visible element, but the full framework includes the duration, the TAEG, any costs, the total cost and the margin of security in the family budget.
Practical case: financing 10,000 € Insulation in Rennes
Thierry, 47, a CDI technician, is owner of Rennes. Her home receives 3,600 € monthly income. He still repays one mortgage and two consumer credits. Its objective: 10 000 € Cash flow to isolate his home, without increasing his overall monthly payment.
| Situation | Before redemption | After simulation |
|---|---|---|
| Appropriations concerned | 180,000 real estate loan € outstanding and 2 consumer credits of 15 000 € outstanding | New single loan of 205 000 €, cash works included |
| Duration | Multiple remaining durations | 19 years |
| TAEG | Variable according to loans outstanding | 4,57 % |
| Overall monthly payments | 1 380 € | 1 347 € |
| Monthly variance | Reference | 33 € less per month |
| Debt ratio | 38 % | 37 % |
| Total cost of credit | Unbound here | 102 116 € |
Source: simulation data
In this example, Thierry finances his isolation project without increasing monthly payments, while simplifying his repayments. The result is favourable for its monthly cash flow: 1 347 € for 1,380 €. But the operation is based on an extension of the duration to 19 years, which explains a total cost of the credit of 102 116 €. The correct reading is therefore to check whether the increase in budgetary comfort and the completion of the work justify this additional cost.
Points to check before signing
A purchase of works credits must be analysed with precise figures. The first verification concerns the debt ratio After operation, but also the rest to live: food, energy, insurance, transportation, taxes and unforeseen expenses. Lower monthly payments are not enough if the budget remains too tight.
The cash flow must then be clearly isolated. An envelope of 10,000 € for insulation shall not become a blurred reserve absorbed by other expenditure. Asking for quotes, prioritizing the most efficient positions and keeping a small margin for hazards avoids funding too short or too broad.
Finally, the comparison should cover several scenarios: minimum monthly payment, shorter duration, total acceptable cost. This is where an advisor's accompaniment takes his interest, as a solid case does not only seek to lower a monthly payment. He organizes a coherent funding with income, work and actual repayment capacity.