Understanding and choosing the best real estate rate no longer takes on a fighter's journey, even for those who discover the world of online banking: examine the different offers, simulate your financing or determine what bank really fits your situation seems finally quite accessible. With practical advice, illustrated by concrete examples and pragmatic tips, it is quite possible to analyze each criterion with serenite and gain autonomy, both to reduce the cost of credit and to master all your real estate projects, with at the key a peace of mind and a significant security for your family.
Some individuals testify to having found their solution in just a few clicks, a funding trainer recently specified that even the novices get out well equipped with some basic elements.
The best real estate rate in September 2025 – which bank choose, profile by profile?
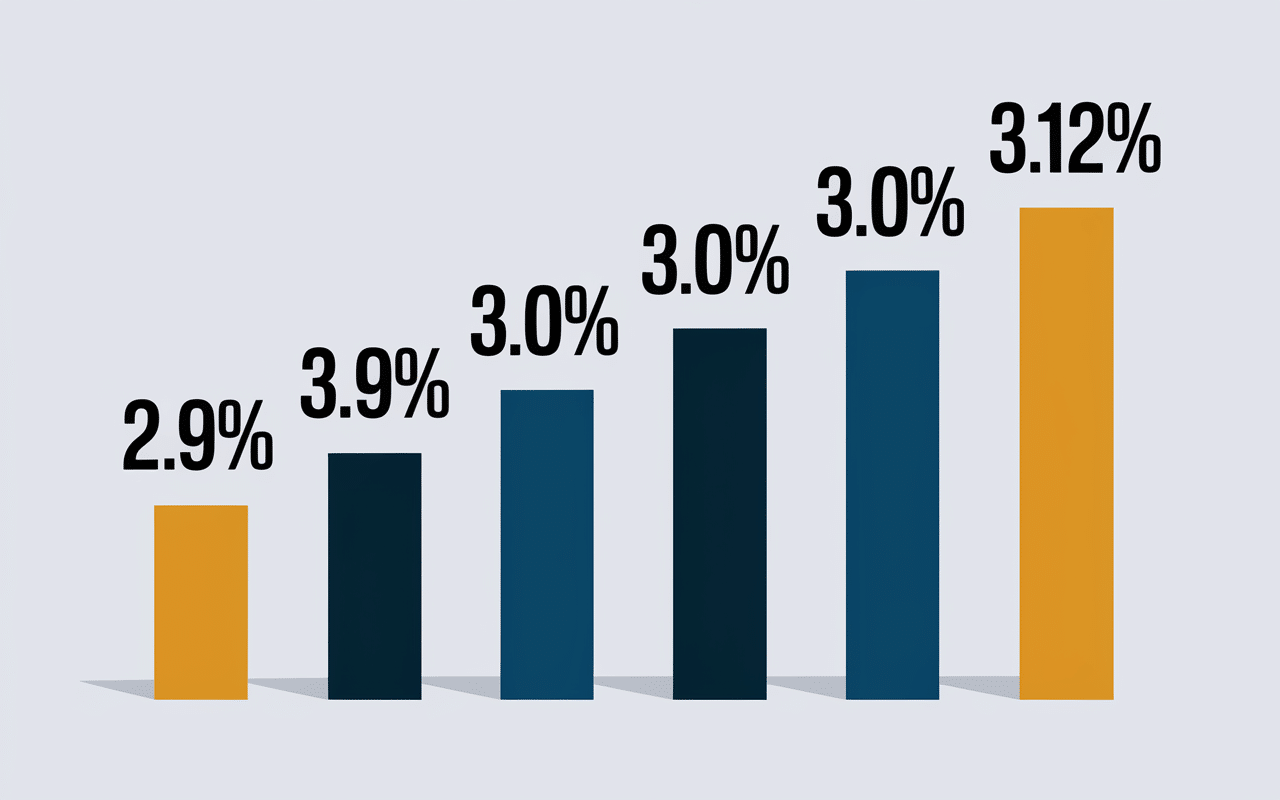
A simple rate spread can save you up to 250 €/month or 3 000 € Over 10 years, this is a fact regularly reported by specialized brokers. The ranking of the most advantageous banks in September 2025 is built according to your situation and the duration envisaged: Bourso Bank and BNP Paribas remain among the market references, sometimes as soon as 2,99% 15 years for solid files.
But this hierarchy is moving and, in practice, it is your borrowing journey and the way you present your case that will tilt the balance towards one offer rather than another. Some professionals point out that a detail, such as managing your account over the last 6 months, can change everything.
Express rating of banks by real estate rate
In general, the approach starts quite naturally with the question: which bank offers the most competitive rates at moment T? Here is an overview of the rates recorded in recent days from the sector references (Reassurance me, Empruntis, CAFPI):
| Bank | Duration 15 years | Duration 20 years | Duration 25 years |
|---|---|---|---|
| Bourso Bank (online) | 2,99% | 3,06% | 3,10% |
| BNP Paribas | 3,12% | 3,17% | 3,24% |
| Agricultural credit | 3,16% | 3,21% | 3,28% |
| Banque Populaire | 3,14% | 3,19% | 3,24% |
| Mutual Credit | 3,09% | 3,13% | 3,20% |
Always think of taking a step back: the posted rate remains indicative. It varies depending on the file, the amount of your contribution, and the duration of the funding chosen. For example, it is not uncommon for a first-time dealer with 15% of intake to see his/her TAEG decrease significantly below 3% in some online banks.
A change of establishment may even make a difference, as several borrowers interviewed recently have experienced.
Custom simulation – how much could you actually save?
Before any decision, simulation is almost indispensable. A simple calculation shows that on a loan of 200 000 € over 20 years, negotiate between 3,06% and 3,27% results in close 4 000 € d) saving on total cost.
Enough to consider an interesting ancillary project, or simply reduce its monthly payments between 18 and 25 €. A financial advisor recently stated that even those who thought they could not negotiate were surprised by the magnitude of the gain.
Using simulators: what savings do you have?
The simulators offered by all the major players in the sector allow to obtain in minutes a clear comparison of the offers and the TAEG adapted to your profile. As a small warning, the difference is not limited to the official rate displayed:
- ✅ On the file feesthe differences are real: sometimes 0 € online (Fortuno, Bourso), or until 1 500 € in a traditional bank.
- ✅ LBorrower insurance is relatively more than is believed, some manage to achieve up to 77% savings through external comparators.
- ✅ Do not neglect the Welcome bonus : it is not unusual to enjoy until 260 € offered by some online actors.
The simulator gives immediate insight into the impact of each major criterion on your overall budget. Some customers say they changed their minds as a result of this situation.
Practical tips to optimize your rate and folder
It is also best to act on the details that make the difference. A contribution of at least 10%, one debt ratio less than 35%, and a solid CDI regularly emerge as key factors.
Nevertheless, there are tricks that work, even for more atypical profiles or for families already engaged in other credits. A former banker reported that a coherent, well-explained project makes it possible to negotiate even if your journey is not quite standard.
However, this is not always obvious; Some banks may have to go through several banks before obtaining a favourable agreement.
Good to know
I recommend that you prepare a consistent and clear file as it greatly facilitates negotiation, even for atypical profiles.
Negotiate as a pro, even without a broker
Do you really think the displayed rate is engraved in marble? It's far from systematic! Negotiations play a decisive role, sometimes even for the less experienced.
Financial institutions are generally inclined to adjust their conditions according to:
- ✅ Your income level and professional status (Staff, framework or Independent... each has its own advantages)
- ✅ The seriousness of your account management over time, a point often underestimated
- ✅ The precise nature of your project: purchase of a principal residence, rental investment, or solicitation of a PTZ
Another effective lever, tested many times: making the competition play in an argumented way during a second appointment and presenting a solid alternative proposal often makes it possible to obtain 0.10 to 0.25 point rate reduction, i.e. up to 1 800 € The economy over 15 years.
As several industry experts point out, this is a proven method.
Banking education: really understand the rate and what surrounds it
The real estate rate attracts attention, but TAEG (Annual total effective rate) offers a complete vision as it includes ancillary costs such as insurance, warranty or file fees.
An attractive nominal rate does not alone guarantee the best deal: compare in detail the TAEG proves to be a must to avoid bad surprises. Sometimes a borrower, thinking that he has found the best rate, discovers, after all, a higher overall cost than expected.
Useful Glossary and Vigilance Points
Behind the acronyms, we find some key notions to memorize to move forward calmly:
- ✅ TAEG : the only legal indicator that combines all credit costs a reliable benchmark.
- ✅ Personal contribution : a minimum of 10 to 20% is generally recommended; each additional point facilitates access to an optimized rate.
- ✅ Debt ratio : ideally fixed under the bar of 35% (all loans included), to be monitored especially when there are already credits in progress.
- ✅ Borrowing insurance The Lemoine Act makes the choice much more open and, often, a well-informed negotiation significantly lowers the bill.
Despite a jargon that may seem hermetic at first, rest assured: the accompaniment offered by platform advisors or via a simulator greatly facilitates understanding, step by step.
Many users testify to be appropriate bases in one evening only.
Social proofs and reinsurance: choosing with confidence
For a real estate project, trust is never a detail. Specialized platforms such as Reassuring Me or Meilleurtaux generally have high satisfaction scores: Trustpilot 4.7/5 over 19,000 opinions in 2025.
Many Internet users admit that they have saved "several thousands of euros" through these comparators or on the recommendation of a broker.
It is also a way to save time: a young couple recently stressed the importance of reassuring support on the documents to be provided and the project schedule.
Recognized labels and expertise
Your reinsurance also requires the legal expertise and the partnerships displayed: authorization of theACPR, business certifications, or recurrent quotes in national media (Le Figaro, BFM) have become essential standards.
This is also why it is useful to check that the comparator tool used is independent, as no bank can buy its place in the final ranking.
As one sector analyst points out, transparency is now the number one argument.
Market analysis – trends and trends
After several months of growth, the market finally showed a stability expected in September 2025, with very limited variations (often less than 0.10 point between the different observatories).
Online players maintain an aggressive policy to capture connected profiles, but historical banks are increasingly focusing on customization and flexibility of editing.
Will it last? No expert advances but many recognize that the current window remains globally timely.
To optimize your chances of getting the best real estate rate, it is crucial to understand the basics of calculation of the debt ratio: method and thresholds to control your finances.
To optimize your borrowing, discover how to calculate my mortgage monthly payments and anticipate future expenses.
To get an advantageous loan, discover the 6 key steps to get the best rate and maximize your chances of success.
Macroeconomic context and outlook
The major decisions of the ECB continue to influence rates, even ifOAT (Treasury assimilable obligation) remained well-mannered at the beginning of 2025.
If you are wondering about the "perfect time to borrow", know that the majority of brokers estimate the current period as "favourable".
In their view, it is better to move forward without waiting too long for a hypothetical decline which, for the moment, is slow to materialize. As we like to recall in the middle, we must not wait for the right time, but rather prepare the right file.
FAQ real estate expert: your questions simply solved
There are still hesitations at this stage. The following are the most common doubts, which are clearly addressed:
Which bank offers the best real estate rate today?
Bourso Bank and BNP Paribas are among the most competitive institutions for rates – however, the best choice always depends on the profile, amount and contribution.
Some experts recommend reviewing his case several times a year, as the trend can change very quickly.
Do I have to go through a broker or compare myself?
A broker facilitates negotiation and access to sometimes less visible offers, but free online comparators available 24 hours a day offer a quick first selection before engaging in discussion with a bank or advisor.
Which profiles get the most advantageous rates?
The files in CDI A stable contribution of over 10% and a controlled debt ratio tend to be preferred.
Both families and young people working at home with the digital tool are, in most cases, offered attractive online rates, according to several experts interviewed recently.
TAEG versus nominal rate, how important?
Only TAEG accurately reflects the actual cost of the credit (including any fees). Better not stop at the call rates displayed in promotions!
What savings can I hope with the right choice?
Until 250 €/month or 456 €/year and sometimes more than 3 000 € saving on the total cost of the loan by carefully negotiating.
Basically, comparing and playing on all criteria really pays off.
Your turn! Simulate, compare, negotiate
You now have all the cards to move forward: launch the simulation on a comparator, ask for a quick quote, or exchange with an expert to get personalized lighting.
A few minutes is enough to rock a project – and sometimes this is all that separates a classic purchase from an unexpected opportunity.
Good road to realizing your real estate project.