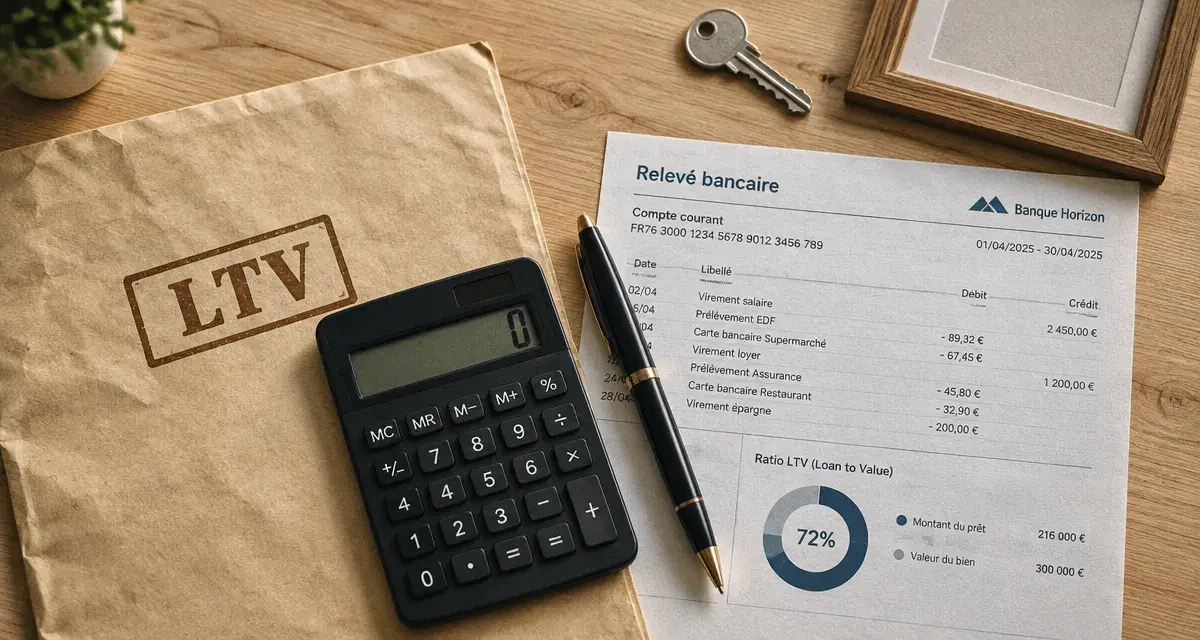
The Loan to Value, or LTV, measures the share of the value of an asset financed by debt. It is widely used in real estate credit and helps the bank and investor assess the risk of a project. The higher the ratio, the more the financing depends on borrowing rather than own funds.
Loan to Value: Definition and Role in Funding
The Loan to Value, literally « Value loan », is a debt ratio expressed as a percentage. It compares the net debt related to a property or portfolio to its market value. In residential, rental or professional real estate, as in investment vehicles such as SCPI, it serves as a benchmark for assessing the financial strength of a borrower or structure.
Loan to Value Calculator
Estimate the ratio between your net debt and the market value of your asset.
Your LTV ratio
Over 70%
LTV = net debt value × 100
LTV does not answer the question « Can you pay the monthly payment? ». This is more a matter of analysing income, expenses and the debt ratio. Instead, the ratio is: If the value of the asset declines or if the asset is to be sold, what portion of the value remains covered by the debt? It therefore provides information on heritage risk and the ability to repay indirectly.
Why do banks monitor this ratio?
For a lender, a low LTV means that a margin of security exists between the value of the asset given as collateral and the amount still due. The personal contribution, the capital already repaid or an increase in the value of the property reinforces this margin. Conversely, a high LTV reduces the security cushion: a limited decline in the market may be sufficient to bring debt closer to the asset value.
The ratio can also influence the proposed conditions: the amount of funding, guarantees requested, the cost of credit and the margin of negotiation of the rate. However, it never decides on the agreement alone. The bank also examines the professional situation, income, available savings, the quality of the property and the overall coherence of the project.
Calculate the LTV ratio without distorting the result
The Loan to Value formula is as follows:
LTV = net debt / asset value × 100
Net debt is the financial debt that remains to be borne. The value of the asset must reflect its market value. In a real estate acquisition, it is generally valued excluding notary fees. Mixing the price of the property with the associated costs can artificially change the denominator or amount funded, and make the comparison less relevant.
Two examples to understand the calculation
| Situation | Net debt | Value of assets | LTV |
|---|---|---|---|
| Highly financed acquisition | 500 000 € | 535 500 € | 93,4 % |
| Reduced debt and valued asset | 430 000 € | 570 000 € | 75,4 % |
In the first case, 500,000 divided by 535,500 give an LTV of 93.4%. Debt accounts for almost the entire asset value and the security margin is low. In the second, the repayment of part of the capital and the increase in the value of the property reduce the ratio to 75.4%. Heritage risk decreases, although debt levels remain high.
Value is worth as much attention as debt
An optimistic estimate can give the illusion of a comfortable LTV. For a prudent reading, a realistic market value, consistent with comparable transactions and the condition of the asset, must be retained. The valuation method therefore counts as much as the amount of the debt.
For a SCPI or land, the underlying asset is a real estate portfolio. The published value and the assessment procedures should be carefully examined as they form the basis for the calculation of the ratio.
Interpret low, moderate or high LTV
There is no universal threshold for all projects. The nature of the property, the stability of rents, the duration of the credit, the guarantees and the borrower's profile change the analysis. However, some benchmarks allow for a first reading.
- Less than 50 % The LTV is generally considered moderate. Debt weighs relatively little against the value of assets.
- Between 50% and 70% Indebtedness requires more detailed analysis, but can remain consistent in a controlled strategy.
- Over 70% : the level becomes more risky because the tolerable value decline before a financial tension is reduced.
A high LTV is not automatically bad. It can correspond to the start of a credit-financed investment and make it possible to mobilise less personal capital. This is the principle ofleverage effect : if the asset generates sufficient income and retains its value, the investor can improve the return on its equity. In return, maturities and risk of impairment remain, especially when rents decline or refinancing rates increase.
The LTV links two developments often examined separately: the capital remaining due to decline over time, while the market value may rise, stagnate or decline. These movements combine. A borrower can repay regularly while seeing its LTV not improving if the market returns. Conversely, a valuation of the property can improve the ratio without exceptional reimbursement. The monitoring of the LTV makes it possible to distinguish the Real debt relief a simple recovery effect.
Real Estate Credit and SCPI: Close Use, Different Readings
In an individual real estate loan, the LTV is observed at the time of the loan application. It can then be re-evaluated in the context of a renegotiation, credit buyback or request for additional financing. The borrower should update its ratio after several years of repayment, based on a credible estimate of the asset. A lower LTV can strengthen its record without guaranteeing better conditions alone.
The SCPI and real estate vehicle LTV
For an SCPI, the ratio measures the debt burden at the asset level held. It informs the partner on the use of the management company's borrowing, and not on its personal financing if it purchases its shares on credit. The announced LTV limits can be 40% or 50%, while SCPIs are rarely indebted to more than 30%. The average SCPI LTV was 18.5% in 2022According to Pierre Papier.
A low LTV can reassure the resilience of the portfolio, but it can also limit leverage. Conversely, higher debt can support acquisitions if income, maturity and building quality warrant. The information note, the level of debt, its maturity and its cost complement the ratio reading.
Use LTV to decide with method
Before a purchase or investment, calculate the initial LTV and then test it in several scenarios: value of the stable property, decrease in value, partial repayment and increase in the cost of debt. This approach makes it possible to assess the available margin rather than limit itself to an isolated figure. For rental property, also check the ability of rents to cover financial expenses. A low LTV does not compensate for a fragile cash flow.
- Identify the net debt Really due.
- Hold a conservative market value, excluding notary fees.
- Apply the formula and compare the result to the risk markers.
- Refresh the calculation when capital decreases or the value of the property changes.
- Analyze the LTV with revenues, available liquidity and the holding horizon.
The Loan to Value is a simple comparison tool, but it does not replace a complete analysis. Well calculated and regularly updated, it allows to visualize the Financial risk, prepare a banking discussion and choose a level of debt consistent with a real estate strategy.