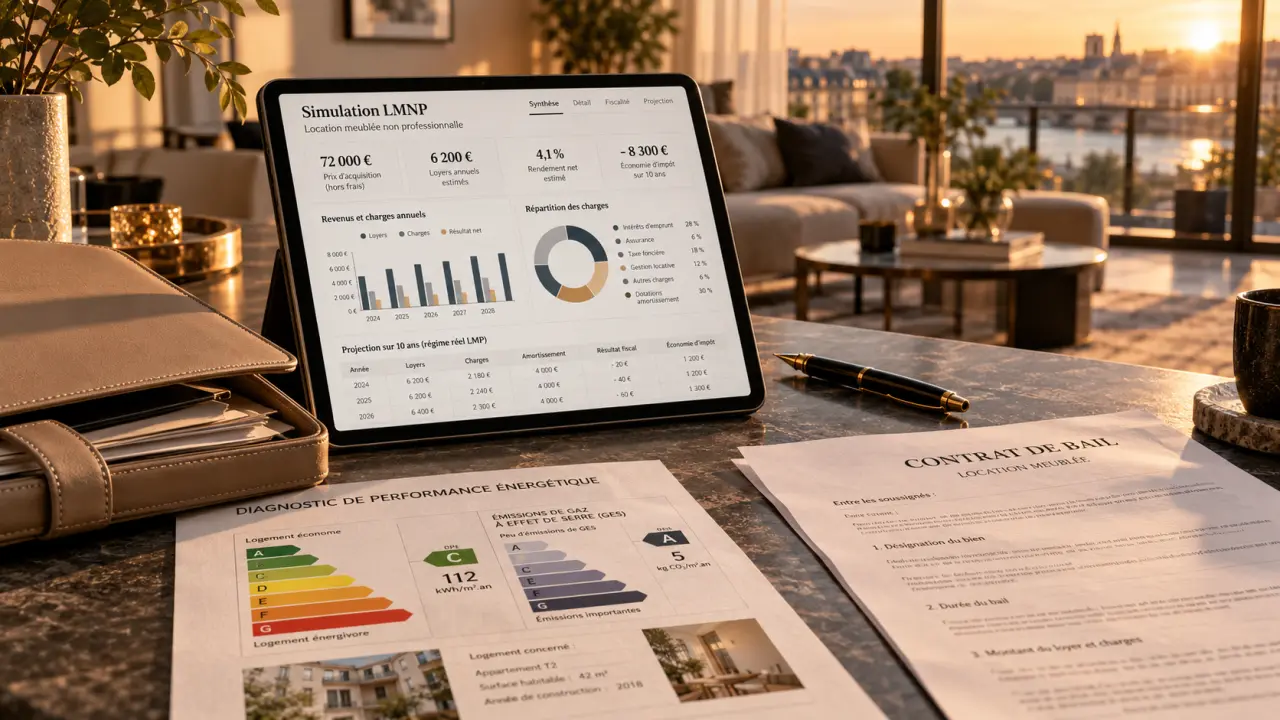
An LMNP investment consists of renting furnished housing and reporting revenues in the Industrial and Commercial Profits (BIC) category. Its interest depends on rental demand, actual expenses and taxation. Depreciation can reduce tax but does not compensate for excessive purchase price or the fragility of a manager.
Before you buy to prepare your retirement or supplement your income, analyze the project as a real estate investment and then as a tax transaction. The return and resale conditions count as much as the tax system.
Check your status before choosing accommodation
LMNP means rental in non-professional furnished. This status does not entail an automatic tax reduction and does not apply only to residential services. A year-round old rented apartment can be furnished, as can a new one entrusted to an operator.
You qualify as a professional furnished rental (LMP) when two conditions are met: the household's annual furnished rental revenues exceed EUR 23 000 and exceed other professional income retained by regulation. If only one of these conditions is met, you will in principle remain at LMNP. The comparison therefore does not involve checking whether the income exceeds 50 per cent of the total household income, including property.
The transition to LMP changes in particular the treatment of deficits and capital gains. It can also have social consequences. This change depends on your actual situation, not on a commercial choice made at the time of purchase.
The housing must be decent and respect the rules of equipment of a furnished rental. This includes bedding with duvet or blanket, room cover, hobs, oven or microwave, and refrigerator with suitable compartment. The list also includes dishes, utensils, a table, seats, storage, luminaires and appropriate maintenance equipment.
The declaration of commencement of activity shall be made on the Single window of business formalities, which allows to obtain a SIRET number. The old procedures with the CFE or the transplant are no longer the reference circuit. If you are planning a tourist rental, also check the applicable local rules.
Choosing a property with no tax advantage
Classic housing: more freedom and responsibility
For classic accommodation, you choose the tenant and manage the lease, directly or through an agency. Study actual rents, transportation, employment areas, educational institutions and competing housing. Before making an offer, also check the energy performance diagnosis and rental restrictions.
In the old, you can observe the building and its environment, but have to anticipate the work. The nine offers recent guarantees and equipment, without justifying too high a purchase price. In VEFA, include the delivery time and any interest in your calculation. The possibility of resuming the dwelling to live there then depends on the lease and the applicable leave rules.
Residence services: quality of lease becomes decisive
Student, senior, tourism, business or EHPAD residences are found in different markets. With a commercial lease, your tenant is usually the operator. He is responsible for the operation of the residence and pays you the rent provided for in the contract. Homelessness does not necessarily suspend this payment, but the lease does not guarantee the solvency of the manager.
Before signing, ask the operator's accounts, rental history, possible renegotiations and occupancy rate of the residence. Have the indexation of rent reviewed, possibilities for termination, renewal and distribution of work. Refusal to renew may result in eviction compensation. Do not assume that you will be able to occupy a dwelling under this contract.
Compare micro-BIC and real over the entire period of detention
The tax system determines the taxable benefit, but not the amount available on your account. To compare options, separate paid expenses, reimbursement from credit and accounting deductions. The right choice depends on your situation and should be assessed over the expected length of detention.
| Comparative point | Micro-BIC | Actual |
|---|---|---|
| Tax calculation | Flat-rate allowance on income | Allowable expenses and depreciation |
| Actual expenditure | No additional deduction | Deduction by nature and justification |
| Monitoring | Simplified declarations | Accounting and taxation |
| Arbitration | To consider whether spending is low | Simulating if charges and depreciation are significant |
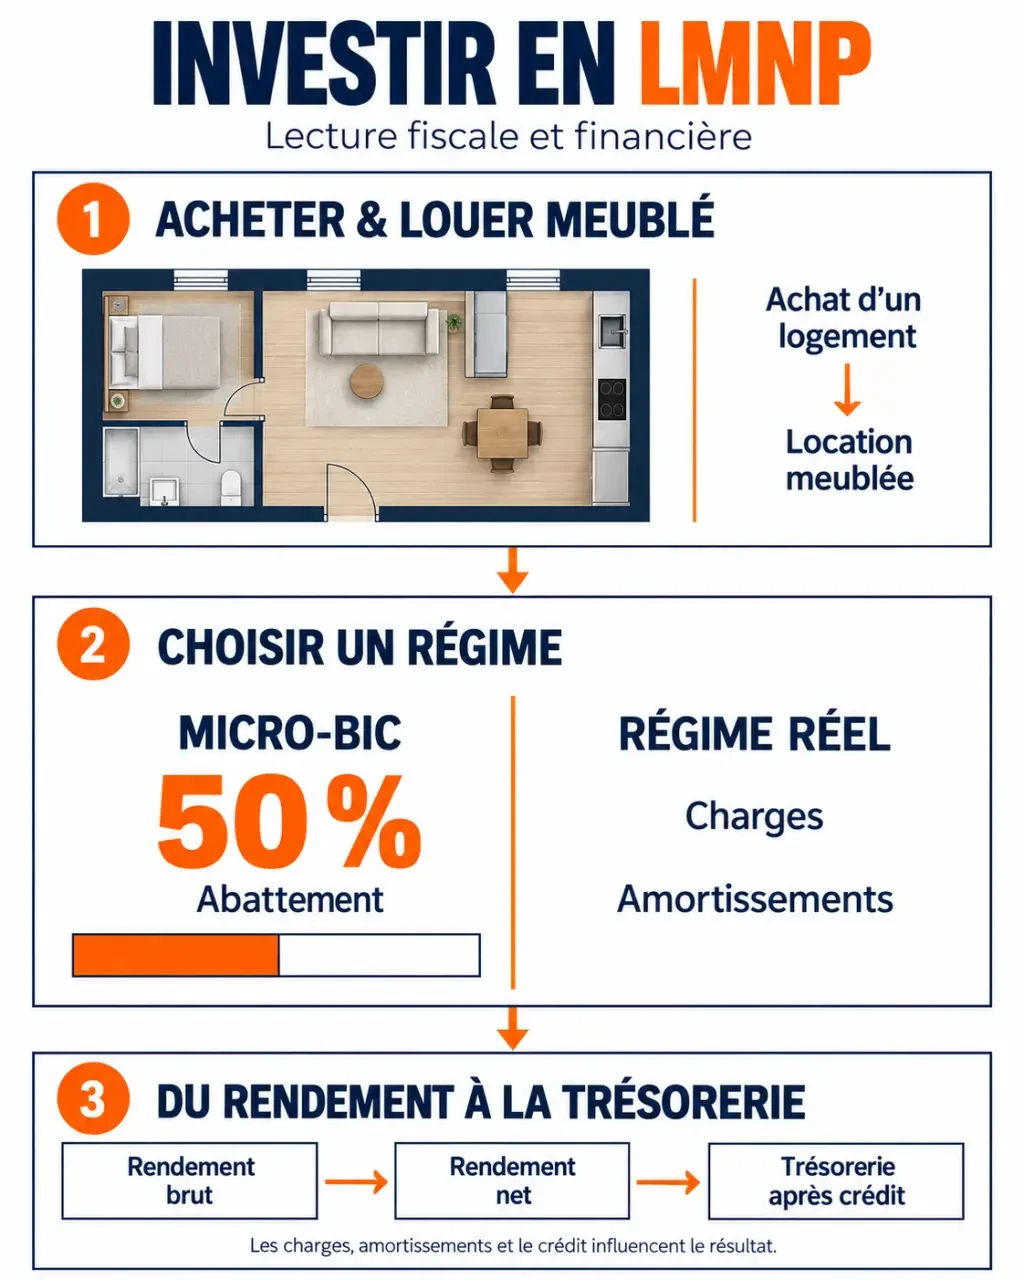
For long-term furnished rental, the micro-BIC provides for a 50 per cent discount, with a minimum of 305 euros, subject to the eligibility requirements. The ceilings and rules for tourist furniture differ. Check those that relate to your activity and the year declared, rather than resuming an old threshold.
Under the actual scheme, interest on borrowing, insurance, management fees, property tax and certain maintenance expenses may be deductible. The capital repaid to the bank is not. The building is damaged by components, off-site, and the furniture according to its duration of use. There is no single depreciation percentage suitable for all assets.
Depreciation cannot create or worsen a tax deficit. Depreciation not deducted shall be carried forward according to the applicable rules. For their part, the LMNP deficits from the expenses are carryable during 10 years on profits of the same nature, not on your salary.
On resale, the NPMA generally falls under the personal property gains regime. In principle, the depreciation deducted must now be taken into account in the calculation of capital gain, subject to legal exceptions concerning certain residences. Make this figure: an annual tax saving is not necessarily a permanent gain. The status also does not automatically exempt the property from the IFI.
Calculate yield and saving effort separately
Gross yield is the annual rent divided by the total cost of acquisition, which includes the price, purchase costs, furniture and initial work. To calculate the net return before financing, subtract non-recoverable expenses, insurance, management fees, maintenance, rental vacancy and, where applicable, local taxation.
Here is a teaching hypothesis: a total cost of 150,000 euros and 7,500 euros of annual rents give a gross return of 5%. With EUR 2 000 in annual expenditure, the yield drops to 3.67% before financing and personal taxation. If credit maturities amount to €7,200 per year, cash flow is less than €1,700 before tax. The project builds a wealth but does not yet provide any additional income available.
Also test a less favorable scenario, with an additional vacancy period, work or a decrease in rent at renewal. Even if management is delegated, plan a cash reserve to meet unforeseen expenses.
VAT 20 % is recoverable only if the operation fulfils the conditions of subordination, in particular those relating to the proposed benefits. Buying in a residence services is not enough. Recovery may be subject to regularisation on 20 years. However, an advance sale does not systematically entail full reimbursement, depending on the conditions for continuing taxable activity.
Prepare the exit before signing
An LMNP investment follows several maturities: credit, works, commercial lease and possible VAT adjustment. Report them to the same frieze. If the lease renewal coincides with your retirement and significant work, expected revenues may become less predictable when you need them.
Before you commit, gather the documents and estimates that are useful to your decision:
- The references of rents and comparable sales.
- Diagnostics, condominium minutes and planned work.
- Full lease and operator's accounts, if any.
- A simulation integrating financing, taxes and resale costs.
- An estimate of the value of the occupied property, without assuming an increase.
Finally, compare the LMNP with the bare lease, which usually requires less furniture, and the SCPI, which mutualize assets but involve costs and liquidity risks. The LMP is not a status that one can freely choose. Have an accountant check the tax and the sensitive clauses by a legal professional. A good purchase must remain consistent even if taxation becomes less favourable.