Hypothetizing a home is giving it as collateral to a creditor, usually a bank, to obtain a loan. You remain the owner and can continue to live, but a default may lead to its seizure and sale. In France, this operation requires a notarial act and registration in the land advertising service.
Before you commit, you must distinguish between three elements: the funding obtained, your ability to repay it and the consequences of the guarantee on your assets.
What You Really Engage By Mortgage Your Home
Mortgage is a guarantee, not a loan. The loan brings the funds; The mortgage protects the lender if you do not repay. We're talking about real estate security, because the guarantee relates to an identified property. The credit remains due even if the value of the house decreases.
A conventional mortgage results from your agreement with the creditor. In particular, it differs from a judicial mortgage, which is covered by a guarantee procedure in a litigation context. For financing negotiated with a bank, it is usually the conventional mortgage that concerns you.
Which projects can be funded?
Depending on the institution and contract, a loan guaranteed by your home can finance work, a real estate purchase, assistance to a relative, a property transaction or a cash flow requirement. Some montages also allow for the grouping of debts. However, the allocation of funds must be validated by the lender: not all banks finance the same uses.
You don't give your house to the bank. You retain its use, subject to contractual commitments. On the other hand, the guarantee will have consequences in a sale, refinancing or certain transmission operations: the notary will have to check its treatment.
The amount available depends on the property, but especially on your budget
Owning a home is not enough to get credit. The bank analyzes your income, expenses, other borrowings, your professional situation and your remaining living. It also verifies the value of the property, its ease of resale and the guarantees already entered.
If the house belongs to several people, you cannot hire all the property alone. The agreement of the rights holders concerned must be verified. The matrimonial regime and the protection of family housing may also require special consent.
Estimate an envelope without confusing it with an offer
The financial amount generally corresponds to a fraction of the value retained by the lender, after taking into account existing debts and guarantees. There is no universal percentage: real estate expertise, mortgage rank and bank risk policy vary the result.
For illustration purposes, a house estimated at 400 000 € and a request for 200 000 € represent a financing ratio of half its value. This does not prejudge the agreement: credit already under way or insufficient income can reduce the envelope or even prevent financing.
The real leverage is not necessarily to borrow more thanks to the house. It may be to limit the amount requested to maintain room for manoeuvre: precautionary savings, maintenance budget and ability to absorb a decline in revenue. A real estate guarantee makes a asset mobilizable, but does not turn it into a monthly income.
Amortissable or in fine: two different constraints
With a depreciable loan, each maturity repays a share of the capital and interest. With a loan fine, the capital is repaid at the final maturity, with interest generally paid during the credit period. This second formula requires a credible and documented reimbursement resource. Placing only on a future resale at the expected price weakens the assembly.
From file to deposit: audits that count
The process begins with a numerical request, followed by banking and legal analysis. An agreement in principle remains conditional: it does not replace the final offer or the notary's checks.
- Make the folder: proof of identity, income, bank statements, title, current credits and project presentation.
- Have the property evaluated: the lender may request expertise and examine its legal situation.
- Study the offer: net amount available, rate, duration, insurance, terms and conditions of early repayment.
- Sign the Notarial Act: the notary formalizes the mortgage and completes the formalities of land advertising.
- Get Unlocked: the funds shall be paid in accordance with the conditions of the tender and the installation chosen.
Do not expect an urgent expenditure solely on the basis of a proposed signature date. The expertise, missing documents, applicable legal deadlines and formalities may delay the operation. Request a written calendar distinguishing bank decision, signature and actual availability of funds.
Real cost includes setting up and exiting
The interest rate is not enough to compare two proposals. The mortgage incurs specific costs that add to the cost of the credit. Ask for a personalized count rather than an overall percentage presented without details.
- Guarantee costs: notary's fees, formalities, disbursements, taxes and property security contribution according to the installation.
- Funding costs: bank file, expertise and possible brokerage fees.
- Insurance: costs and guarantees if borrower insurance is requested or subscribed.
- Output costs: any advance reimbursement allowances and release costs.
Compare the overall effective annual rate, but also the amount actually received and the total to be reimbursed. For two offers of different duration, a lower monthly payment may mask a higher total cost.
Selling remains possible, with a settlement to anticipate
A mortgaged house can be sold. The notary then arranges the reimbursement of the creditors concerned on the price and, where necessary, the release of the registration. If the price does not cover the amounts due and the costs, the sale requires an upstream negotiated solution.
The full repayment of the loan does not instantly erase the registration. It shall normally end at the end of its legal term of effect; early release may be necessary before this deadline, in particular to sell. Have this item checked before calculating your net sales product.
Choose the guarantee without losing sight of the risk
In the event of persistent unpaid payments, the creditor may initiate a seizure procedure leading to a forced sale. This is not an immediate consequence of a missed deadline, but the risk is real. If the price obtained is not sufficient to repay the debt and fees, a balance may remain due.
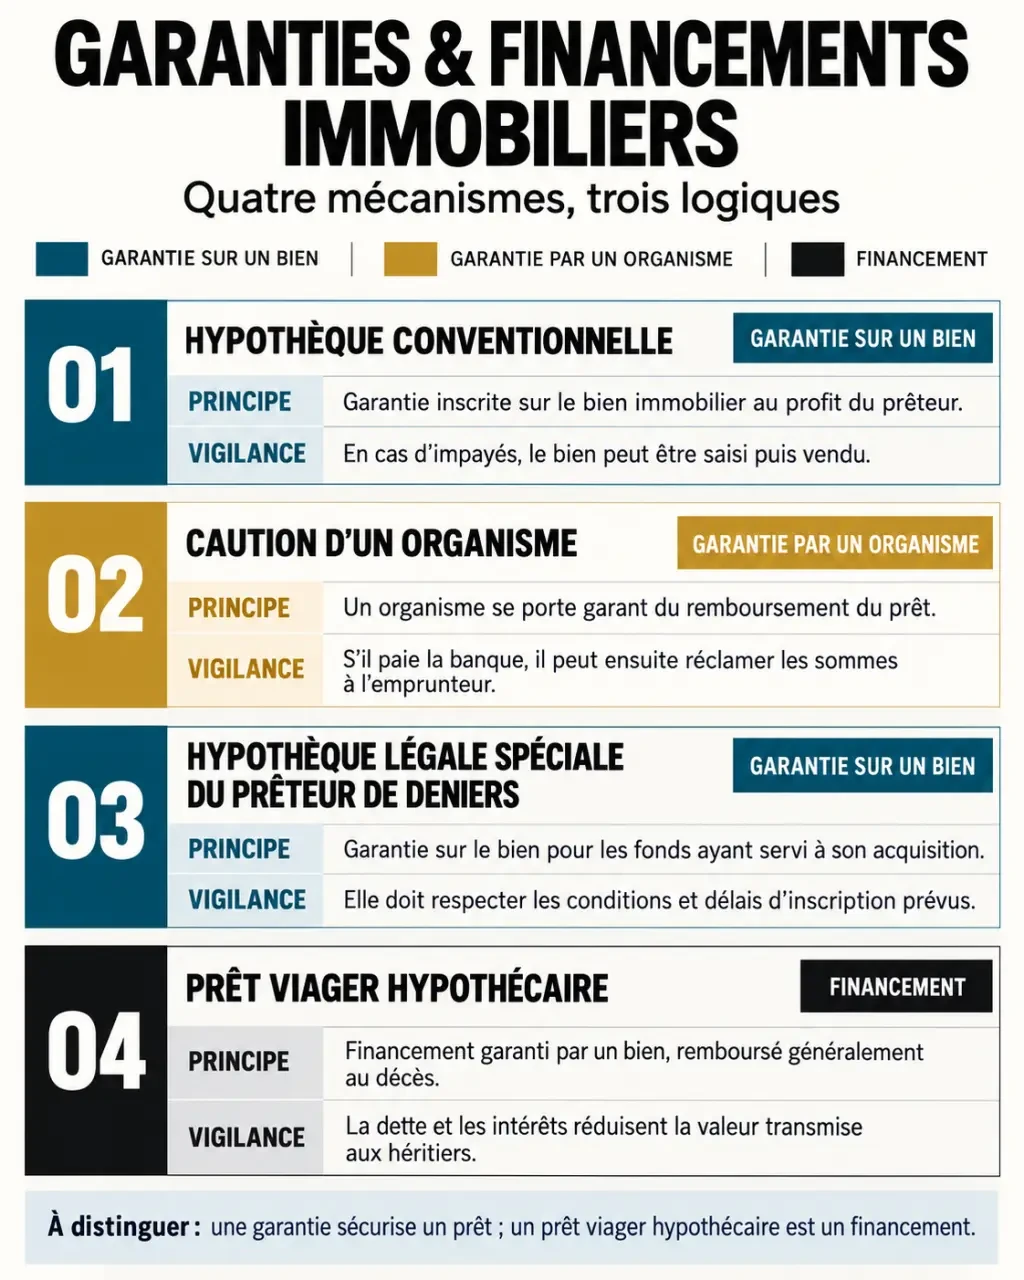
| Solution | Principle | Point of vigilance |
|---|---|---|
| Conventional mortgage | Real estate guarantees the debt. | Notarial fees and seizure risk. |
| Security of an organization | An organization guarantees credit from the lender. | Acceptance of the file and appeal against the borrower after payment. |
| Special legal mortgage of the money lender | Guarantee related to the financing of an acquisition, replacing the former PPD. | Limited scope; it is not suitable for any cash flow. |
| Mortgage life loan | Financing guaranteed by property, usually with reimbursement for death. | Accumulated interest and effect on transferred assets. |
For a limited need, also compare a work or personal loan: avoiding a real estate guarantee may be preferable, depending on the rate, duration and amount. Before signing, encrypt three scenarios: normal repayment, early resale and revenue decline. The right solution is the one that your budget can support, not just the one that your home guarantees.