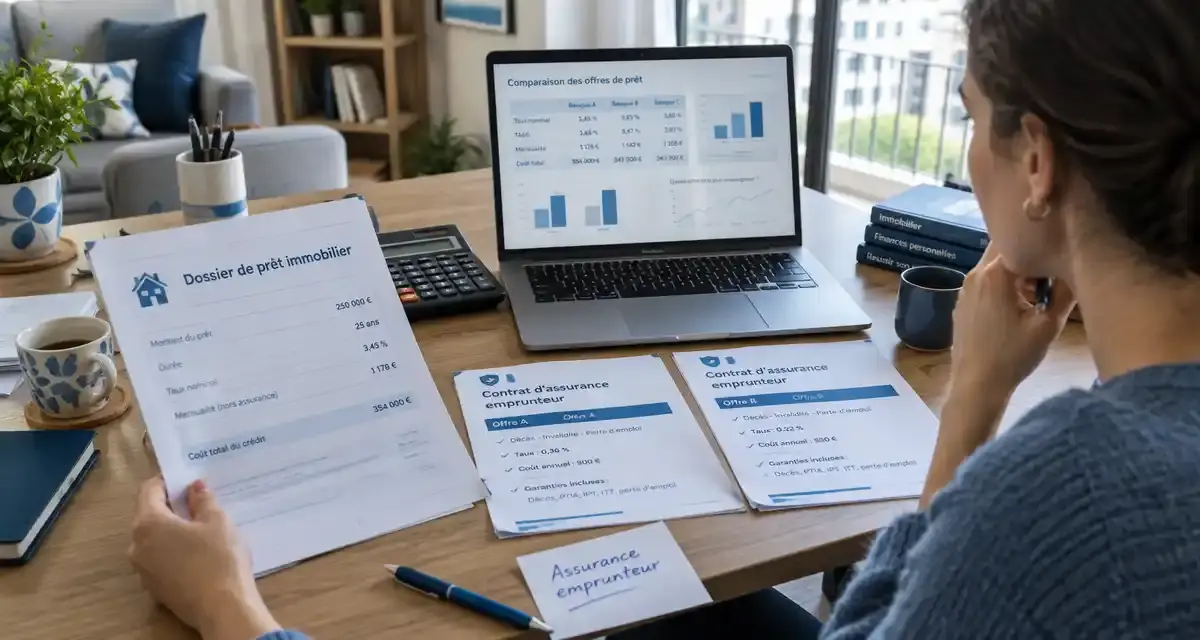
The change in borrower insurance can reduce the total cost of a real estate loan, sometimes without reaching the credit rate or renegotiating with the bank. The aim is not only to pay less: the new contract must properly cover the risks required by the lender and remain adapted to your personal situation.
Since the relaxation of the termination rules, the borrower has had real room for manoeuvre. It can compare, substitute its contract and have external insurance validated, provided that it complies with theequivalence of guarantees. To secure this step, Santiane is real estate loan insurance broker and can help analyze guarantees beyond the simple price displayed.
Why consider a change in borrower insurance?
Borrowing insurance accounts for a significant part of the total cost a real estate credit, especially when the loan runs over fifteen, twenty or twenty-five years. The contract proposed by the bank at the time of signature is often practical, but not always the most competitive. An individual contract can take better account of the borrower's age, health status, occupation or lifestyle.
Changing can also become relevant after a personal evolution. A person who quits smoking, changes his/her profession, repays part of the loan, or sees his/her remaining capital be reduced, may have an interest in doing so again. The right time is therefore not only the first year of the loan: it is also the one where the contract no longer corresponds to the real risk.
However, a purely tariff reading should be avoided. A lower contribution may hide more exclusions, less favourable compensation or longer deductible periods. The real gain is measured by comparing the Total cost remaining until the end of the loan and the solidity of the guarantees.
The regulatory framework for termination
Termination at any time
For real estate loans for residential or mixed use, the Lemoine law allows the cancellation of borrower insurance at any time, without waiting for an anniversary date. This has simplified the procedures: the borrower no longer has to calculate a complex notice window to change the contract.
The bank cannot refuse substitution for a simple commercial preference. It must verify whether the new contract has a level of collateral equivalent to that required when the loan is granted. If this condition is met, it must accept the change and transmit a amending the contract loan.
Equivalency of guarantees, central point of the file
Equivalency includes death, total and irreversible loss of autonomy, temporary incapacity for work, permanent disability and sometimes loss of employment if required. The insured quotes must also be consistent: a 100% covered couple cannot always replace their contract with a 50% coverage without the bank's agreement.
It is useful to compare the contract from several angles. For the borrower, the monthly contribution weighs in the budget. For the bank, it is the continuity of the repayment that counts. For the family, it is the protection of housing in the event of a life accident. This check avoids choosing attractive price insurance, but too low on a decisive guarantee.
Concrete steps to change without blocking your loan
- Recover Useful Documents : loan offer, amortization table, current contract, standardized information sheet and bank guarantee requirements.
- Compare several quotes : the tariff must be studied with exclusions, allowances, allowances and compensation methods.
- Enter the new conditional contract : it must be ready to replace the old, but the switch depends on the agreement of the bank.
- Send substitution request It must contain the new contract and the information to establish equivalence.
- Waiting for agreement and amendment The bank usually has ten working days to respond. In the event of acceptance, it cannot charge an alternative fee.
The main mistake is to terminate the old contract too early. There must be no broken coverage between the two insurances. Another common error is to send an incomplete file: lack of general conditions, poorly legible guarantees, different quotité or date of imprecise effect.
The criteria to compare before signing
A good comparison is not limited to the actual annual rate of insurance. It is necessary to analyse guarantees in detail, since two contracts at the same price can work very differently at the time of a disaster.
| Criteria | What to check |
|---|---|
| Method of calculation | Contribution on initial capital or capital remaining due, with impact on cost over time. |
| Incapacity for work | Definition of incapacity, deductible period and lump sum or compensation. |
| Invalidity | Thresholds, occupational exclusions and conditions of compensation. |
| Exclusions | Sports, travel, back or psychic pathologies, jobs at risk. |
| Quota | Distribution between co-borrowers and level of home protection. |
The role of a specialist broker is to translate these clauses into concrete consequences. It may identify any deviations that may lead to bank refusal, identify weakened collateral and calculate net gain over the remaining term of the loan. This support is particularly useful when the medical, professional or heritage record comes out of standard profiles.
Housing F and G: an additional point of vigilance
Property classified as F and G raises specific questions in a real estate project. Their energy performance may influence the financing strategy, the construction budget, the future value of the property and the borrower's ability to maintain its repayment plan. Even if borrower insurance covers primarily the person and not the energy quality of the housing, the whole file can be looked at with more attention.
For a purchase including renovation work, it is therefore prudent to compare insurance at the same time as the overall financial package. The cost of insurance, monthly payments, the rest to live and the work envelope must be consistent. On this subject, a lighting dedicated to theBorrowing insurance for housing F and G provides a better understanding of energy-intensive issues.
Before validating a change, the right reflex is to ask for a written comparison, guaranteed by guarantee, and then verify the effective date of the new contract. A successful change eases credit without creating a dead corner: same protection, optimized cost, folder accepted and no interruption of coverage.