You can change real estate loan insurance at any time, without waiting for the anniversary date of your contract. This is the main contribution of the Lemoine law, which also facilitates access to insurance for certain borrowers through the framed deletion of the medical questionnaire and a shortened right to forget. But this freedom retains an essential condition: the new contract must have a level of guarantees equivalent to that required by the bank.
What Lemoine law changes for your borrower insurance
The « new law » on real estate loan insurance generally means the Lemoine Act of 28 February 2022. Its main measures concern housing and mixed-use, professional and residential loans falling within its scope. It should therefore not be automatically transposed to all credit insurance.
Lemoine Law Quiz and Borrower Insurance
Test your knowledge in six questions.
A possible termination at any time
Since 1 June 2022 for new loan offers, and since 1 September 2022 for existing contracts, the borrower can replace his insurance without waiting for an annual maturity. It is no longer necessary to distinguish the first year from the next to exercise this right.
There are no charges or penalties for termination. On the other hand, it does not exempt from purchasing a suitable cover: changing insurance means organizing a substitution, not leaving the credit without protection. The choice may be made to an insurer outside the bank, subject to compliance with the required guarantees.
A freedom that also exists when the loan is subscribed
You do not have to automatically accept the insurance offered with the credit. The insurance delegation allows you to choose an individual contract from the start. The Lemoine law makes this choice easier to review afterwards, for example if you signed the bank insurance to quickly complete your acquisition.
The bank cannot raise the loan rate in return for accepting external insurance. Nor can it charge for the analysis of the proposed alternative contract or for the credit related to that change.
Medical Questionnaire: Check both conditions before comparing
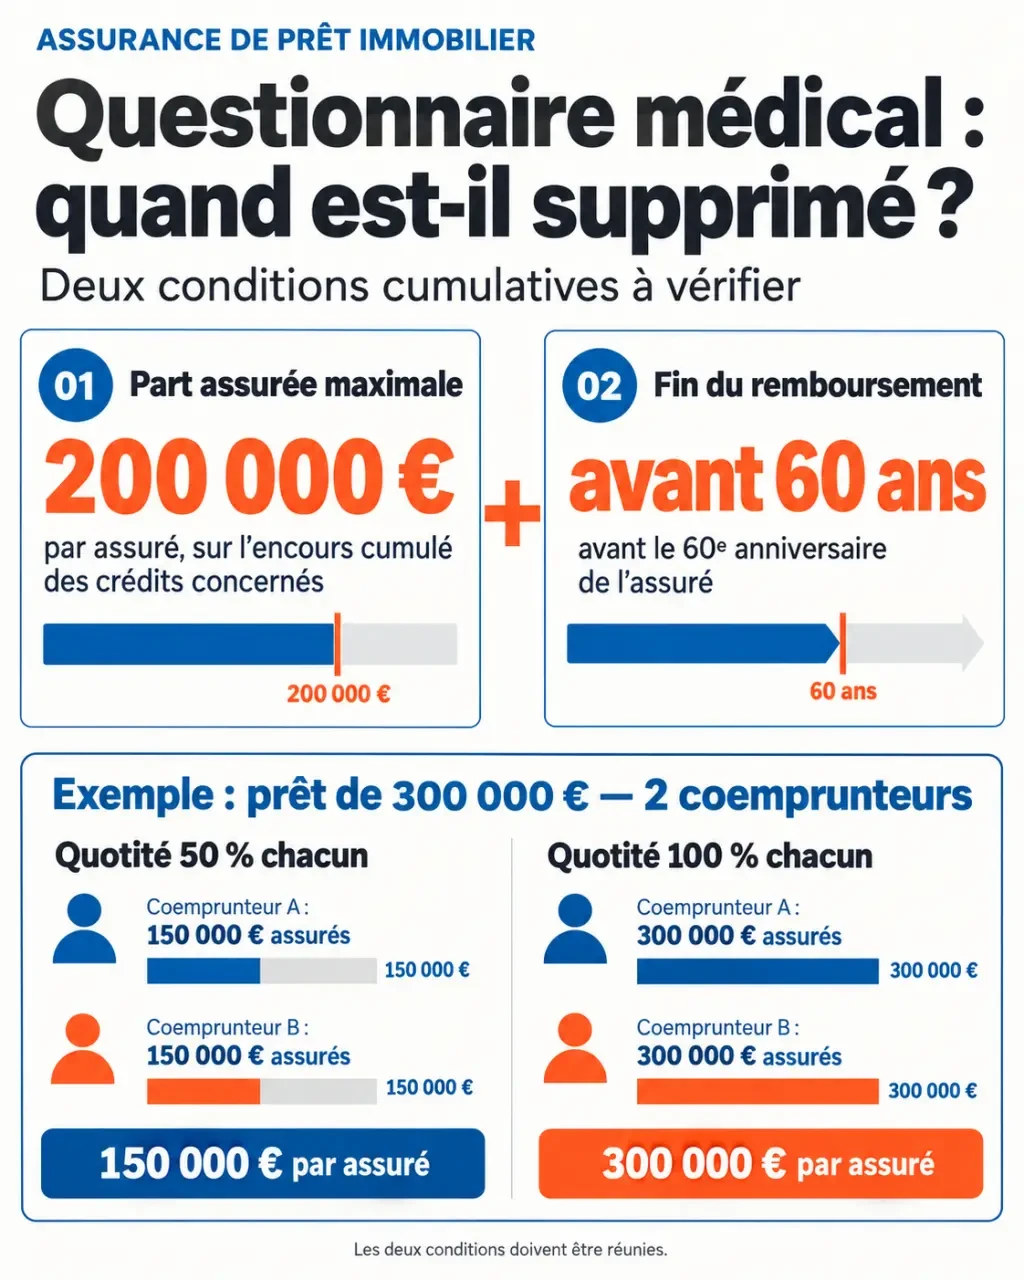
The deletion of the health questionnaire is not general. It depends on both the amount insured and the age at which the credit will be fully repaid. Where the legal conditions are met, the insurer may not request any health information or medical examination.
| Condition | Threshold |
|---|---|
| Guaranteed share of the cumulative outstanding amount of the appropriations concerned | Up to EUR 200 000 per insured person |
| End of repayment of credit | Before the insured person's 60th birthday |
These criteria are cumulative. Therefore, a small loan repaid after the 60th anniversary does not benefit from this exemption. Similarly, we must look at all the outstanding amounts involved, not just the new funding.
Quoting counts as much as the amount borrowed
The amount is the proportion of the loan covered for each borrower. For a couple borrowing 300 000 euros with 50 per cent coverage each, the insured share is 150 000 euros per person. In the absence of other relevant outstanding amounts, the amount criterion may be met. With a 100% coverage each, each person insures 300,000 euros: the threshold is exceeded.
However, it would be risky to reduce the quota only to avoid a questionnaire. In the event of the death of a 50 % insured co-borrower, the insurance shall in principle reimburse half of the remaining capital, subject to the terms of the contract. The survivor therefore retains a debt. Protection of the home must remain the first criterion of decision.
Health history: distinguishing the right to forget and the AERAS convention
The Lemoine law has reduced to five years the right to be forgotten for former cancer and hepatitis C patients, from the end of the therapeutic protocol and in the absence of relapse. Where the conditions are met, such background shall not be reported in the context concerned.
This mechanism remains useful when a medical questionnaire is needed, in particular because the loan exceeds the exemption thresholds. It does not mean that all old diseases can be omitted. If you have to fill out a questionnaire, answer the questions asked precisely while respecting your right not to declare the information covered by the right to forget.
The AERAS Convention, for « s »constitutes another device. It organises the examination of insurance applications with an aggravated health risk. Its reference grid also provides for access to insurance for certain pathologies and conditions without overprime or exclusion, or with framed limitations.
Three situations must therefore be distinguished: no questionnaire is allowed, a questionnaire is required, but some background is a right to be forgotten, or the file requires a medical study that can be considered by AERAS. This distinction avoids believing that a history automatically results in a refusal, or that it can always be ignored.
Change contract without creating a hole in your cover
The process begins with the recovery of your bank's requirements, including the personalized card specifying the expected guarantee criteria. Then compare contracts on the same basis: same borrowers, same quotities, same remaining duration and guarantees adapted to the financing.
- Request a full proposal with the tariff, contractual terms, exclusions and documents necessary for substitution.
- Send your request to the bank with the new contract and parts to verify the equivalence of guarantees.
- Wait for her decision. and coordinate the end dates of the old insurance and take effect of the new insurance.
- Check the supplement and the samples to ensure that the change is correctly applied.
The Bank has 10 working days from the date of receipt of the request for substitution to notify its decision. A refusal must be explicit and contain all of its grounds, including missing information or guarantees. If you receive an imprecise negative response, ask what criteria are not met before changing your file.
Do not terminate your current insurance in isolation until you have organized the replacement. Continuity of coverage is essential: an attractive tariff does not compensate for a period during which a claim would not be covered by any contract.
Good arbitration: real savings and real guarantees
A lower monthly contribution is not enough to demonstrate that an offer is better. Compare cost over the remaining term of the credit, taking into account the method of calculating contributions : initial capital or capital remaining due. If you are considering a future resale, also consider the cost over your likely holding horizon.
Pass each offer to the sieve of your daily life: physical work, self-employment, travel or sports. Exclusions, frankness and the definition of incapacity sometimes take exactly the situation that concerns you. A contract can satisfy the requirements of the bank while protecting you less well in your professional reality. This personal filtering therefore completes regulatory equivalence, without replacing it.
In particular, consider whether incapacity is assessed in relation to your profession or any occupation, whether compensation is lump sum or related to loss of income, and how old the guarantees apply. These differences may weigh more than a small contribution gap.
The law facilitates change, but does not make all contracts interchangeable. The right choice combines a verifiable economy, uninterrupted coverage and guarantees consistent with your situation. Start by putting together your current contract, your depreciation chart and the requirements of the bank: these are the three useful pieces to compare seriously.