To ensure your first home, compare the price, but also the deductible, the goods covered and the conditions for issuing the certificate. A young home insurance can be suitable for both a student and a young asset, according to the criteria of the insurer. The right contract must match your accommodation, lease and the amount you could actually pay after a claim.
Check your eligibility before requesting a quote
Young housing insurance is a commercial formula for young occupants, not a separate legal category. Each insurer sets its conditions: age, type of housing, number of rooms or status of occupation. A student formula may require academic or academic status, unlike some offers open to active youth.
StudyAssur announces an offer for 18 to 32 years, independent of professional status: students, employees, temporary workers, job seekers, freelancers or persons undergoing retraining may thus be concerned. Crédit Agricole presents a young formula for 18 to 30 years. Check the conditions applicable to your situation and what becomes of the contract when you exceed the age limit.
Housing and occupation status count as much as age
Room, studio, apartment or house, empty or furnished rental: precisely inform the property to be insured. StudyAssur announces housing of 1 to 6 pieces. A room in a university residence, a sub-lease or a temporary occupation requires a special check; they are not automatically accepted by all forms.
In France, the tenant of a dwelling constituting his principal residence must generally be insured against rental risks, including fire, explosion and water damage. The lessor can apply for a certificate upon handing over the keys, and each year thereafter. If you are staying with your parents, check your coverage in their contract before you purchase separate insurance.
Compare the annual cost and what will remain at your expense
StudyAssur displays a price from 53 € TTC per year, also presented from 4.42 € per month. This call price is not a quote for all dwellings. The price depends in particular on the address, the area, the guarantees and the movable capital chosen. Compare the annual total, any fees and payment terms.
Do not rate estimates on their own. One deductible is the amount that remains at your expense under the terms of the contract; one ceiling limit compensation. A low fee can therefore be less interesting if a leak or fire leaves you with a difficult expense to absorb.
| Point to compare | Concrete benchmark | Useful verification |
|---|---|---|
| Franchise | MAIF mentions 100 € for fire and explosion. | Check the amount of each guarantee. |
| Climate events | Franchise of 100 € or 380 € according to the events at MAIF. | Identify precisely the regime applicable to the claim. |
| Capital | StudyAssur offers 5,000 € 20 000 €. | Evaluate all assets, not just furniture. |
| Special ceilings | Limits of 1,000 € for cellars and outbuildings or leaking, and 500 € for watches and jewellery are mentioned in MAIF warranties. | Read the sub-ceilings and conditions of the proposed contract. |
Your precautionary savings are the invisible basis of this choice. If you cannot mobilize the franchise without compromising your rent, a slightly more expensive but less demanding formula after a disaster deserves to be studied. Compare two budgets: the one for the year without incident and the one for the month you have to replace your business while bearing the rest.
Protecting your business, not just satisfying the lessor
Rental risk coverage protects your liability for certain damage to the rented accommodation. It is not necessarily enough to compensate your own business or damage to neighbours. One multi-hazard housing combines several protections, the perimeter of which varies. Civil privacy, when included, involves other damage to third parties under the conditions provided for.
Guarantees to be read first
Examine the fire and explosion, water damage and weather events, then cover the furniture. For a leak, distinguish the damage caused, the search costs and the repair of the defective element: a guarantee does not necessarily cover these three expenses. Theft, ice breakage or electrical damage must also be checked, without assuming that they are included.
Climate events include their own definitions. MAIF mentions in particular, under a specific condition, an average speed of 145 km/h or gusts of 215 km/h. These thresholds do not summarize all the storm cover: the event concerned must be identified and the supporting documentation required. A natural disaster is also a separate framework.
Declare realistic movable capital
Inventory furniture, clothing, appliances, computer equipment, multimedia and sports equipment. Keep invoices and photographs. Then check whether the compensation takes into account the outdated or provides a value of nine under conditions. A computer covered in the housing is not necessarily against theft or accidental breakage.
Finally, read the exclusions: lack of maintenance, special infiltrations, prolonged absence or flight protection requirements may limit the handling. Jewellery, valuables and goods stored in cellars require special attention, even when overall furniture capital seems sufficient.
Co-location, match the contract to the lease
With a joint lease, a single contract may cover several roommates if the insurer so provides. StudyAssur announces coverage up to 6 roommates. Ensure that all affected occupants are declared and that their responsibilities and personal property are within the guaranteed perimeter. The name of the only subscriber does not prove that all are protected.
With individual leases, each roommate must ensure that he/she is occupied according to the requirements of his/her lease. Ask how the private room and shared rooms are treated. Separate contracts may require clarification of responsibilities and guarantees for common assets.
Upon departure or arrival of a roommate, notify the insurer and request an updated certificate if necessary. Also, re-evaluate the collective furniture: a sofa or refrigerator purchased from several must not be forgotten. Divide the contribution between occupants is not enough to organise their coverage.
Subscribe and obtain a usable certificate from entry
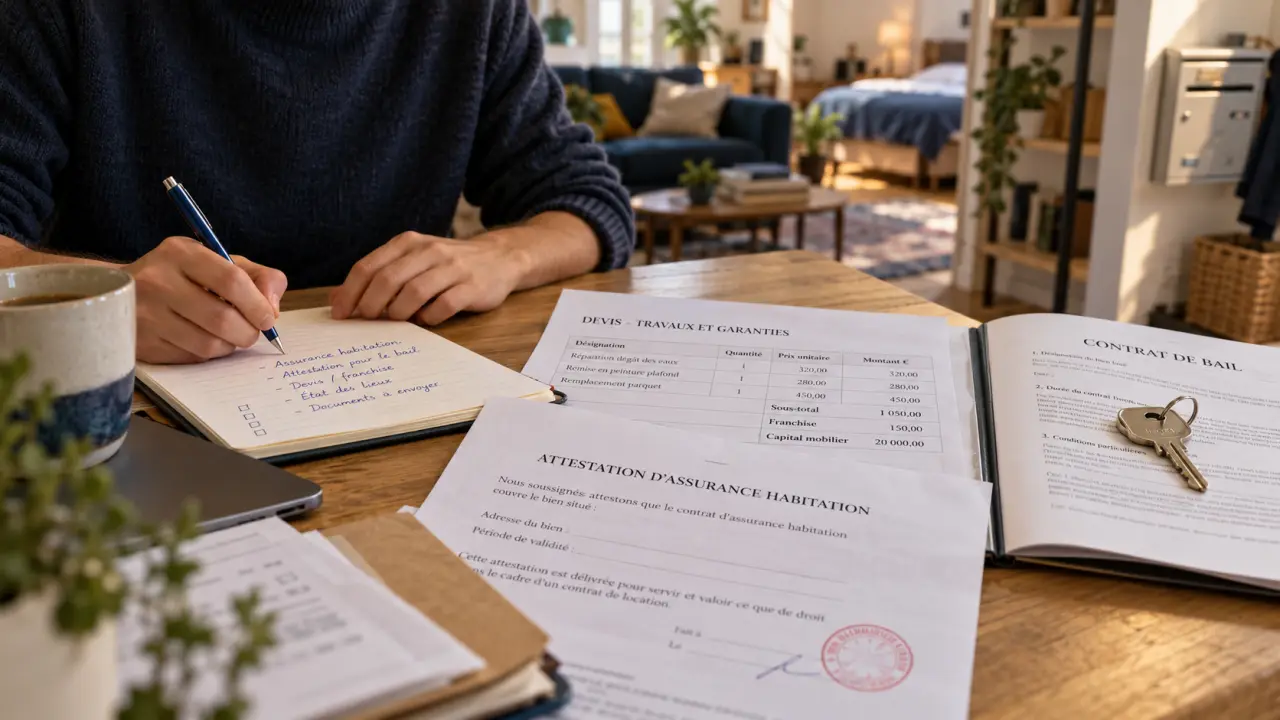
Prepare full address, desired effect date, surface area, number of rooms, type of lease, occupants and value of property. According to the insurer, an identification document, a lease, proof of status or bank details may be requested. StudyAssur announces an unsupported subscription and immediate certification; This does not exempt accurate statements.
- Ask for quotes with the same characteristics and the same furniture capital.
- Check guarantees, deductibles, ceilings and exclusions before validation.
- Choose an effect at the latest when the keys are delivered.
- Download the certificate and check the address and the occupants mentioned.
A certificate issued immediately does not necessarily mean immediate coverage the effective date of the contract is authentic. Keep the contract documents and assistance contact information. In case of relocation, change of occupant or loss, contact the insurer promptly for the applicable procedures and deadlines. This will provide you with adequate protection, not just a document to pass on to the lessor.