Allianz Borrowing Insurance can replace the insurance offered by your bank, provided it meets its collateral requirements. Its interest is measured on two points: the total cost to your profile and the protection actually provided in case of a disaster. Before asking for a quote, gather the features of the loan and the Standardized Bank Information Sheet: they will allow a useful comparison, beyond the savings displayed.
An alternative to bank insurance, to compare with equal coverage
Real estate loan insurance takes place when a covered event threatens repayment: death, loss of autonomy, incapacity for work or disability, according to the guarantees subscribed. The insurer shall then take over part of the outstanding maturities or capital, within the limits of the contract.
You can choose the group contract offered by the lending institution or alternative insurance, such as that of Allianz. The individual contract allows the cover to be adapted to the borrower's profile. However, it is not automatically cheaper or more systematically protective bank insurance.
Allianz puts forward a guaranteed rate over the duration of the loan, with an exception announced for the job loss option, as well as an absence of file fees. Allianz and Meilleurtaux also mention a reduction in 10% for two or more borrowers. Request that its conditions of application be included in your proposal.
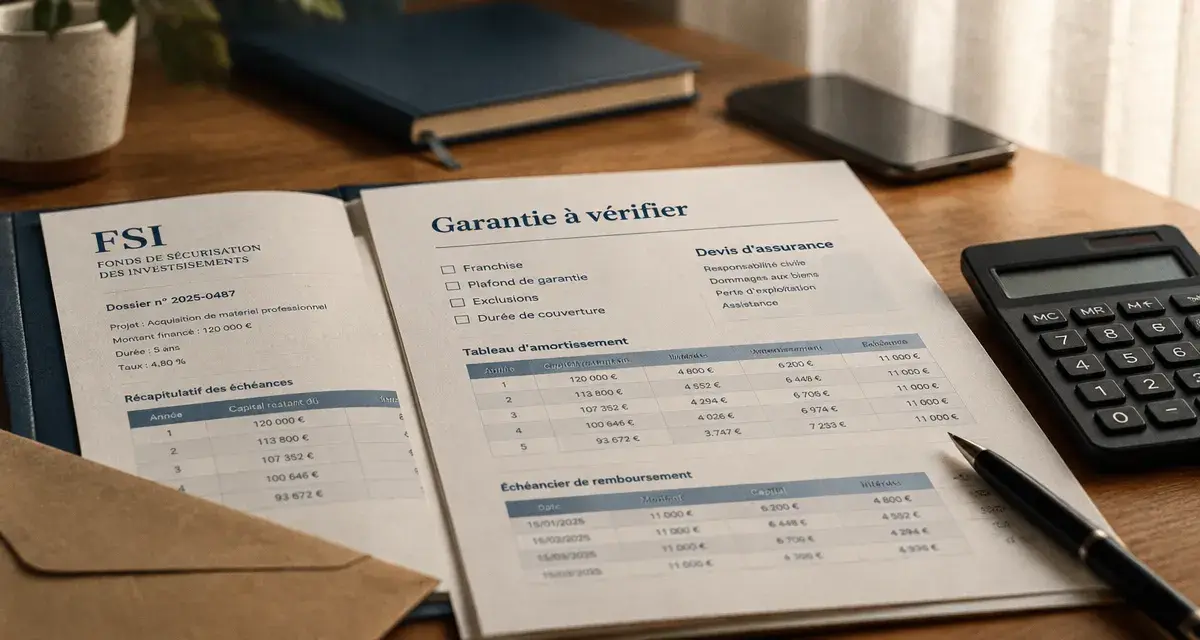
The right starting point remains the Standardized Information Sheet, or FSI, issued by the bank. It sets out the requirements to be met. Equivalency does not mean that contracts must be identical: the alternative contract must meet the criteria adopted by the lender.
Guarantees: look at the conditions before the titles
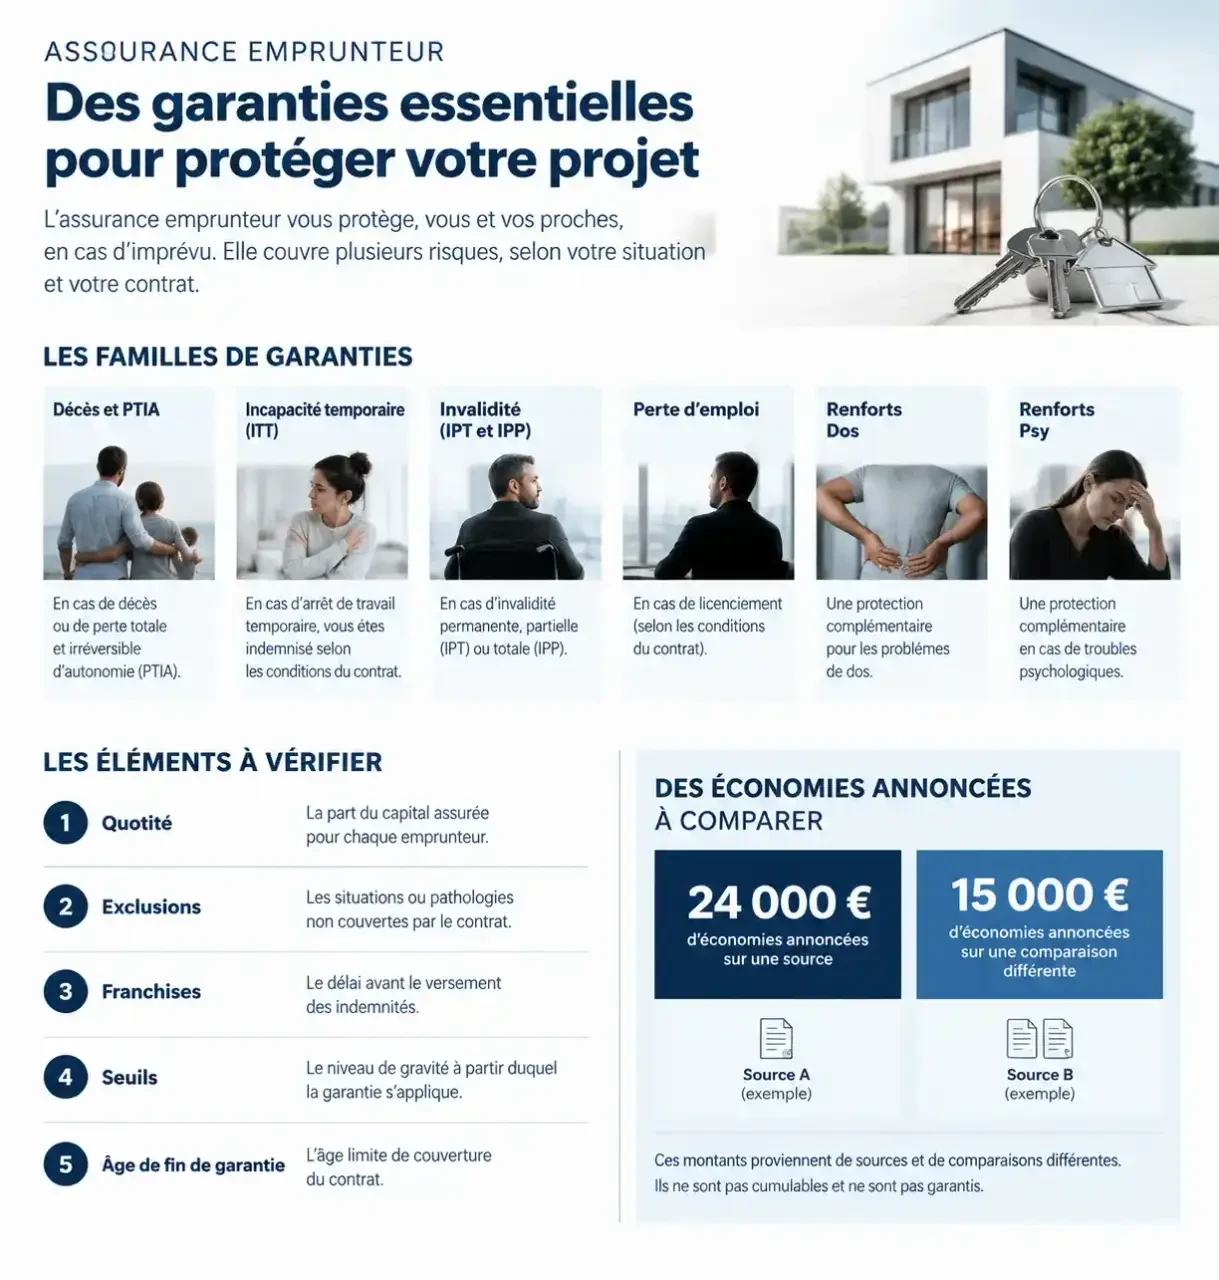
Death and total and irreversible loss of autonomy, called PTIA, form the basis of the coverage presented. Other guarantees depend on the banking formula, options and requirements. Their presence in a commercial presentation does not mean that they are all included in your estimate.
| Guarantee cited | Role | Point to be checked |
|---|---|---|
| Death and PTIA | Capital protection according to the event covered | Quoting, exclusions and end-of-guarantee age |
| ITT and ITP | Total or partial temporary incapacity | Definition of disability, franchise and partial recovery |
| IPT and IPP | Total or partial permanent disability | Scale, threshold and method of compensation |
| Loss of employment | Unemployment protection | Accepted situations, deficiency, duration and ceiling |
| Back and Psy | Development of the coverage of certain diseases | Medical conditions and restrictions maintained |
| Dreaded diseases | Protection related to certain defined diseases | Contract list and expected performance |
Also mentioned are the death-PTIA coverage before the release of funds and a specific AERAS disability guarantee. Their availability must be confirmed for your file. For IPP, Meilleurrates evokes support from 33% invalidity in his comparative example: this threshold alone is not enough to determine your compensation.
A blanket looks like a fabric: two fabrics may seem identical, but yield to different places. In a contract, the « seams » are definitions of disability, exclusions and deductibles. Test a concrete situation — e.g. stopping for back disease without hospitalization — and ask if it would be covered, from when and for what amount. You will find invisible differences in a simple list of guarantees.
On the other hand, the quota determines the protection of each individual.
The amount corresponds to the portion of the loan insured on each head. A breakdown of 50% per person means that a covered loss affecting one of the co-borrowers triggers a limited liability under the contract. 100% coverage on each of them protects more, but generally increases the cost. For a borrower alone, the amount requested is usually 100%. Choose it based on the income remaining at home, not just the contribution.
Prices and savings: compare the remaining cost, not a maximum promise
Allianz announces until EUR 24,000 in savings on its product page. Better rates mention up to EUR 15 000 and advances a reduction of up to 70 % for an individual contract compared to a group contract. These figures represent different comparisons: they are neither cumulative nor guaranteed for your loan.
The rate depends in particular on age, the amount borrowed, the duration and, where possible, the health situation. Guarantees and quotes also influence the contribution. A low monthly payment can simply correspond to a more limited protection.
- Compare over the same duration: in case of change, keep the remaining period of the loan.
- Keep the same quotities: a decline in coverage is not an economy with equal protection.
- Review the schedule: check whether contributions are constant or evolving.
- Look at the total cost and the AETD: the effective annual rate of insurance supplements the reading of the amount in euro.
The example Best rate for a 30 year old borrower, a credit of EUR 200 000 over 20 years at the non-insurance rate of 3.85 %, mentions EUR 674 per month of insurance. This periodicity requires verification: this amount is not a reliable basis for estimating your contribution. Prefer a nominative proposal with its schedule.
Health and assistance: the conditions to be clarified before accession
Medical formalities are not the same for all. The absence of a questionnaire shall apply subject to conditions, in particular where the insured share of the cumulative amount does not exceed EUR 200 000 per person and that the repayment ends before the 60th anniversary. These thresholds are also recalled by Better rates. So do not confuse the total amount of a two-way loan with the insured share of each.
Without exemption, a health statement or questionnaire may be requested. Better rates suggest a simplified questionnaire for certain profiles up to 45 years and 400 000 euros of insured capital. Confirm the applicable route. Its response announced in 10 minutes concerning certain dossiers, not universal acceptance within that time limit.
If there is an increased health risk, ask how the AERAS Convention can intervene. When a questionnaire is required, answer the questions specifically and use the confidential medical circuit.
The services mentioned include career guidance, return to employment and home help. Better rates refers to a ceiling of EUR 200 per year for certain home services in the event of serious health problems. Check the triggers: assistance completes the insurance, but does not replace the repayment of the maturities.
Go to Allianz: from quote to validated substitution
The delegation consisted of choosing external insurance from the bank as soon as financing was available. Substitution replaces current insurance. For the real estate loans concerned, the Lemoine law allows the change at any time, subject to the equivalence of guarantees.
- Prepare the folder: FSI, loan characteristics, amortization table, guarantees and current quotas.
- Ask for a quote Allianz : online or with an advisor, with notice and schedule of contributions.
- Check equivalence: Allianz announces a certificate to facilitate this examination.
- Submit the complete application: indicate the steps taken by the adviser and the remaining documents.
- Coordinate the dates: wait for validation and organize the effect without interruption of coverage.
Allianz indicates a bank delay of 10 working days to process the substitution application. Examination of the alternative contract shall not entail any additional costs; a refusal must be substantiated in writing according to the equivalence criteria.
Before signing, ask for a written comparison between remaining costs, guarantees, allowances and exclusions. It is this document, more than the maximum economy displayed, that makes it possible to decide whether the Allianz offer is suitable for your credit and home.