
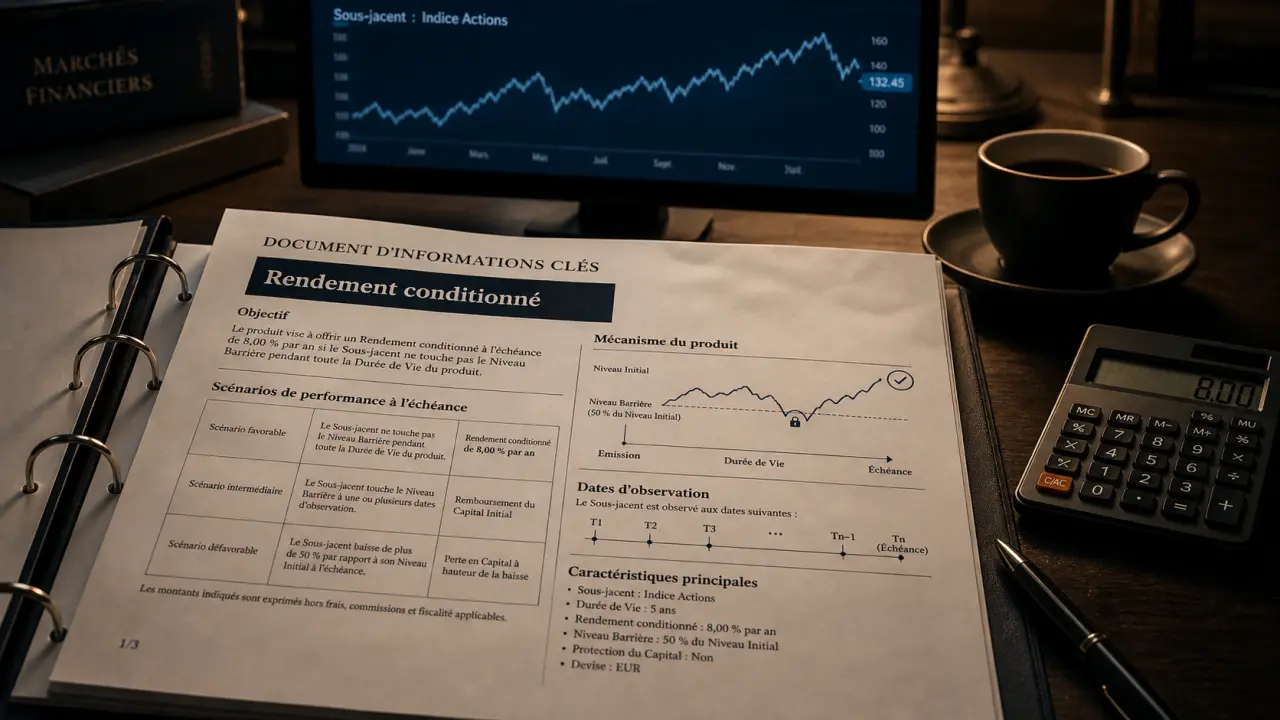

A structured product is a financial investment built around a predefined scenario, for example the evolution of an index, a share, a basket of securities or another underlying asset. It can offer a potential yield higher than that of more conventional investments, but with a more complex formula, often long investment duration and risk of capital loss. To understand this, we must look at three points: the underlying, the performance formula and the actual level of protection.
Definition of a structured product: an investment built around a scenario
The definition of a structured product lies in its construction: it is a financial product assembled from several bricks. It usually combines debt support, issued by a bank or financial institution, and one or more derivative instruments, often options. This combination offers a different return/risk ratio for direct investment in shares, bonds or conventional funds.
Quiz : Structural products
In concrete terms, the investor is not only betting on the rise or fall of a market. He subscribes to a precise formula, known from the beginning, which indicates what happens if the underlying rises, stagnates, decreases moderately or falls sharply. The yield is therefore conditional on a predefined market scenario, and not guaranteed in all cases.
Components to be identified from the start
A structured product is based on a few essential concepts. The underlying can be a share, a stock index, a stock basket, a composite index, a commodity or sometimes another financial asset. The lifetime is often between 2 and 10 years, sometimes up to 12 years, with a typical maturity of 5 to 10 years. The mathematical formula sets the conditions for repayment, coupon and capital protection.
The subscription is often made during a Limited marketing window, sometimes a few weeks. This is very important because unlike a share or ETF that can be purchased continuously on a market, a structured product is generally offered over a specified period of time, with fixed conditions at the time of its creation.
How performance works: coupon, barrier and maturity
The functioning of a structured product may seem technical, but it follows a fairly legible logic: at certain observation dates, the value of the underlying is compared to its initial level. Depending on the result, the product can pay a coupon, be repaid early or continue until the final maturity.
The performance formula is not a simple promise
The potential yield often takes the form of a coupon, i.e. a gain paid if certain conditions are met. For example, a product may provide for the payment of a coupon if an index remains above a given threshold at a compliance date. In other cases, the gain is calculated at maturity only, depending on the underlying performance.
A frequent error must therefore be avoided: read the coupon displayed as a guaranteed rate. The coupon is usually linked to a condition. If the expected scenario does not occur, the yield can be reduced, delayed or even zero according to the formula set out in the Key Information Document.
Capital protection: total, partial or non-existent
Capital protection is one of the main arguments of structured products, but it must be read with precision. It may be total, partial or null. It may also apply only at maturity, and only if the underlying does not pass a protection barrier. In other words, a moderate fall in the market can be absorbed by the structure, while a sharper fall can result in a loss.
The word "protection" should therefore not be confused with "absolute guarantee". Maturity protection does not necessarily protect in case of pre-term resale. Similarly, if the barrier is crossed under the conditions laid down, the investor may suffer a capital loss, sometimes significant.
A good reflex is to look at the product from the simplest question: in what concrete case is capital preserved, and in what case is it no longer? This reading avoids being seduced by a high coupon without measuring adverse scenarios. If a temporary decrease of 20%, 30% or more would cause you to sell in an emergency, the structure may be less suitable than it looks, even if the central scenario seems reassuring.
Benefits and limitations over conventional investments
Structured products can be of interest when they meet a specific objective: to seek a potential return, to diversify a wealth, or to frame a risk-taking in a given market. However, they are neither secure booklets, nor conventional equity funds, nor simple obligations.
Master the Key Information Document (ICD) before investing · Learn how to decrypt this essential document to assess the risks and characteristics of a financial product before subscription.
| Placement | Main logic | Point of vigilance |
|---|---|---|
| Structured product | Yield conditioned by a scenario and formula known from subscription | Capital loss risk, liquidity, formula complexity |
| Funds in euro | Search for security and stability in a life insurance contract | Generally more limited performance |
| Actions | Direct participation in an enterprise's up or down | High volatility and lack of integrated protection |
| ETF | Diverse exposure to an index or market | Market-dependent performance without specific protection formula |
The main advantages
The first advantage is that visibility the form of return, dates of compliance, thresholds and repayment conditions are known at subscription. The second is the Personalisation of risk Some products seek to protect capital at maturity, others favour potential returns, and others seek directional exposure to a market.
Structured products can also provide access to various asset classes, such as stock indices, stock baskets or raw materials. For an already diversified investor, they may occupy a complementary position, provided that they do not concentrate an excessive share of the assets on the same issuer or underlying.
Risks not to be minimized
The most obvious risk is the capital loss. It depends on the formula, the level of protection and the evolution of the underlying. There is also a liquidity risk : resale before maturity can be made under unfavourable conditions, with a price below the original value. The credit risk also counts, as repayment depends on the issuer's ability to meet its commitments.
Finally, complexity is a risk in itself. A product may look attractive because it has a high coupon, but this coupon often pays for constraints: long duration, lower or more demanding protection barrier, volatile underlying, less likely scenario. The potential performance must always be read against the accepted risk.
Types of structured products and examples of use
There are many forms of structured products, but there are two large families: yield products and directional products. The former often seek to pay a coupon if the market remains in an acceptable area. The latter are more likely to benefit from a market movement, up or in other configurations provided for in the formula.
Performance product
A return product may be suitable for an investor who anticipates a moderate stability or increase in the underlying. The promise is not to capture the full performance of the market, but to get a coupon if the conditions are met. In return, the gain can be capped: if the index increases sharply, the investor does not necessarily benefit from all this increase.
Directional product
A directional product is more exposed to a market scenario. It can be designed to accompany an increase in an index, a basket of shares or a specific asset. It can offer a form of participation in performance, sometimes with partial protection at maturity. This type of product requires a good understanding of the underlying and the investment horizon.
In both cases, the concrete example must always be linked to the Chione. The Key Information Document is mandatory and regulated by regulation. It includes essential characteristics, risks, performance scenarios and costs. The AMF regularly recalls the importance of understanding the product before subscribing, especially when the formula is complex.
For which investor and under what framework?
Structured products are not intended for all savers. They can suit an investor who already has a precautionary saving, accepts a potential blockage period of several years and understands that capital is not always guaranteed. They are often used in a heritage logic, in addition to other media.
Questions to ask before signing
Before subscription, it is useful to check some simple points:
- What is the exact underlying and why was it chosen?
- What is the expected duration: 2, 5, 10 years or more?
- Is capital protection total, partial or non-existent?
- Does the protection apply only to the expiry date?
- In what cases is the coupon paid, deferred or lost?
- What happens in case of resale before expiry?
- What is the soundness of the issuer and the level of fees?
Taxation depends on the holding envelope and the investor's position: securities account, life insurance, capitalization contract or other framework. This is a point to consider before comparing two products, as an attractive gross yield can give a different net result depending on the envelope used.
In summary, a structured product is relevant if it meets a specific objective, with an accepted duration, an understood risk and a readable formula. It becomes problematic when it is chosen solely for its displayed coupon, without analysis of the underlying, the protection barrier, liquidity and credit risk. The right approach is to compare it to simpler solutions, then decide whether it actually brings something to your overall allocation.