
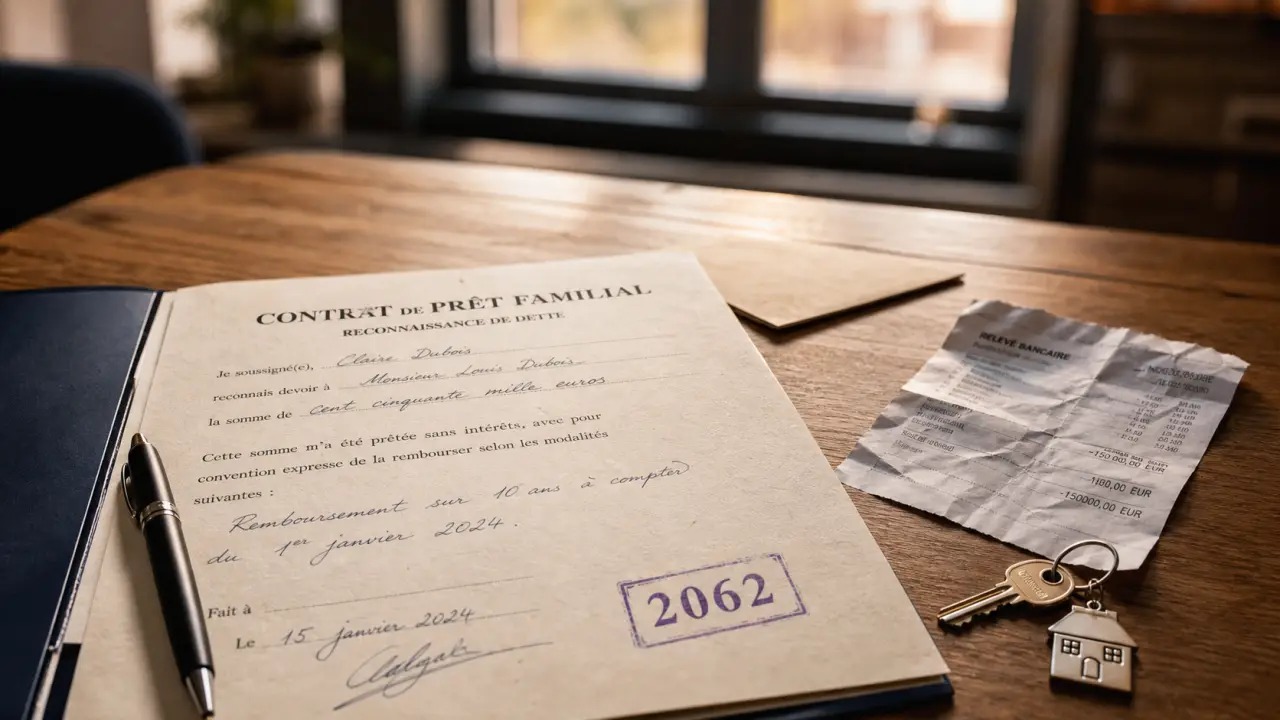

A family loan can finance a real estate purchase, help a child start a project, or absorb an unforeseen event. The question of the maximum amount comes back quickly: can you lend 10,000 €50,000 € or more to a loved one? In French law, there is no single statutory ceiling. On the other hand, the higher the amount, the more evidence, tax returns and precautions become necessary.
Family loan: no legal ceiling, but a real logic of proof
The family loan is a loan of money granted between members of the same family: parents and children, grandparents and grandchildren, siblings, spouses or other relatives. It can also take the form of a loan between individuals when the family relationship is further away. Its peculiarity lies in the trust between the parties, but legally, there remains a loan: a sum is repaid and then it must be repaid in accordance with the arrangements laid down.
Family Loan Quiz
The maximum amount of a family loan is therefore not fixed by law. A family can arrange a loan of 3,000 €10 000 €50 000 € or more, provided that the transaction remains consistent with the financial capacity of the lender and the borrower. A parent may lend a large sum to his or her child to supplement a property contribution, for example, without this being prohibited in principle.
The real limit is not a numerical ceiling, but the ability to demonstrate that it is a loan rather than a disguised donation. If the money is never repaid, if no date is foreseen, if no writing exists or if the heirs dispute the transaction, the tax officer or a judge may question the actual nature of the transfer.
Family loan or donation: the difference is reimbursement
In a donation, the amount is transferred without consideration for repayment. In a loan, the borrower undertakes to return the money, with or without interest. This difference must be clearly reflected in the documents: amount lent, identity of the parties, schedule, duration, possible interest rates, terms of early repayment. The higher the sum, the more this precision protects both sides.
The thresholds to know : 1,500 € and 5,000 € change formalities
Even without a legal ceiling, two thresholds change the obligations: 1 500 € for writing and 5 000 € for the tax return. These thresholds do not limit the amount of the loan, but they determine the formalities to be followed. They are mainly used to secure evidence and avoid a loan being confused with a gift.
Reporting your loan contracts: the official form 2062 · Access the official form to easily report your loan contracts to the tax administration.
| Amount of family loan | Main formality | Practical advice |
|---|---|---|
| Up to 1 500 € | Written not mandatory but recommended | Keep a bank record and a clear message about the purpose of the transfer |
| Over 1,500 € | Mandatory | Write a debt recognition or loan contract |
| Over 5,000 € | Compulsory tax declaration | Use Tax Form No. 2062 |
| High amount, e.g. 50,000 € | Recommended enhanced formalities | Provide a detailed contract or notary |
Over 1,500 € : written becomes obligatory
Once the loan exceeds 1,500 €, a writing is necessary. It can take the form of a debt recognition signed by the borrower or Family loan contract signed by both parties. The objective is simple: to avoid a payment being presented later as a gift, an inheritance advance or an unreimbursable aid.
In order to be useful, the written text must indicate as a minimum the amount in figures and letters, the date of delivery of the funds, the contact details of the lender and borrower, the duration of the loan, the terms of repayment and whether or not interest is present. A bank transfer remains preferable to a cash discount, as it leaves a clear trace.
Over 5,000 € : tax return is required
When a family loan exceeds 5,000 €, it must be reported to the tax administration by means of Form No. 2062. This declaration does not mean that the loan becomes taxable in itself. It is primarily used to inform the administration of the existence of the loan and to avoid confusion with an undeclared donation.
The form can be searched on the official tax website: impots.gouv.fr. In practice, this formality is particularly important for loans that finance a real estate contribution, work, business start-up or significant family support.
Writing a strong contract: what really needs to be anticipated
A good family loan contract does not need to be complicated, but it must be complete. It protects the lender, who can prove his debt, and the borrower, who can prove that it was not a taxable or questionable gift. A simple but precise document already avoids many difficulties.
The following clauses should be included in a clear document:
- the complete identity of the lender and borrower;
- the exact amount of the loan;
- the date and method of disbursement of funds;
- the duration of the loan and the final repayment date;
- The schedule, with monthly payments, annual repayment or final repayment;
- the interest rate, even if it is set at 0 % ;
- conditions for early repayment;
- the consequences of delay or non-reimbursement;
- the signature of the parties, with date.
The contract must also remain legible. An overly vague clause creates discussion when the evidence becomes useful. In a family, tensions rarely arise at the time of the transfer, but rather at the time of divorce, death, poorly financed property purchase or disagreement between heirs. Predicting the maturity, proof of payment and the fate of the loan in the event of death is not an excessive caution, it is a way of protecting everyone.
With or without interests: a choice to be clarified
A family loan can be made without interest. It is common when a parent helps a child. But this gratuity must be expressly mentioned in the contract. If interest is provided, it must be reported by the lender as income. The borrower, for its part, must respect the payments provided in order to avoid that the transaction resembles a disguised heritage transmission.
Notary and registration: when to consider them
The use of a notary is not always compulsory, but it becomes recommended for high amounts, recomposed families, sensitive estate situations or loans related to a real estate purchase. An authentic act provides for greater legal certainty and provides a date Operation.
Registration of the act is possible, even when it is not compulsory. It officially proves the date of the loan, which may be useful if an heir later disputes the existence or conditions of the repayment.
Risks if the family loan is poorly formalized
The main risk is donation requalification. If the tax administration considers that the refund was not real or never envisaged, it may consider that the given amount must be treated as a donation, with the corresponding tax consequences. This risk increases when the loan is old, unpaid, undeclared or unwritten.
The second risk is family. A loan of 10,000 € may already create tensions if the brothers and sisters do not have the same information. A loan of 50,000 € may become a major subject at the time of succession, especially if the borrower is also an heir. Other heirs may ask whether the sum is to be repaid to the estate or taken into account in the division.
The third risk concerns the lender himself. Lending a large sum without a repayment schedule may weaken its assets, particularly in retirement or in case of liquidity. Therefore, prior to lending, it must be verified that the amount remains consistent with its expenditures, projects and contingencies.
What happens in case of non-reimbursement?
If a contract exists, the lender has a basis for claiming the refund. He may first amicably restart the borrower and then formalize his request in writing. In the absence of a solution, legal action may be considered. Without writing, the evidence becomes much more difficult, especially beyond 1,500 €.
In the event of the death of the lender, the debt enters into the estate: the borrower may have to repay the sum to the heirs or see this debt taken into account in the division. Again, a specific document prevents family memory from replacing legal evidence.
Practical examples for setting the right level of formalities
For a loan of 2,000 € To help a child pay a rental deposit, a simple writing is usually enough: amount, date, refund in a few monthly instalments and signature. Although the relationship is excellent, this document avoids misunderstandings and establishes a clear basis.
For a loan of 10,000 € financing a car or training, a realistic schedule must be provided and the loan declared if the threshold of 5,000 € is out of date. Form 2062 then becomes an essential formality, in addition to the contract or the recognition of debt.
For a loan of 50,000 € to supplement a real estate contribution, it is better to draft a detailed contract and consider the intervention of a notary. The stake goes beyond just one-off assistance: the loan can influence the borrower's property situation, the relationship between heirs and the tax analysis of the transaction.
Before paying out the funds, the safest method is to verify the lender's financial capacity, set a realistic term, write down the writing before the transfer, declare the loan beyond 5,000 €, keep proof of repayment and inform the persons concerned when the succession can be affected. Family loans remain a flexible and useful tool, without becoming a source of conflict.