
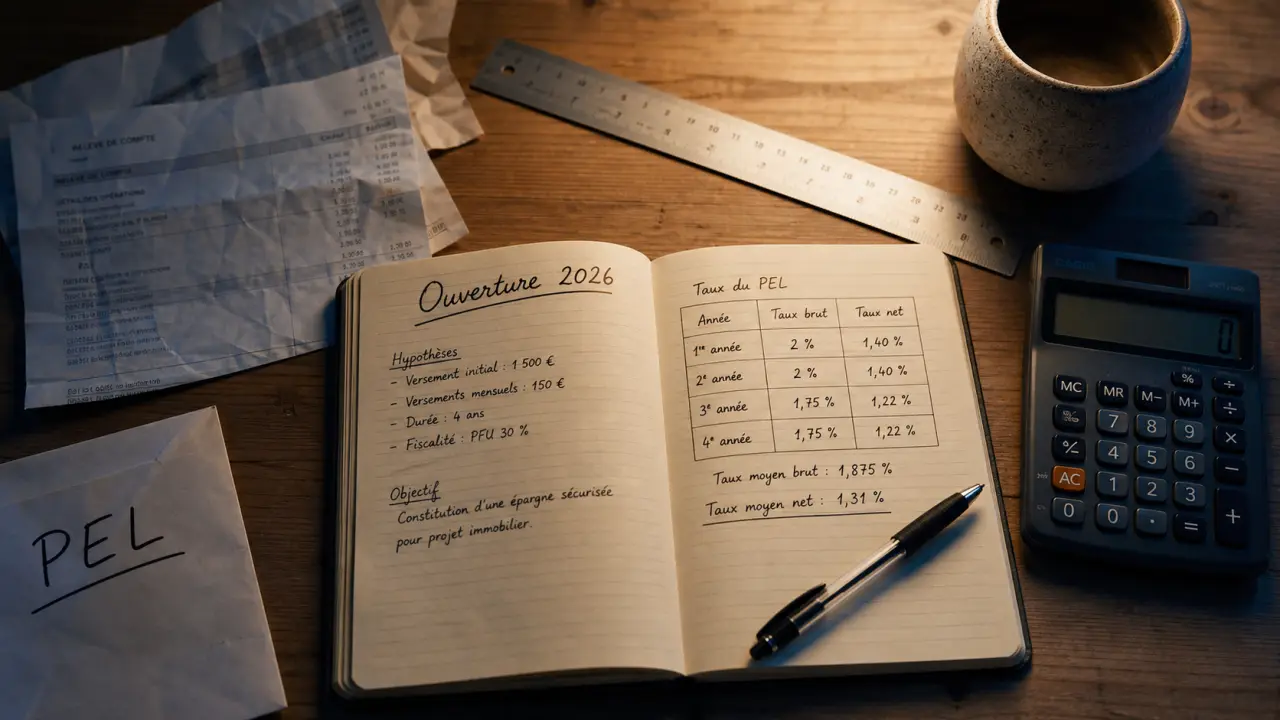

The rate of PEL at Caisse d'Epargne is not freely fixed by the bank. It depends on the regulations in force on the date of opening of the plan. For an LEP opened in 2026, the rate of pay indicated is 2 %. If you already have a plan, the right reflex is to check its opening date, as the rate remains guaranteed throughout the contract.
The ELP rate at the Caisse d'Epargne depends first on the date of opening
The Housing Savings Plan is a regulated savings product. At the Caisse d'Epargne, as in other institutions that distribute it, its rate of pay is known in advance at the time of opening. This rule has a simple consequence: two Caisse d'Epargne clients may have an ELP at different rates, because they did not open their plan in the same year.
Estimated capital of an ELP
Note: Indicative calculation before taxation. Minimum payment rules for the ELP (initial payment 225€monthly payments 45€ceiling 61 200€) remain the contract.
For a new ELP opened in 2026, the rate is 2 %. This rate applies to new plans opened over this period. It does not automatically replace the rate of an old ELP. If your plan has been opened on another date, it is the rate associated with this opening that continues to apply, subject to the terms of your contract.
A guaranteed but not universal rate
The most important notion is that guaranteed rate. Once the ELP is opened, the rate of pay is fixed for the duration of the plan. This saves money against a future drop in rates on the new ELPs, but it also means that an old, less favourable rate does not automatically go up when new openings show better pay.
This mechanism explains why the question "what is the rate of the Caisse d'Epargne ELP?" rarely calls for a single answer. To open a plan today, you have to look at the current rate for new openings. To follow an existing plan, it is necessary to find its opening date in the customer area, on the statements or with an advisor.
Recent history of ELP rates: the table to read before comparing
The table below provides a quick location of the applicable rate according to the ELP opening period. It is useful if you already have a plan at Caisse d'Epargne and want to understand why its remuneration differs from that displayed for new openings.
Everything about the Housing Savings Plan (LSP) · Discover the official rules, interest rates and operating conditions of the ELP to prepare your real estate project.
| Opening period of the ELP | Rates of pay | To be retained |
|---|---|---|
| 2026 | 2 % | Rates applicable to new LEPs opened over this period |
| 2025 | 1,75 % | Lower rate than openings 2026 |
| 2024 | 2,25 % | Rate above 2026 |
| 2023 | 2 % | Rate identical to the rate indicated for 2026 |
| 2016-2022 | 1 % | Lower pay period for open plans then |
This table shows one often misunderstood point: the ELP does not evolve as a booklet whose rate changes for all holders on the same date. The ELP rate is attached to the open contract. So it's the opening date, not the bank alone, which determines the applicable remuneration.
Why Comparison with Book A or SARA should be conservative
Comparing the ELP with Booklet A or Popular Savings Booklet may be useful, but it is necessary to compare products that do not have the same function. Booklet A shows a rate of 1,7 % in 2025, with a ceiling of 22 950 € for individuals. SARA has a rate of 2,7 % in 2025, but it is subject to eligibility conditions. The ELP, on the other hand, is distinguished by its rate fixed at the opening and its link with a possible Housing savings loan.
In other words, the ELP is not just a cash support. It is also used to structure a regular saving for a real estate project. If your priority is the immediate availability of money, a booklet may be more suitable. If your priority is to block a known remuneration and gradually feed a housing project, the ELP maintains a specific logic.
Payments, savings rate and ceiling: the practical rules to know
Opening an ELP to the Caisse d'Epargne requires compliance with payment rules. The minimum initial payment is 225 €. Next, the holder shall supply his plan at least at the height of 540 € per year. This obligation really matters: the ELP is not designed as an account to which you pay only when you think about it.
Possible payment rates
The minimum annual payment can be arranged at different rates. In practice, this corresponds to 45 € per month, 135 € by quarter or 270 € per semester. These amounts help to automate the saving effort and avoid oblivion. Exceptional payments may also be made within the ELP regulatory ceiling.
This regularity is part of the interest of the product. It imposes a discipline, but it also allows for a gradual construction of housing savings. For a young asset, a couple preparing a purchase or a home that wants to secure an envelope dedicated to housing, the scheduled payment can become a tool for budget control.
The regulatory ceiling and annual interest
The ELP is subject to a regulatory ceiling. Once this ceiling has been reached, it is no longer possible to add new amounts freely, even if interest continues to follow the rules laid down in the plan. Interest is paid annually, which allows us to monitor the evolution of savings over time.
Before you open or strongly feed an ELP, it is useful to check two elements: the share of your savings that you agree to spend on a housing project, and the rate of payment that you will be able to maintain over time. An attractive rate is not enough if the product does not match your horizon or your need for liquidity.
What the Caisse d'Epargne provides beyond the regulated rate
The Caisse d'Epargne does not decide the ELP rate alone, but it intervenes on the accompaniment, management and integration of the plan into a broader savings strategy. The interest for the customer is to be able to link the ELP to a concrete project: purchase of a main residence, work, preparation of a contribution or reflection on a future real estate loan.
A simple product to follow with an advisor or customer space
The ELP can be opened and monitored in a bank proximity logic. Depending on your situation, you can exchange with an advisor to verify the applicable rate, the rate of payment, the consequences of a closure or the consistency of the plan with your other savings products. Customer space usually allows to track payments, cumulative interest and contract characteristics.
The real decision point is often in the articulation between several envelopes. The ELP can play a pivotal role: on one side it does not have the flexibility of a booklet used for unforeseen expenses; On the other hand, it is not yet a real estate credit. It occupies this intermediate area where savings cease to be set aside only and begin to become a trajectory. Personal contribution, purchase schedule, future debt capacity, margin of security for work, all this comes into play when deciding how much to pay, without drying up its available savings.
Housing Savings Loan: An Advantage to Study, Not an Automation
The ELP may open rights to a housing savings loan, according to the conditions laid down in the product. This may be of interest to those who are preparing a real estate project, but it should not be considered automatically as the best financing option. The terms of the credit market, your borrower profile and the bank offers available at the time of the project must be compared.
With this in mind, the Caisse d'Epargne can support the overall analysis: savings already constituted, need for financing, target monthly payments, duration envisaged and articulation with other investments. The ELP's rate of pay is therefore only part of the subject; The value of the product also depends on how it fits into your project.
Should we open or keep an ELP at Caisse d'Epargne?
The decision depends first on your situation. For an opening in 2026, the rate of 2 % offers a remuneration known from the start and guaranteed for the duration of the plan. This can be suitable for a saver who seeks visibility and accepts savings supervised by regular payments.
For an already open ELP, the first step is to compare its contractual rate with the current rates of other supports available to you. An ELP opened in 2024 2,25 % does not have the same interest as an ELP opened between 2016 and 2022 1 %. However, the rate should not be the only criterion: seniority of the plan, real estate project, applicable taxation, liquidity requirement and loan rights must also be included in the arbitration.
To be considered if you want regular, secure and housing-oriented savings. To compare if you are looking for the best immediate return between regulated booklets and other investments. To be checked with an advisor before closing, because closing an ELP can cause the features attached to its opening date to lose.
In practice, the right reflex is simple: identify the opening date of your Caisse d'Epargne PEL, check its guaranteed rate, and then compare it to your real goal. If you are planning a real estate purchase or want to introduce a savings discipline, the ELP may remain relevant. If you are only looking for savings available at any time, it deserves to be balanced with other solutions.