
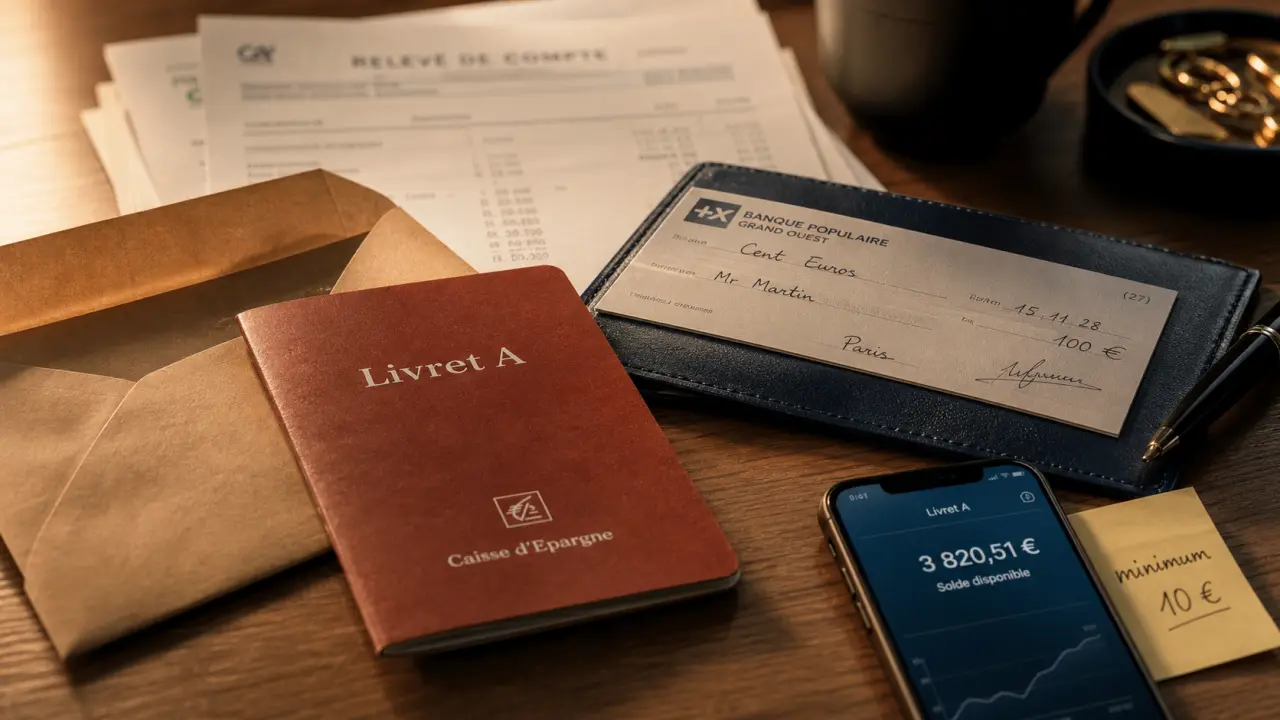

The minimum to leave on a Booklet A is 10 € in most banks. To Bankthe threshold is 1,5 €. If a withdrawal brings the balance under this floor, the booklet cannot be kept in this condition, and the situation in practice leads to its closure.
The rule is simple, but it counts when withdrawing money. Should we leave a small balance? Can we empty the account without closing it? What happens to the interests? The answers are clear, provided you look at the balance available and the threshold applied by your bank.
The threshold according to your bank
Book A is a regulated savings product. Its great rules do not depend freely on each establishment. For the minimum balance, the principle is net: 10 € must remain on Book A in most banks, with an exception to Bankwhere the minimum is 1,5 €.
Everything about the operation and rules of Book A · Consult the official documentation for the terms, limits and withdrawal rules applicable to your Book A.
| Establishment | Minimum to be stored | Consequences of a withdrawal below this threshold |
|---|---|---|
| Most banks | 10 € | The booklet cannot remain open with a lower balance |
| Bank | 1,5 € | The booklet must keep at least that amount |
This minimum is not a frozen sum in the strict sense
The funds of a Book A remain available. You can withdraw money when you need it, as long as the account stays above the allowed threshold. The grade is important: this minimum is neither a penalty nor a fee, it is the bar that allows the booklet to continue to exist. If you want to recover all the money placed on it, you have to ask the Closing of Book A.
The ceiling works in the other direction
The minimum is at the bottom of the balance, the ceiling is for payments. For a natural person, the ceiling of Book A is 22 950 €. Once this ceiling is reached, you can no longer feed the booklet with new payments. Interest may, however, continue to be added. Payments remain free No periodic filing is required to keep the booklet open.
Remove money without closing Book A
To avoid involuntary closure, just start from the balance actually available. If your Booklet A contains 1,000 € in a classic bank, you can withdraw up to 990 € while keeping the minimum of 10 €. At Bank Postale, with the same balance, the maximum withdrawal to keep the booklet open would be 998.5 €.
- Current balance: check the amount available before starting the operation.
- Threshold of your bank: hold 10 €, or 1.5 € at the Bank Postale.
- Maximum amount to be withdrawn: Current balance minus minimum to be retained.
A small calculation avoids a bad operation
The formula is simple: possible withdrawal = balance of Book A – minimum to leave. If the result is zero or negative, you cannot withdraw without closing the booklet. If it is positive, withdrawal is possible and the account remains open.
This minimum is used primarily as a practical benchmark. It keeps a savings envelope already open, ready to receive a new payment after a premium, a second sale or a refund. With 10 € When left on the booklet, you also keep a clear separation between precautionary savings and the current account, where daily expenses pass faster.
Withdrawals remain flexible, but not unlimited in effect
Book A is often used as a security reserve because money can be withdrawn at any time. This flexibility does not mean that we can go down to zero without formality. A total withdrawal changes the nature of the transaction: you no longer make only a cash flow, you stop saving support.
What happens if the balance goes below the minimum?
A Booklet A should not be kept under its minimum regulation. If a transaction drops the balance below the applicable threshold, the expected consequence is the mandatory closure of the booklet. In practice, banks therefore frame withdrawals to prevent an account from being in a non-compliant situation.
Total withdrawal: a fence, not a simple withdrawal
If you want to recover the entire balance, you must ask for the closure. The bank then pays the funds into the indicated account, taking into account the interest due. The procedure varies according to the institution: request online, in an agency, by mail or via an advisor. In all cases, the objective remains the same: to complete the booklet and terminate the contract.
Interest is calculated and capitalized
Booklet A produces interest at its rate of pay, shown here at 1,50 %. These interests are Capitalized annually, with a date of capitalisation at 31 December. In the event of closure, interest earned shall be taken into account in accordance with the rules applied by the bank. Another important point is that Book A interests benefit from a Tax exemptionThis makes it a simple medium to read for precautionary savings.
Minor, major, legal person: the cases to be distinguished
The minimum to be left on a Book A does not depend on the age of the holder. A minor and a major are subject to the same threshold in the bank concerned: 10 € in most establishments, 1.5 € at the Bank Postale. The difference is mainly in the way operations are managed and authorized.
For a minor, access to withdrawals can be supervised
A Book A may be opened on behalf of a minor, but withdrawals may require the intervention or agreement of the legal representative according to age, bank and account management rules. The minimum threshold remains the same, but the procedure can be more supervised than for an adult who manages his savings alone.
For a person under guardianship, management must be secured
Where the holder is under guardianship, the operations must respect the protection framework provided for the person concerned. It is therefore preferable to check the details with the establishment before a significant withdrawal or closure. The issue is not limited to the bank: it also concerns the protection of the owner's assets.
For some legal persons, access rules differ
Book A is not restricted to individuals. Some legal persons may have access to this, such as authorized structures or unions of co-owners. In this case, the practical management conditions, supporting documents and signing authorities may be specific. The minimum balance must be verified with the bank, especially if the booklet serves as a collective cash reserve.
Compare with other booklets before removing everything
Before closing a Book A to move money elsewhere, you have to look at the real goal: keep a savings available, choose another regulated booklet, or recover the funds for a specific expense. Book A combines three strong features: availability, regulatory ceiling for 22 950 € interest exempt from tax.
| Support | Use logic | Point to be checked |
|---|---|---|
| Book A | Available and regulated savings | Minimum 10 €, or 1.5 € at the Bank Postale |
| LDDS | Complementary regulated saving | Opening conditions and product-specific ceiling |
| Bank book account | Flexible savings offered by a bank | Rates, taxes and minimum rates fixed by the institution |
Closing a Book A may be relevant if you are no longer useful, if you are changing banking organisation or if you need to mobilize all your savings. However, if your goal is only to make a large one-off withdrawal, keeping the minimum can be more convenient. You keep an open booklet, ready to be recharged, without further opening.
The right decision is therefore a simple check: do you need to recover every euro, or only almost the entire balance? In the first case, ask for closure. In the second, leave the required minimum and keep your Book A active.