
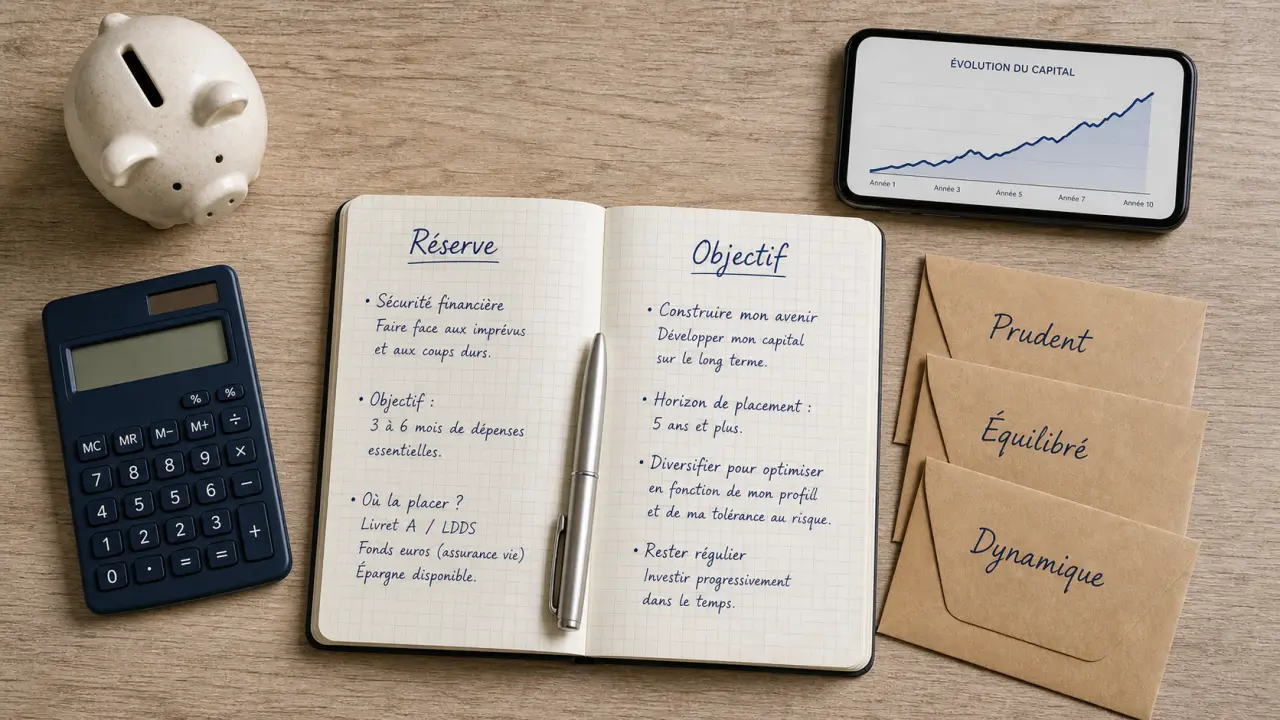

Investing 10,000 euros requires the method. The sum is high enough to build a real strategy, but it must not be committed at random. Before looking for the yield, it is necessary to decide how much to keep in reservation, what level of Risk accept and for how long let this capital work.
The right choice depends mainly on your goal. Protecting savings, preparing a real estate project, building capital on 15 or 20 years, or simply limiting the effect of inflation, this is not the same approach. An inflation target of 2 %, as mentioned by the ECB, recalls that money that sleeps too long is gradually losing its real value if its yield remains low.
Start by securing the base before looking for the yield
Do not invest the money you may need
The first rule is to separate precautionary savings from investment capital. If your 10,000 euros represent your entire reserve available, it is rarely wise to place them entirely on risky or loose media. An unexpected expense, a decline in revenue, or an urgent project may cause you to sell at the wrong time, so you may suffer an unnecessary loss.
Capital projection
One safety mattress shall remain accessible, preferably on a simple and liquid medium. The amount to keep depends on your situation: professional stability, fixed charges, family, current credit, level of comfort in the face of unforeseen circumstances. An employee with little expense does not have the same need as an independent person or a home with children. The idea is not to freeze a universal rule, but to preserve real room for manoeuvre.
Define a measurable objective
Investing "to earn more" remains too vague. A good objective specifies a horizon and a function: to finance a real estate contribution in three years, to prepare for retirement, to create a long-term supplementary income or to boost part of its savings. This precision avoids choosing an inappropriate placement. A short-term project does not support volatility; a project on 15 or 20 years can accept more fluctuations in exchange for higher yield potential.
We must also be wary of promises of rapid multiplication. Hope to turn 10,000 euros into a fortune 6 months requires extreme risk-taking, often incompatible with sound heritage management. Rather, performance is built with time, regularity and diversification. A clear strategy also helps to resist decisions made under the influence of fear or enthusiasm.
Choose according to your profile: careful, balanced or dynamic
Assess your loss tolerance
Your investor profile depends not only on your age or income. It also depends on your reaction to a temporary decline. Can you bear a loss of 5 %, 15 % or 30 % Without panicking or selling in an emergency? This issue counts as much as the expected level of return, as financial markets can fluctuate sharply even when the long-term strategy remains coherent.
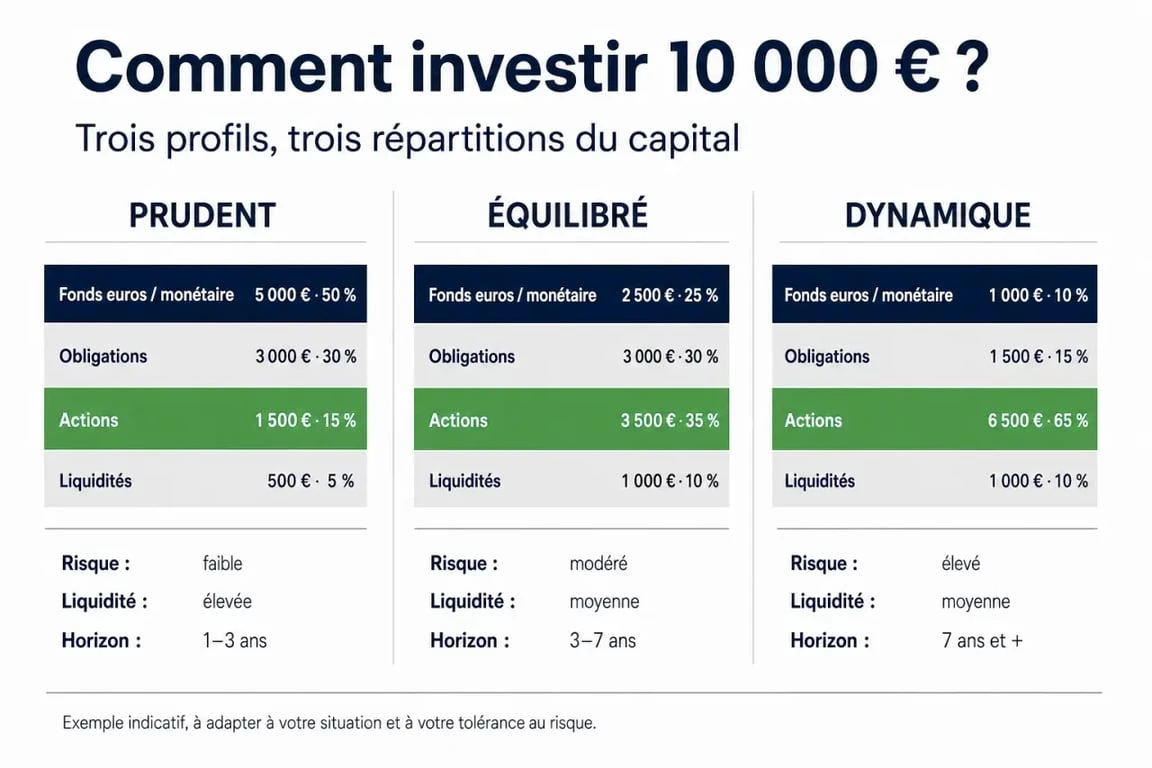
A prudent investor will favour stability and availability. A balanced profile will accept a measure of risk to improve potential performance. A dynamic profile can devote a greater proportion to equities, ETFs, private equity or crypto-actives, knowing that variations can be brutal. The most important thing is to align the distribution with your real ability to cash down, not with a theoretical ambition.
Sieve your placements before deciding
A useful method is to examine each placement with the same criteria, as if you passed a material to the sieve. What remains must be strong enough to enter your allowance. Always ask the same questions: is the placement liquid? Do you understand what generates performance? What scenario can make you lose money? What taxation applies? What costs reduce performance? This sorting avoids stacking attractive products in appearance, but difficult to manage together.
This audit also highlights the imbalances of a portfolio: too much indirect real estate, too many technological actions, too many blocked media or excessive exposure to a single risk. In practice, a good choice is not only a good product. It is a product that finds its place in a coherent whole.
Compare accessible media with 10,000 euros
With 10,000 euros, several investment families are accessible. The issue is not to choose one, but to understand each one's role in a global allocation. Some supports are used to secure part of the capital. Others focus on growth. Still others offer a more opportunistic exhibition. The table below gives a simple reading of the most common options.
| Placement | Possible role | Risk | Liquidity | Attention |
|---|---|---|---|---|
| Life insurance in euro funds | Securing part of the capital | Low to moderate | Generally good | Limited yield, fee to be monitored |
| Life insurance in units of account | Diversify with funds, ETF or real estate | Variable | Good to medium | Unsecured capital according to media |
| PEA | Investing in eligible European or ETF actions | Moderate to high | Average | Recommended long horizon |
| ETF | Exhibit portfolio with a diversified index | Variable | Often good | Market volatility |
| SCPI | Access real estate without buying property | Moderate | Limited | Costs, resale time, unsecured income |
| Crowdfunding real estate | Funding targeted real estate projects | High | Low | Risk of delay or capital loss |
| Private equity | Investing in unlisted companies | High | Low | Long block and demanding selection |
| Crypto-active | Very speculative diversification | Very high | Variable | Strong volatility, risk of significant loss |
Life insurance, PEA and ETF: the basic trio for many savers
Life insurance is often used to combine security and diversification. The euro fund can accommodate the defensive part, while units of account open access to more dynamic media. The PEA is interesting to invest in eligible shares or ETFs with a long-term logic. ETFs have the advantage of offering a diversified exposure with less complexity, provided they accept market variations. For many profiles, this trio forms a legible and easy-to-follow basis.
It is not the product alone that counts, but the architecture together. One secure pocket, a financial market-oriented pocket, and possibly a more limited real estate or alternative pocket make it possible to distribute capital logically. The choice of contract, costs and available media remains crucial, as two envelopes that appear to be close can produce very different results.
Indirect, unrated and crypto real estate: to handle with dosage
SCPIs can bring a real estate exhibition without directly managing housing, but they should not be confused with a booklet available at any time. Real estate crowdfunding and private equity can offer higher yield potential, but with loss risk and reduced liquidity. As for crypto-actives, they must remain a speculative pocket, reserved for money that you agree to see strongly fluctuate. Here, caution does not mean total absence of exposure, but a suitable pocket size.
These materials are especially meaningful in an already structured strategy. Used alone, they expose to hard-to-manage bumps. Used with measure, they can complete a more traditional allowance. So the right dosage depends less on the mode of the moment than on your horizon, your risk tolerance and your need for liquidity.
Examples of allocation to invest 10,000 euros without improvising
These distributions are not personalized recommendations, but frameworks for reflection. They show how to adapt the same sum to different profiles. The interest is to start from a simple logic, then adjust according to your goals, your financial security and your taste for risk. The same amount can therefore serve very different strategies.
Official AMF guides to better manage your savings · Discover the AMF's educational guides to understand your rights, placements and the right spare reflexes.
- Careful profile: 5 000 euros in secured savings or euro funds, 3 000 euros in diversified life insurance, 2 000 euros in large ETFs or moderate supports.
- Balanced Profile: €3,000 in secured pocket, €4,000 in ETF or diversified units of account, €2,000 in SCPI, €1,000 in more opportunistic placement.
- Dynamic Profile: 2 000 euros in reserve, 5 000 euros in ETF or shares via PEA, 1 500 euros in indirect real estate, 1 000 euros in private equity or crowdfunding, 500 euros maximum in cryptoactive.
Diversification does not involve random multiplication of lines. It aims to spread the risks between several drivers: liquidity, real estate, shares, secure media, possibly unlisted. Two apparently different investments can respond to the same economic factors; It is therefore necessary to monitor the correlation between assets and to rebalance periodically. Without this follow-up, a portfolio can drift without being accounted for.
Investing in multiple times can also reduce the risk of entering markets at the wrong time. Instead of investing 10,000 euros in volatile assets, you can spread the payments over a few months. This disciplined approach to decision-making, limits the emotional impact of fluctuations and makes it easier to adjust the distribution if your situation changes during the investment period.
Errors to avoid before taking action
High yield and good investment
An attractive yield is never free. It often pays a risk: capital loss, blockage, volatility, lack of a project, high fees or lack of transparency. Before subscribing, always check the operation of the product, the adverse scenarios, the entry, management and exit costs, and the applicable taxation. A good yield figure is not enough if the rest is unclear.
Follow a fashion instead of a strategy
Trendy actions, crypto-actives, real estate presented as "risk-free", advice from financial influencers: investment attracts simplifying discourses. A strong strategy is part of your situation, not the product of the moment. If you do not understand what you are buying, it is best to defer the decision or ask for a qualified opinion. The apparent simplicity of a product can mask real complexity under conditions, costs or output.
Forget post-investment monitoring
Placing 10,000 euros is not a unique gesture. Your allowance must evolve with your income, your projects, your age, your taxation and the economic context. An annual point is often enough to check whether the distribution remains consistent, arbitrate certain lines, reinforce an underrepresented pocket or reduce a risk that has become too high. Without follow-up, even a good starting decision can lose relevance.
The best way to invest 10,000 euros is therefore to move forward with a method: securing a reserve, defining a horizon, choosing understandable supports, diversifying without dispersing and accepting that time is a major ally. If your heritage situation is complex or if you hesitate between several options, a financial advisor can help you turn this amount into a truly appropriate allocation.