

Comparing bank charges is not just about looking at the price of a card. Depending on your age, your payments, any overdrafts or your need for agency, the annual gap can quickly become significant. Panorabanks evoke up to 296€ average annual savings, while MoneyVox quotes 246€ annual saving possible in its comparisons. The stake is simple: to identify the Useful costs for your profile, then choose a bank whose rate schedule corresponds to your usage.
Bank charges to be compared as a priority
Bank charges consist of amounts invoiced by a bank for account management, means of payment, certain services and incidents. They vary greatly between traditional bank1 online banking and one neobank, but also according to the chosen options and frequency of use.
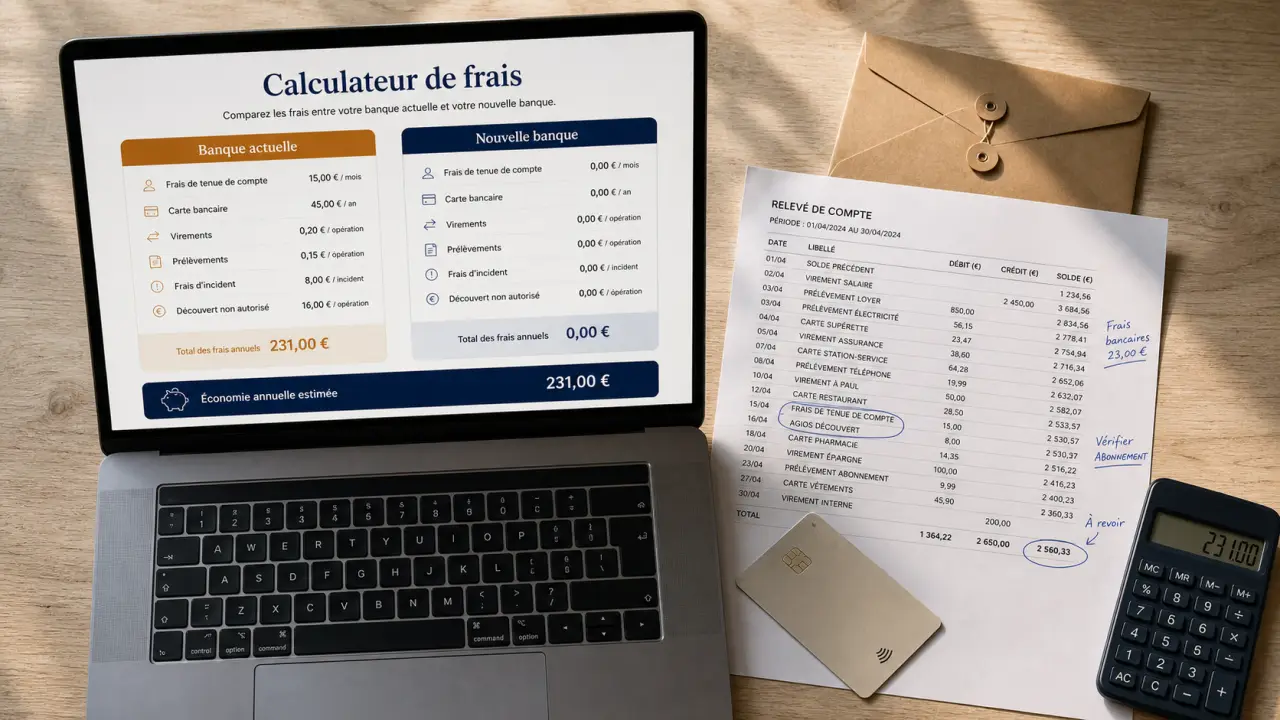
Bank charge calculator
Current Bank
New Bank
Daily expenses
The first fees to review are those you pay even when everything goes well: account keeping fees, credit card fees, offline withdrawals, specific transfers, SMS alerts or service packages. Lesfurets.com indicates for example 20€ average account keeping costs, a post that is often discreet but recurring.
Credit cards deserve special attention. A systematic card, a classic card, a premium card or a high-end card do not meet the same needs. A free offer may be interesting if you meet its terms of use, but it may become more expensive if penalties apply in case of inactivity.
Incident costs
Intervention fees, rejection fees, agios, information letters and overtaking costs may weigh heavily on clients exposed to overdraft. A profile that is never uncovered will not have the same ranking as a profile that experiences several incidents per year. This is one reason why a single ranking of the cheapest banks remains insufficient.
Less visible services
Foreign transactions, instant transfers, bank cheques, insurance related to means of payment or inheritance charges are less frequent, but may create significant differences. The European regulation on instant transfers is gradually changing pricing, with a free fee scheduled for January 2025: this is a point to watch if you often use this service.
Compare according to his profile: young, classic, premium
A good one comparative bank charges must start from your actual use. The same rates can be excellent for a student, medium for an employee with premium card, and unfavourable for a person who is often short. The idea is not to look for the cheapest bank on one line, but the one that corresponds to your year-round usage.
Easily compare official bank rates · Use this government tool to compare banking fees and services according to your department and your needs.
| Profile | Fresh to watch first | Often competitive banks | Point of vigilance |
|---|---|---|---|
| Young | Card, account keeping, withdrawals | Online banks, neobanks | Conditions of age or use |
| Classic | Card, account keeping, occasional incidents | Online banks and sober offers | Actual cost of package |
| Premium | Premium card, insurance, foreign | Premium online banks, some traditional offers | Effective guarantees |
Young profile: free is available, but under conditions
MoneyVox indicates 0€ annual fees for Fortuneo and BoursoBank on a young profile. This type of offer can be very advantageous for a student or young asset who mainly uses card payments, mobile app and transfers. On the other hand, foreign charges, withdrawals outside the euro area and any conditions of income or use must be checked.
Classic profile: the cost is played on accumulation
For a conventional customer, differences rarely come from a single tariff line. They are formed by addition: account keeping, card, withdrawals, insurance, one-off incidents. Lesfurets.com mentions 215.50€ This shows the interest of regular monitoring, even when monthly fees seem low.
In a bank budget, each fee counts. A 3 card€ Two withdrawals per month, a paid SMS alert and an occasional intervention commission may be sufficient to raise the annual bill. In order to compare correctly, it is necessary to reconstruct the complete mechanics of your banking year, not only look at the most visible line.
Premium profile: do not pay twice the same guarantees
A premium profile should compare the card contribution, but also travel insurance, payment limits, withdrawals abroad and assistance services. If you already have guarantees via home insurance, a business card or a mutual fund, some banking options can duplicate. The right choice is not always the cheapest bank, but the one that only charges the services you really use.
Where to find reliable data for its comparison?
Bank rates change regularly. To avoid bad surprises, public tariff pads, transparent comparators and up-to-date data are needed. It's the only way to keep a Bank comparison relevant at the time of the decision.
Public comparison of bank rates
The website economy.gouv.fr highlights a comparison that compares up to 15 banking services. It has 150 credit institutions and covers 98% of the market. Its interest is to offer a broad base, structured by department and by type of institution, useful to confront a national bank, regional bank or online bank.
Independent comparators
Actors like MoneyVox, Panorabanks or UFC-Que Choosing can complete the analysis with rankings, standard profiles and savings estimates. MoneyVox cites for example 2.78€ annual fees for the cheapest online banks, 91.26€ for Hello bank and 130,70€ for Crédit Coopératif in his statements. These figures must be read with their methodology: profile studied, services included, date of tariff and usage assumptions.
Tariff plate remains essential
Before you open an account, always check the bank's rate tag. It specifies the account keeping fees, cards, incidents, international transactions, transfers, cheques and ancillary services. A comparator helps to preselection, but the badge allows you to check specific cases: joint account, proxy, currency withdrawal, opposition, duplicate or estate-related costs.
Calculate your savings before changing banks
To estimate your savings, take your last 12 months' statements and add up the actual fees. Then compare this amount with the annual cost of a competing bid by reproducing the same uses. This method gives a more reliable view than just a call rate.
| Cost item | Your current bank | New bank envisaged | Annual difference |
|---|---|---|---|
| Accountancy | To be completed | To be completed | To be calculated |
| Carte bancaire | To be completed | To be completed | To be calculated |
| Withdrawals and payments | To be completed | To be completed | To be calculated |
| Incidents and discovered | To be completed | To be completed | To be calculated |
| Related services | To be completed | To be completed | To be calculated |
This method avoids the classic error: choosing a cheaper bank on paper, but not suitable for your habits. If you travel often, foreign exchange charges can count more than accounting. If you are rarely exposed, a bank that is highly competitive on incidents will not necessarily be a priority.
Reducing costs without necessarily changing banks
Changing banks can be profitable, but it's not the only leverage. Some of the fees can be reduced by adjusting your current offer and removing options that do not serve.
- Remove unnecessary options : average payment insurance, pay alerts, too wide package or oversized card.
- Switch to a more suitable card : A classic card is enough if you do not use premium guarantees.
- Limiting incidents Free balance alerts, overdraft authorization adjusted, automatic transfer to the current account.
- Negotiate certain costs An advisor can sometimes reimburse a one-time incident or offer a simpler offer.
- Testing a bank online It can be used as a primary or secondary account before a complete changeover.
If you decide to leave, the bank mobility support service facilitates the transfer of recurring levies and transfers. Before closing the old account, keep a margin for undebited cheques, forgotten subscriptions and expected refunds. The best comparison is not only the one that displays the lowest price: it is the one that allows you to pay less without losing in comfort, safety or useful services.