

Notary fees for a real estate acquisition fall to only 2% or 3% of the selling price when the new one is chosen. But how can you ensure that your bank record will keep pace with a construction site that has not yet come out of the ground?
VEFA funding imposes a progressive payment schedule that can quickly weaken your budget if the interlayer interests are not anticipated. An update on the credit mechanisms and the aid available for secure your purchase on plan.
Operation of the VEFA and specific features of the plan purchase
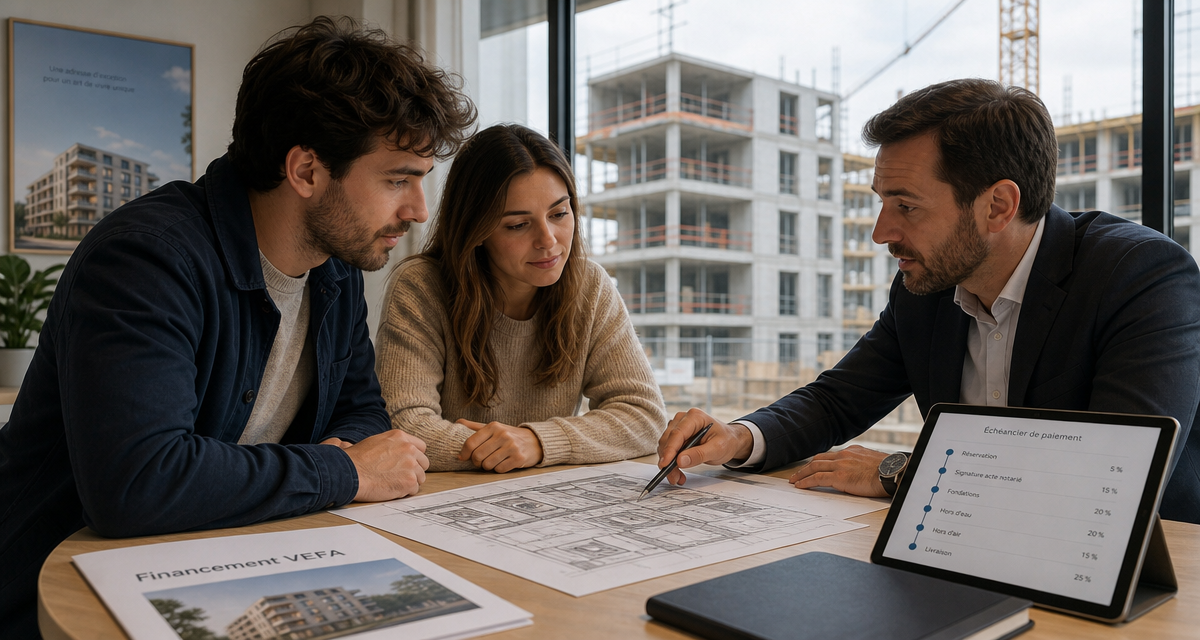
The VEFA allowsbuy a new property with reduced notary fees 2-3 per cent and 10-year guarantees. The payment is made by means of successive calls for funds, from 15 % at the opening of the yard to the final 5 %, marking a net break with the old real estate.
VEFA financing: what you need to know before you buy is that everything is based on plans. The transition between catalog selection and key delivery often over 18 to 24 months.
Major differences between the nine and the old
The old offers an immediate enjoyment unlike the 18 or 24 months of the new. You buy on plan without prior physical visit. It's a jump into the future.
The new guarantees compliance with RE2020 standards. These thermal performances drastically reduce your heating bills. Your comfort gains over the long term.
Role of the reservation contract and security deposit
The security deposit up to 5 % maximum if the act occurs within one year. This contract must detail the area and equipment intended to secure the buyer.
You have a 10-day withdrawal period. During this period, recover your funds without penalty by registered letter. This is an essential legal protection.
Verification of the real estate developer's solidity
Analyze the manufacturer's past financial statements and achievements. Don't neglect anything.
Consult customer reviews for potential litigation. Visiting completed sites remains the best method for judge the quality of the finishes. Be curious and demanding.
Real estate credit mechanism for a project in VEFA
After having secured the choice of the proponent, consideration must be given to funding, as the release of funds follows a very precise rhythm.
After having secured the choice of the proponent, we must look at how to financing housing in VEFA, because the release of funds follows a very precise pace.
Legal time frame for calls for funds in stages
The law lays down strict bearings. You pay 35% to the foundations, then 70% to the water out. The architect certifies each step to validate the actual advancement.
Your bank releases money only on presentation of these proofs. The payment is therefore strictly progressive and secure For you.
Management of intermediate interests during the construction site
These costs are the interest calculated on amounts already paid to the proponent. They logically increase at each new step.
Here are the key points of the VEFA funding What you need to know before you buy:
- Immediate payment of interest
- Use of personal input as a priority delay first release
- Impact on overall monthly payments
Partial or total refund
The partial deductible limits the costs to interest. The total franchise postpones everything, but its Final additional cost is much higher.
Make your choice according to your ability to accumulate rent and credit. The strategy must remain careful for your budget.
What help to finance your new home?
In addition to the traditional loan, several public schemes allowconsiderably reduce the total bill your real estate acquisition.
Zero rate loan and reduced VAT in ANRU zone
The PTZ 2026 depends on your resources and your area. This free loan finances your first purchase. In ANRU, VAT falls to 5.5%.
These aids are for your principal residence. They optimize your VEFA funding file : what you need to know before you buy.
Exemption from property tax and notary fees
The new reduces notary fees 2 % or 3 %. Land tax exemption is possible for the first two years.
| Costs | Former | Nine | Gain |
|---|---|---|---|
| Rights transferred | 5,8 % | 0,715 % | High |
| Property tax | Full | Exemption | 2 years |
| Folder | Variables | Variables | – |
| Total | 7-8 % | 2-3 % | ~5 % |
Impact of Changing Work on the Loan
Changing bulkheads or sockets Cost. These TMAs are often billed separately by the developer, out of your real estate loan.
These changes may delay delivery.
4 guarantees to secure your real estate investment
Buying a home that does not yet exist may seem risky, yet the French legal framework offers extremely strong protections.
Financial guarantee for completion and 10-year protection
The GFA guarantees the completion of the project despite a possible bankruptcy of the promoter. The 10-year warranty covers damage to the building's strength. These devices secure your capital over ten years.
The biennial guarantee protects dissociable equipment such as radiators. These protections automatically activate Upon receipt of the work.
Anticipate delivery delays and compliance
The creation of a rescue savings helps to overcome possible construction delays. Carefully compare the plans with the final realization. Vigilance avoids bad surprises when handing over keys.
The reservation agreement is your legal reference for require repairs. Remedies exist if promised benefits are not honoured.
Reserve management and blocking of the remaining 5%
You can record the balance of 5% if wrongs appear during delivery. Complete the minutes conscientiously with the sponsor. This document formalizes the actual state your new home.
You have an additional month to report any defects hidden by registered mail. This deadline secures the transfer of ownership.
Mastering the timing of fund calls, securing your support like PTZ and checking the sponsor's guarantees are the pillars of a safe purchase. Prepare your VEFA funding package for Realize your new real estate project With confidence. Your future housing with the latest energy standards is waiting more than you.