

Choosing car insurance is an engaging and sometimes technical decision. The market is changing rapidly, offers are increasing and price and guarantee differences are large. For a driver who cares about his budget and his peace of mind, understanding the reasons for comparing car insurance avoids both bad surprises, unnecessary costs and inappropriate contracts. This guide details not only the concrete benefits of the comparison, but also the criteria to be analysed, the specificities by driver profile, the developments in the sector and the pitfalls to be monitored.
The main reasons for comparing car insurance
Comparing your car insurance is primarily used to compete with guarantees, franchises and options that directly influence your daily life. Differences may exceed 600 € depending on profile, vehicle type and level of coverage. If you rely on a single simulation, you often have to pay too much, or get poorly covered in the event of a disaster. Owners of electric vehicles, for example, have to check for the handling of batteries or specific equipment, without unforeseen costs.
The market is full of low-priced offers that hide high franchises or little visible exclusions. Examining the details of the guarantees, adapting the choices to your actual use and comparing the services offered – troubleshooting, legal aid, digital management – are all levers of optimization. Young drivers, who are penalized by high premiums, gain a comparison, as some telematics (following driving behaviour) offer savings of up to 30%, as at Allianz and Ornikar.
Beyond the rate, comparing offers gives a clear view of customer service, the speed of compensation and the simplicity of the procedures, factors sometimes more decisive than the amount of the contribution.
What criteria should be analysed when comparing car insurance?
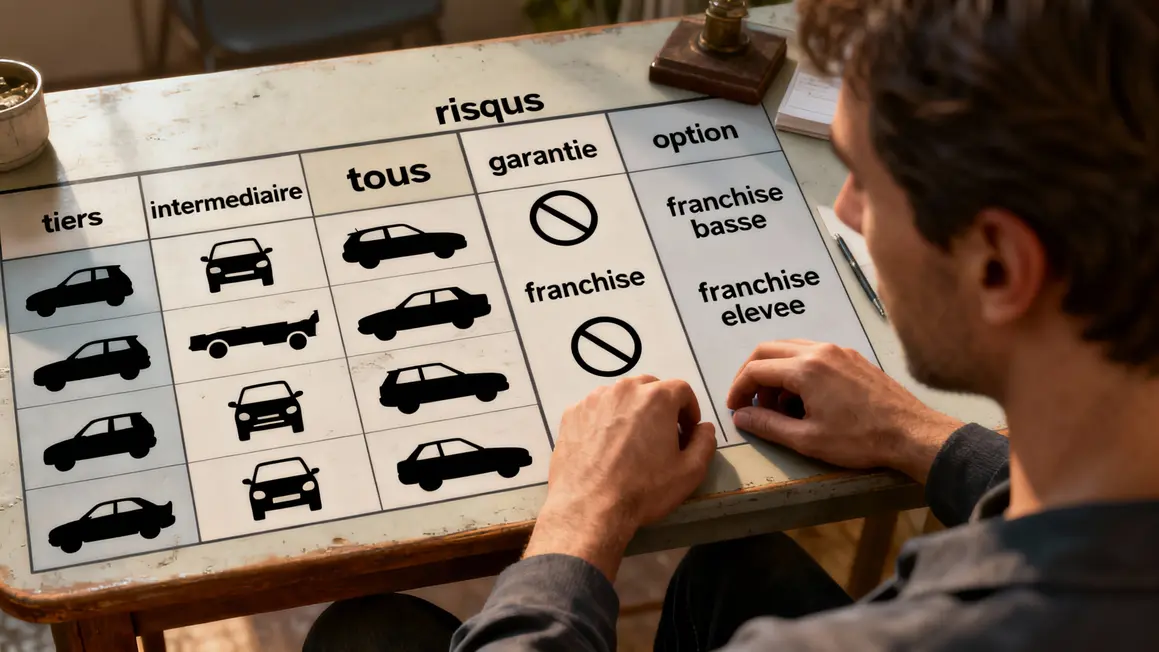
Benchmarking should be based on specific criteria:
- Type of coverage Third party (civil liability alone), intermediate (theft, fire), all risks (damage to your vehicle). Adjust according to the value and use of the vehicle.
- Amount of allowances : the higher the franchise, the lower the premium, but the rest of it goes up in case of a disaster.
- Compensation ceilings It is prudent to check the limit for physical or material damage.
- Optional guarantees : natural disasters, new value, battery insurance, zero-kilometre assistance... To customize according to your profile and geographical area.
- Related services : quality and accessibility of assistance, digitalisation of procedures or presence of a telephone customer service.
A few concrete examples: a young driver will often pay more, but can limit the bill with insurance to a low-free third party. A hybrid or electric car owner will have to look at the technical guarantees. It is essential to adjust each parameter to its actual use to avoid extra costs.
Focus on insured profiles and their varying needs
Contracts vary according to the driver's profile and vehicle type.
Young drivers
Rates are generally higher, with offers such as Ornikar or L-Olivier that rely on accompanied driving and telematics to reduce costs. The integration of educational options and digital monitoring is a relevant choice to consider.
Experienced drivers
More accessible premiums, loyalty bonuses, marketable franchises and premium guarantees, including legal protection, are offered to insurers such as Allianz.
Electric or hybrid vehicles
AXA or MAIF offer specific guarantees: battery support, dedicated support, charging station protection. The price may be higher than a conventional formula, but protects the investment made on the vehicle.
Casual drivers
Choose a third-party or adapted kilometer insurance. For example, Direct Assurance offers rates adjusted for real use.
Mixed profiles
Combining several features (experience, usage, technical vehicle) requires comparing bonuses, franchises and custom options to avoid paying too much without compromising coverage.
The impact of new technologies on car insurance
Telematics, applications and digital platforms now allow for the customization of premiums according to driving and facilitate contract management. Insurers, like Ornikar, L-Olivier or AXA, offer trackers to adjust rates and offer immediate discounts to responsible drivers. Electric vehicles also benefit from technical guarantees through the collection of on-board data. These innovations speed up compensation and improve user experience, but keep in mind that accepting personal data may be a constraint for certain profiles.
Compare auto insurance prices in inflation context
The continued rise in rates due to inflation (parts, claims, labour) leads to the challenge of his car insurance formula on a regular basis. Identify your needs: all risks to an old vehicle are rarely justified. Negotiate at renewal: Many insurers accept a discount to keep their customers. And watch the franchises, often increased in exchange for a lower posted premium.
Tip: Use an online comparator to update your choice in real time and detect offers tailored to your portfolio.
Centralized auto and home management can also reduce the bill through negotiated packages.
Tools for comparing auto insurance effectively
- Online Comparers : quick access to personalized quotes according to your criteria.
- Insurers sites More detailed specifications, integrated services, direct contact.
- Independent traders : personalized selection, accompaniment in negotiation.
However, the speed of a comparator must be complemented by a careful reading of the clauses and a verification of the visibility of the customer service, particularly for attractive rates on the web.
Traps to avoid when comparing and subscribing
Too quickly or superficially exposed to these risks:
Opt for a all-car insurance: guarantees, exclusions and criteria to know can offer you maximum coverage, provided you compare the available offers.
Comparing auto insurance better anticipates your expenses, especially when you ask yourself how many kilometers travel with 20 euros of petrol in 2025.
Comparing auto insurance not only saves money, but also optimizes its transport budget by knowing, for example, that How many kilometres can you travel?.
| Trap | Impact | Advice to avoid |
|---|---|---|
| Not reading clauses | Discovery of disaster restrictions | Read each warranty and exclusion carefully |
| Unknown guarantee exclusions | Lack of coverage for certain vehicles or situations | Report sensitive protections to a comparative table |
| Franchises too high | Unforeseen expenditure on claims | Compare franchises before validating a contract |
| Price focus only | Poor coverage of after-sales service and responsiveness | Analyze opinions on the compensation deadline and support quality |
Add to your checklist: detailed reading of exclusions, comparison of service levels, customer contact test before signing up.
The financial benefits of comparing your car insurance
A systematic approach often generates 150-438 € annual savings according to your profile and vehicle. The study of hidden posts (franchise, temporary promotions, unused options) makes it possible to tailor the invoice as accurately as possible. For a new city, up to 200 € can be saved with Ornikar or a hybrid SUV up to 300 € Groupama's. Optimal contract management can also free up funds for other family or leisure uses.
| Driver profile | Vehicle type | Potential savings | Recommended insurer |
|---|---|---|---|
| Young driver | New Citadine | Up to 200 € / year | Ornikar |
| Senior owner | Hybrid SUV | Up to 300 € / year | Groupama |
| Periurban driver | Former utility | Up to 150 € / year | Insurance |
Rank 2026: the best car insurance by category
The sector has been structured around recognized leaders: Allianz and Direct Assurance on global quality, Ornikar and L-Olivier for young drivers, AXA and Groupama for electric vehicles. The strengths differ: pricing, speed of compensation, accessibility of assistance and personalization of guarantees.
| Category | Top Insurers | Highlights | Low points |
|---|---|---|---|
| Overall quality | Allianz, Direct Insurance | Reactivity, extended coverage | High rates for Allianz, limited flexibility at Direct Assurance |
| Young drivers | Ornikar, L-Olivier | Adjusted rates, teaching support | High franchise, limited guarantees |
| Electric vehicles | AXA, Groupama | Dedicated options, effective support | Price above a classic formula |
Users point out the relevance of the MAIF to mutualised solutions or a recognized customer service, but complex management times may vary. Adapting the choice to your profile remains essential not to lose control over the overall cost and quality of access to services.
How to prepare your subscription after comparing
Before finalizing, gather all the necessary documents: permit, grey card, information record. Search bonus-malus and simulators, check the guarantees for your specific journeys or needs. Read the entire contract, including assistance or franchise clauses.
- Always ask for an easy-to-access copy and test customer service from the start.
- For digital services, become familiar with the tools offered for fluid and autonomous management.
- Note the payment deadlines, the impact of the bonus/malus after each claim and the renewal dates.
The above steps facilitate the management of your contract and reduce unforeseen events.
Comparing auto insurance helps optimize both your coverage and your budget. Have you ever found any price differences or unexpected options in your own comparisons? Share your experiences or ask your questions as a comment to benefit from the feedback from the 01bank.com community. If this article has helped you clarify your choices, don't hesitate to spread it to your friends each exchange expands the opportunities to better choose its financial services. What other aspects of auto insurance do you want to deepen? Propose your ideas for future files.
Author: Fabien Durand, specialist in insurance and financial optimization. Article updated June 2026.