

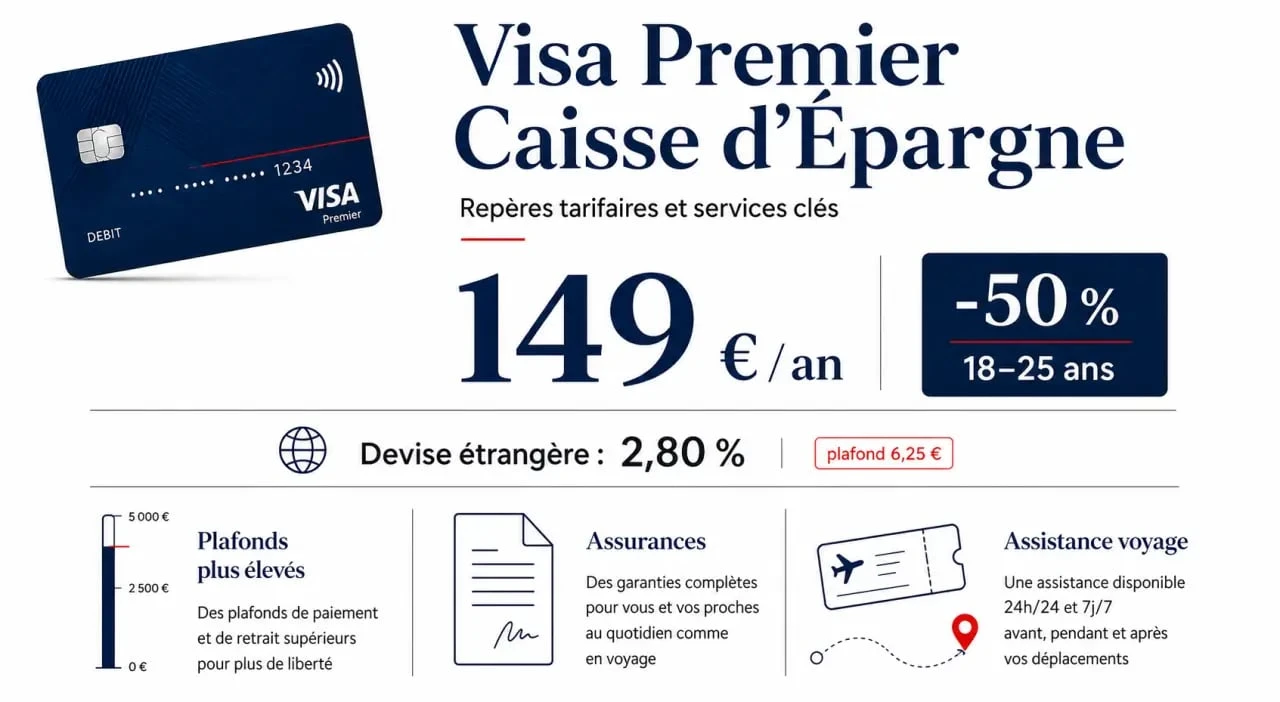
The Gold Caisse d'Epargne card price, marketed under the name Visa First Card, is of 149.00 € per year. This card gives access to more comfortable ceilings, insurance and assistance guarantees, and useful travel services. Before you subscribe, the real question is therefore simple: do these advantages justify the annual cost according to your use?
The Gold Caisse Savings Card Price and Possible Discounts
The Caisse d'Epargne Visa Premier card is located above a Visa Classic card. Its annual 149,00 € corresponds to a high-end bank card designed for customers who want more comfort on a daily basis, more security on the move and more flexible ceilings.
Estimated annual cost: Visa Premier
Formulas used:
• Annual tariff : 149,00 € (or 74.50) € 18-25 years).
• Costs per operation: min(amount × 2.80 %; 6.25 €).
• Total = Annual rate + (Number of transactions × Costs per transaction).
Note: Non-euro area withdrawal costs are not included in this calculation because their exact scale is not specified.
| Item to be checked | What to remember |
|---|---|
| Annual tariff | 149.00 € for the Visa First Savings Fund card |
| Youth reduction | 50% discount for 18-25 year olds |
| Trade name | Visa Premier card, often called Gold card |
| Card type | International payment card |
The reduction of 50% for 18-25 year olds changes the deal strongly for an active young person, a student travelling or a mobile person. At this age, interest is not only in the name of the card. Travel guarantees, payment abroad and more comfortable ceilings can already be used for first trips outside France.
To evaluate the rate, one must think according to usage. A map at 149,00 € seems expensive if it is used only to pay for some daily purchases. It becomes more coherent if it covers several costly situations, such as a delayed flight, lost baggage, medical assistance abroad or a rental vehicle. The correct calculation is based on your travel frequency, expenses and warranty requirements.
What Visa Premier really brings to everyday life
Higher ceilings to avoid blockages
The Gold Caisse savings card includes High payment and withdrawal ceilings. The exact amounts depend on the customer profile and the terms and conditions with the bank, but the idea remains the same: offer more margin than a standard card. It is useful to pay for a plane ticket, a hotel deposit, an unforeseen expense or several close purchases without immediately requesting a temporary increase.
This is especially important if you use your card for group expenses: family vacations, travel bookings, computer equipment or advanced professional fees. A card with too low ceilings can block a transaction at the wrong time, even when the account has the necessary funds.
Insurance and assistance included
Visa Premier card is also wanted for its Insurance and assistance guarantees. They may occur in several cases: cancellation or modification of travel, repatriation in the event of sickness or accident, reimbursement of medical expenses abroad, loss, theft or deterioration of luggage, as well as certain incidents related to a rental vehicle.
These guarantees should not be seen as merely a commercial argument. They may avoid taking out certain separate insurances, provided that the ceilings, exclusions and activation conditions are clearly read. In several cases, total or partial payment of the benefit with the card may be necessary to trigger coverage.
Useful emergency services
The Caisse d'Epargne also highlights practical services such as Opposition in the event of loss or theft, and Cash troubleshooting service within 48 hours. This type of service makes sense abroad, when a lost card can quickly complicate a stay.
Service AirRefund may also assist in claiming compensation for delayed theft. This is not a service used daily, but it can make a real difference in the event of a transport incident, especially when the approach to an airline is long or unclear.
In practice, it is often the whole that counts: the card is used to pay, to have room for manoeuvre, and then to manage unforeseen events without multiplying separate contracts. This is where the annual contribution is made, or not, according to your profile.
Foreign expenses: the item to consider before travelling
The Gold Cash Savings Card is an international card, but this does not mean that all transactions outside the euro area are free. For payments in foreign currency, a 2.80 % commission may apply, with maximum charge of 6.25 € on a payment transaction.
Official rate schedule for banking operations and services · See the Caisse d'Epargne's official rates and banking services, as well as the associated tariff information document.
| Situation | Costs to be anticipated | Practical advice |
|---|---|---|
| Payment in euro | Generally the simplest case | Focusing on local currency payments in the euro area |
| Payment in foreign currency | Commission of 2.80 %, maximum charge of 6.25 € by operation | Consolidating some important purchases may limit the multiplication of costs |
| Withdrawal from the euro area | Costs to be checked in the tariff brochure | Avoid repeated small withdrawals |
For a one-time traveller, these fees may remain acceptable if currency transactions remain scarce. For a person who often travels outside the euro area, they must enter the global calculation. A card with good insurance but high user fees can become less interesting if you pay very regularly in foreign currency.
Before departure, it is best to check three points: payment costs, withdrawal costs and limits available during the travel period. A simple call to the advisor or a consultation of the tariff brochure helps avoid a bad surprise on the spot.
It should also be borne in mind that the costs do not read in isolation. A one-time payment in foreign currency does not have the same impact as a series of purchases over several days. It is this repetition that really weighs on the budget.
Immediate or deferred debit: choose according to how you manage your budget
The Visa First Savings Card can work in immediate flow or deferred flow rate. The choice is not only technical: it changes the way you track your expenses.
Immediate debit to track your account as closely as possible
With the immediate debit, payments are made quickly from the account. This option is suitable for people who want a simple reading of their pay and who prefer to avoid the accumulation of expenses at the end of the month. It reassures if you manage your budget on a day-to-day basis or if you want to keep a clear vision of your money out.
Deferred debit to smooth out expenses
With deferred debit, card payments are consolidated and collected later, often on a fixed date. This option may be suitable for executives, independents or professional travellers who advance pre-reimbursement fees. On the other hand, it requires more discipline, as the displayed balance of the account does not immediately reflect all expenses incurred.
Before choosing, ask your agency for specific terms and conditions: collection date, access conditions, possible tariff differences and options for modification. The right choice is one that corresponds to your income rate and your tolerance for the lag between purchase and actual debit.
The flow mode also influences your mental comfort. Some people prefer to see everything go along the water. Others choose the delay to better organize their monthly expenses. In both cases, it is important to know how the account will actually be enlivened.
Compare with other Visa cards before signing up
Gold is not always the best choice in principle. It becomes relevant when its services correspond to real use. Comparison with a Visa Classic or Visa Platinum allows you to locate the right level of card.
| Map | Profile generally adapted | Main strong point |
|---|---|---|
| Visa Classic | Simple daily use | Standard international map, often sufficient for current expenditure |
| Visa First | Casual traveler, family, customer with higher expenses | High ceilings, insurance and enhanced assistance |
| Platinum Visa | Client looking for more services and comfort | Level of benefits above Visa Premier |
If you travel little, never rent a car and don't need high ceilings, a cheaper card may be enough. Conversely, if you leave several times a year, book online stays, carry valuable luggage or travel with loved ones, Visa Premier can offer significant security.
To subscribe, the simplest thing is to contact a Caisse savings advisor or consult the customer area if the offer is offered. Prepare some useful information: age of holder, desired type of debit, income level, planned use in France and abroad, need for specific ceilings. This preparation provides a more precise answer on eligibility, applicable tariff and associated options.
When comparing, look especially at what the card prevents you from buying separately. If you already have travel insurance, low non-euro area costs and modest ceiling requirements, the price differential may weigh more. If you often use the moving card, balance changes quickly.
In summary, the Gold Caisse d'Epargne card rate must be assessed with its specific counterparts: 149.00 € per year, a significant reduction for 18-25 year olds, useful travel guarantees, more comfortable ceilings and foreign exchange monitoring fees. It's a relevant card if you're actually using its services, less obvious if you're only looking for a classic payment method.