

A payment refused in cash, a card passed to the distributor or a message « invalid card » online can quickly block an expense. The good news is that an invalid credit card does not always mean that it is unusable. In most cases, it is temporary blocking, ceiling reached, a disabled option or a security check to be lifted from the bank.
Quickly identify the type of problem
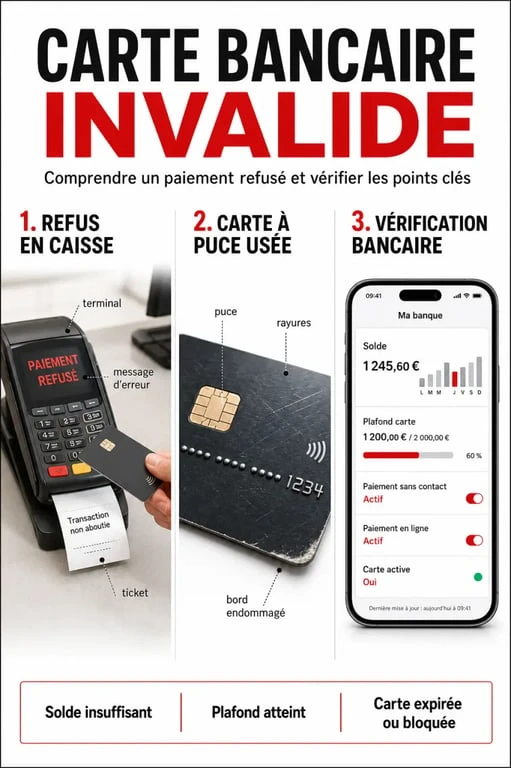
Before requesting a replacement, three often confused situations must be distinguished: refusal of payment, blocking of the card and the disability linked to the card itself. The message displayed by the payment terminal, the merchant site or the distributor often gives a first clue.
| Observed symptom | Probable cause | First reflex |
|---|---|---|
| Payment refused while card seems to work | Insufficient balance, ceiling reached or authorisation refused | Check account and ceilings in the bank application |
| Card blocked after code entry | Blocking after 3 wrong codes | Contact the bank or follow the procedure indicated in the customer space |
| Card silent or not read | Damaged piece, worn strip, damaged map | Try another terminal and then request a renewal if the problem persists |
| Online payment impossible only | E-commerce option disabled, strong authentication failed | Check payment options and validation notifications |
| Card swallowed at distributor | Wrong code to third attempt, opposition or security | Call immediately the bank or service indicated on the ATM |
Denied does not always mean blocked
A card can be refused on an ad hoc basis without being blocked. A high purchase may exceed your payment ceilingeven if your account is sufficiently stocked. Conversely, a small payment can be rejected if a bank authorization does not pass, if the terminal has a network breakdown or if the merchant does not accept certain cards.
Message « invalid card » is sometimes misleading
On some sites, « invalid card » can simply report an input error: wrong number, expired date, incorrect cryptogram or inconsistent billing address. Before concluding a bank blockage, retrace the information calmly and check that the card used matches the registered payment method.
The most frequent causes of a card that no longer passes
When a credit card becomes unusable, the cause is often simple to isolate. The aim is to check first what can be settled in a few minutes, and then what requires the bank to intervene.
What to do if your credit card is stolen · This official file explains the steps to be taken to oppose and secure your account after your credit card is stolen.
Balance, authorization and ceiling
An insufficient balance remains a classic cause, but it is not the only one. Bank cards also work with Payment ceilings and withdrawal, usually calculated over a slippery period. So you can have money on your account and be refused if you have reached your authorized limit. This happens after several close purchases, a hotel reservation, a lease deposit or a large withdrawal.
The right reflex is to open your customer space or mobile app to control the available balance, pending transactions and ceilings. Some banks allow a temporary increase of the ceiling directly from the application, sometimes with immediate validation or after confirmation by an advisor.
Incorrect confidential code and security blocking
After 3 wrong codes, the card can be blocked to protect the cardholder. At the distributor, it can even be swallowed at the third attempt. This mechanism prevents a person who has found or stolen a card from multiplying the tests. If you just forgot your confidential code, do not try to guess it: each additional test increases the risk of blocking.
Depending on the banks, unlocking may involve a withdrawal with the right code, a customer space, a call to customer service or an agency visit with an ID. If the card has been swallowed, contact the bank without delay, especially if the distributor is not attached to your usual agency.
Expiry, wear or card disabled
An expired card may no longer be used after the date indicated above. In general, the bank sends a new card before expiry, but a change of address, unrecovered mail or a card never activated can cause an interruption. Check the date, then ask your bank if a new card is available or already shipped.
Physical wear and tear is just as common: striped chip, folded card, damaged magnetic tape, failing contact with terminal. A card that works once in two is a clear signal. The problem does not necessarily come from the account, but from the support itself. In this case, renewal is often the most reliable solution.
What to do immediately depending on the situation?
In the face of an invalid credit card, we must act in the right order: secure, diagnose, then unlock or replace. This method avoids unnecessary calls and gives the advisor the right information if you need to contact him.
In store or at the distributor
If the payment fails in store, first try another method of payment if you have one, then ask the merchant if the terminal encounters a problem. If the contactless fails, insert the card and enter the code. If the card is refused with the code, stop testing after one or two failures to avoid blocking after 3 wrong codes.
At the vending machine, be even more careful. Repeated code error may lead to a swallowed card. If the DAB displays an unusual message, cancel the transaction, retrieve the card if possible and check your bank application. In case of a selected card, note the distributor's address, the time of the incident and contact your bank.
For an online payment
On-line, start by checking the information entered: card number, expiry date, cryptogram, holder name. Then check that the internet payment is enabled and that you can validate strong authentication from your phone. A missed notification, an unupdated bank application or a networkless phone may be sufficient to cause the transaction to fail.
Think also of the virtual map If your bank offers one. It can serve as a back-up solution between the emergency of a purchase to be finalized and the replacement of a defective physical card. It allows to compartmentalize the risk, with a dedicated number1 limited amount and one duration of use framed. For a trip, reservation or online subscription, this separation avoids blocking your entire daily life at the slightest incident on the main card.
In case of suspicion of fraud or loss
If you see an unknown operation, if your card has disappeared, or if you think its data has been compromised, do not try to unlock it: object. The aim is to prevent fraudulent use. You can go through the bank application, call your bank or use the bank card opposition number provided by your institution.
In practice, the opposition number indicated in some banking devices is 03 88 40 10 00 from France, and 00 33 88 40 10 00 from abroad. Always check your bank details in your customer area, on your contract documents or on the back of your card if you still have it.
Who to contact and what information to prepare?
Your bank is the only one that can precisely confirm the origin of a blockage, reactivate certain options, order a new card or validate a ceiling increase. The more useful information you prepare, the faster the answer will be.
- The location of the incident : store, website, distributor, foreign country.
- The type of operation Payment, withdrawal, online purchase, subscription, deposit.
- The message displayed Invalid card, payment refused, mute card, incorrect code.
- Time and amount of the attempt, especially in the case of security checks.
- Tests already performed: other terminal, other site, code entry, mobile validation.
If the problem is not urgent, the customer space is often enough: consultation of ceilings, activation of online payment, request for renewal, secure messaging. If you are blocked abroad, at the distributor or in the face of possible fraud, prefer the telephone or opposition service.
Preventing future blockages without thinking about it every day
Invalid credit cards often occur at the wrong time, but some simple habits severely limit the risk. The idea is to set up safeguards without thinking about it every day, with a emergency solution ready for use.
- Check your ceilings before an unusual expense, including travel, moving, equipment, hotel or car rental.
- Keep your banking app up to date to receive strong authentication notifications and manage card options.
- Physically protect the map Avoid folding it, storing it with metal objects or exposing it to moisture.
- Remember your code without noting it with the card and stop attempts if you have any doubt.
- Anticipate expiration by checking your mailing address and arrival of the new card a few weeks before the end of validity.
- Enable operations alerts to quickly identify an unusual payment or a suspicious attempt.
Finally, keep at least one backup solution: some cash, a second card, a mobile payment configured or a virtual card depending on your bank. This safety net prevents a simple technical incident from becoming an emergency, especially when travelling, at night or abroad.