

A signed loan offer constitutes a contractual undertaking between the bank and the borrower. However, in certain specific circumstances, the bank can cancel a signed loan offer, in particular if the suspensive conditions are not fulfilled or if the borrower's financial situation changes significantly. Understanding your rights and remedies is essential to protect your property acquisition project.
Difference between agreement in principle and signed loan offer
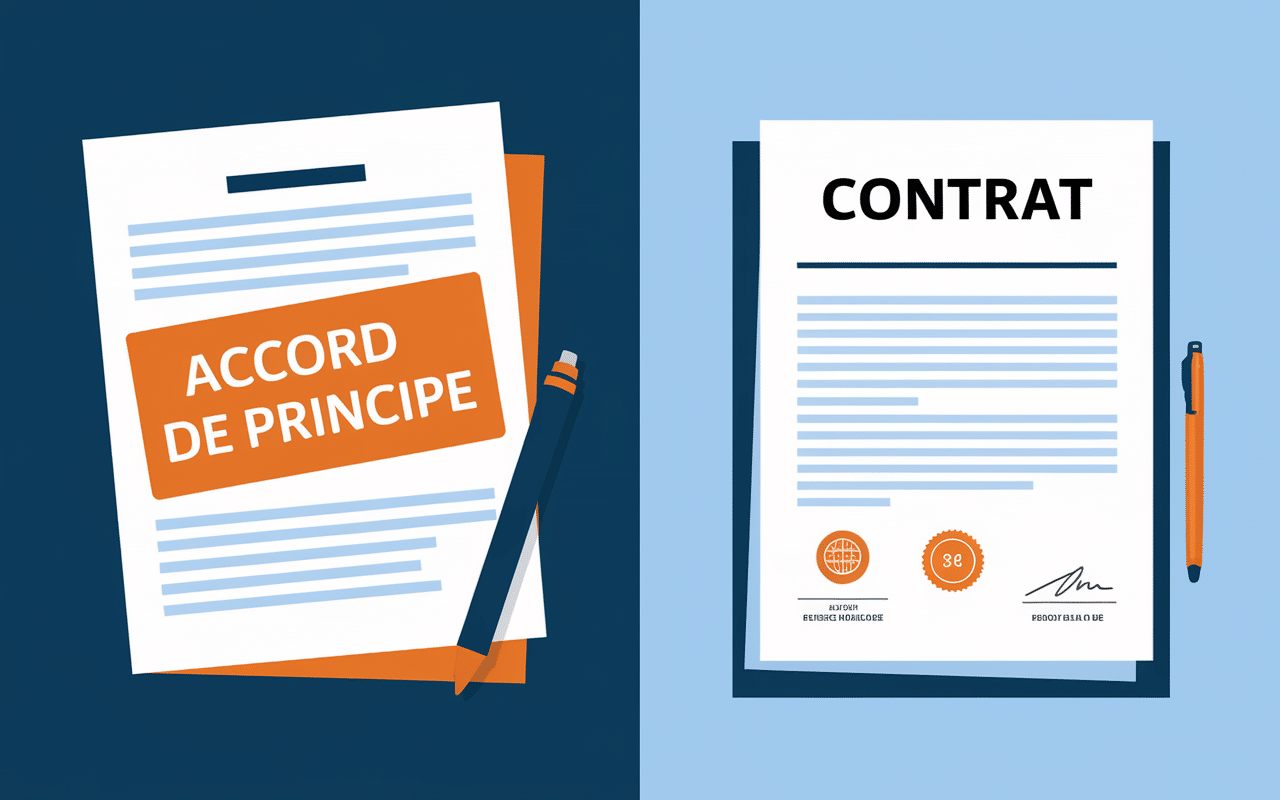
There is a fundamental distinction between the agreement in principle and the signed loan offer, which determines the legal force of the banking commitment.
Agreement in principle represents a loan intention on the part of the bank, based on the information provided in your initial file. This is a moral commitment without contractual value. The bank may reconsider its decision without legal consequences at this stage.
Signed loan offer is a contractual document legally binding on the bank. Once issued and accepted by the borrower, it creates reciprocal obligations. The bank can no longer withdraw freely, except in very specific cases provided by law.
In which cases can a bank cancel a signed loan offer?
Despite its contractual nature, the bank can cancel a signed loan offer in several legally regulated situations:
Non-realization of suspensive conditions
The suspensive conditions represent events which must be carried out before the loan is finally granted. If one of them is not satisfied within the specified time limits, the bank can legitimately cancel the offer.
- Obtaining a building permit for a construction project
- Sale of existing property to finance acquisition
- Maintenance of employment or reported income
Significant change in financial position
If your financial situation deteriorates substantially between the signing of the offer and the release of the funds, the bank may use this change to cancel the loan. This includes loss of employment, a significant decrease in income or the emergence of new undeclared debt.
Fraud or misrepresentation
The discovery of false information or falsified documents in your file is a legitimate ground for cancellation. The bank may withdraw if it proves that your acceptance was obtained by fraudulent means.
Non-compliance with the acceptance deadline
The loan offer must be accepted by the borrower within 30 days of receipt. After this period, the offer becomes obsolete and the bank can cancel a signed loan offer for failure to accept in time.
Legal protection of borrower against cancellation of a loan offer
The Consumer Code strongly protects borrowers through several legal provisions that strictly regulate the possibility of cancellation by banks.
The 10-day reflection period
Article L312-12 of the Consumer Code imposes an incompressible reflection period of 10 calendar days from receipt of the offer. During this period, the borrower cannot accept the offer, but neither can the bank withdraw it without legitimate reason.
The obligation to maintain supply
Once the offer has been issued, the bank contractually undertakes to maintain its terms for the duration of the offer, usually 30 days. This bond protects the borrower against changes in interest rates or changes in trade policy.
Strictly framed cancellation conditions
Article L312-14 of the Consumer Code limits the possibility of cancellation only to the cases provided for in the offer itself, mainly the suspensive conditions and the substantial changes in the borrower's situation.
What recourse if the bank cancels your loan offer in an abusive manner?
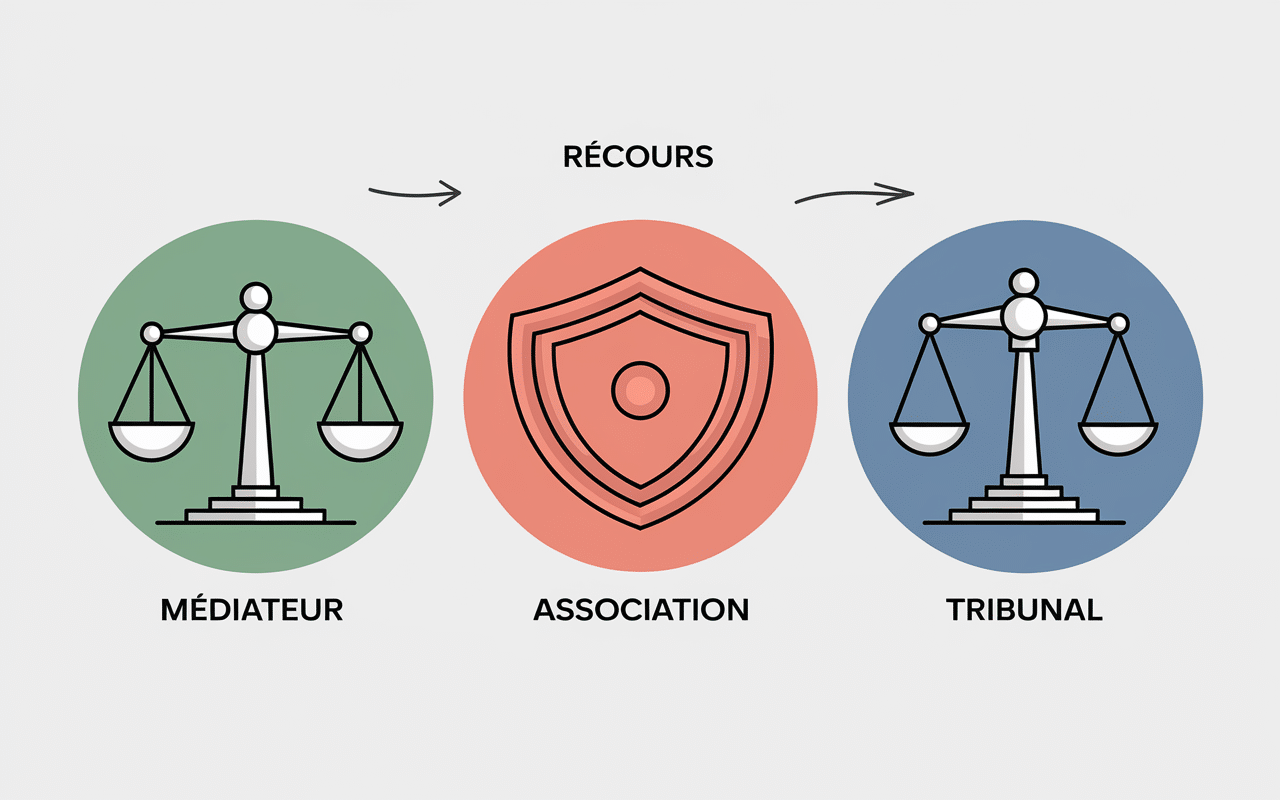
In the face of unjustified annulment, several remedies are available to you to assert your rights and obtain redress.
Banking mediation
The bank mediator is your first recourse in case of dispute. This free procedure allows you to examine your case impartially. You have one year from the written complaint addressed to your bank to refer the matter to the Ombudsman.
Before finalizing your project, find out how buying real estate: the essential steps to secure your project and avoid unforeseen circumstances related to your loan.
To protect your real estate project against unforeseen events, subscribe a Borrower insurance: 7 reasons to insure your real estate credit remains an essential step.
To avoid unforeseen circumstances in the event of a change in the terms of your loan, read our guide oncredit insurance: essential criteria for reliable coverage.
Consumer associations
Organizations like UFC-Que Choisir or CLCV can support you in your efforts and help you build a solid record. These associations have valuable legal expertise to analyse the validity of the cancellation.
Judicial proceedings
If the bank can cancel a signed loan offer In specific cases, abusive cancellation may result in damages. You can apply to the court for:
- Forced execution of loan contract
- Damage for damage suffered
- Reimbursement of expenses incurred
How to secure your real estate project against the risk of cancelling the loan
Several preventive strategies minimize the risk of cancellation and protect your property acquisition project.
Anticipation of suspensive conditions
Identify precisely all the suspensive conditions included in your loan offer and establish a realistic schedule for their implementation. Take sufficient security margins, including for obtaining administrative documents.
Financial stability maintained
Avoid any major professional change between the issue of the offer and the release of funds. Notify your advisor immediately of any changes to your financial situation to jointly assess the impact on your file.
Retention of evidence
Keep all exchanges with your bank in a valuable way: emails, mails, interview reports. This documentation will be valuable in case of dispute over the conditions for cancelling your offer.
| Funding stage | Protection of borrowers | Bank cancellation option |
|---|---|---|
| Agreement in principle | None | Free |
| Unsigned offer | Reflection period 10 days | Legitimate reason only |
| Offer signed and accepted | Contractual protection | Suspensive conditions only |
Your rights to cancel a loan offer
Although the bank can cancel a signed loan offer In specific circumstances, this possibility remains strictly regulated by law. Your protection as a borrower is based on understanding your rights and putting in place preventive strategies. In case of unfair annulment, do not hesitate to file your appeal with the competent authorities to obtain compensation for the damage suffered.