
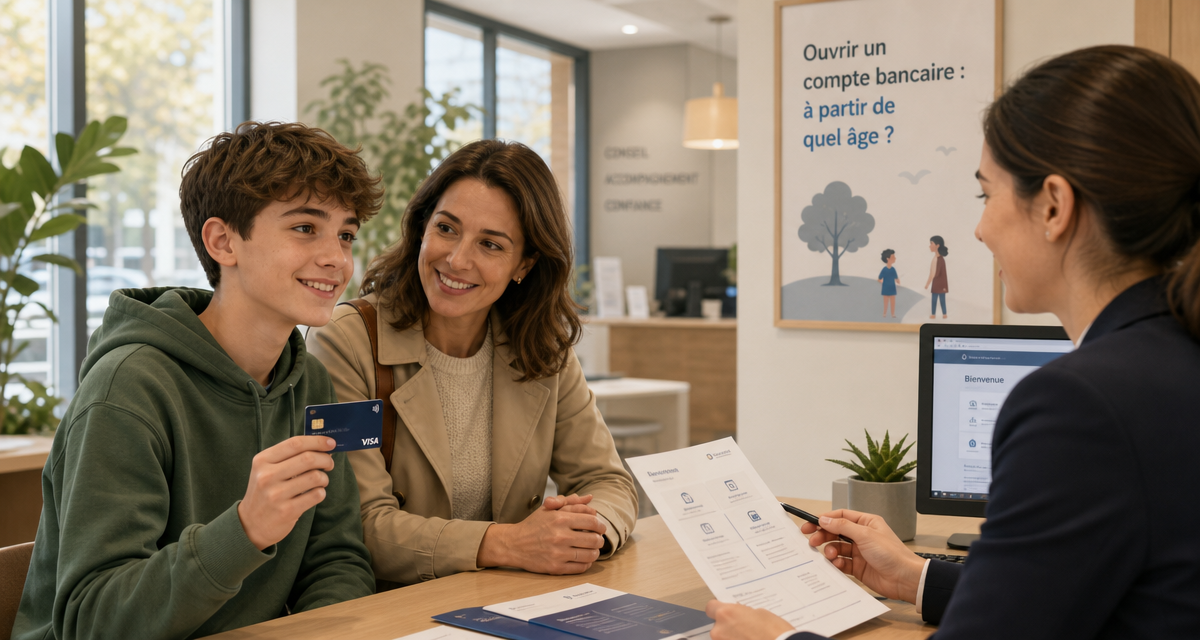

In France, it is possible to open a savings booklet or life insurance in the name of a child from the day of birth. However, access to a real current account and the use of a payment card remain subject to specific steps related to civil maturity. We often find ourselves unable to cope with the banking restrictions when it is simply a desire to give a little financial autonomy.
This article details legal age to open a bank account and specifies the user rights that evolve between 12 and 18 years of age. Together, we take stock of the steps and responsibilities of parents.
Legal age for opening a bank account
A Young Booklet can be opened from birth by the legal representative. From 12 years old, the latter can also open a current account on behalf of the minor, with a credit card adapted according to the chosen offer. To take the step today, you can Open a bank account online or in an agency.
This transition to financial independence is done in stages, starting with passive savings managed by parents.
Saving for your child from the first day
Parents may open a Booklet A or an ELP from birth. The child does not need to sign the documents. The procedures are simple and free of charge.
Early savings prepares the financial future in a serene manner. Funds are blocked or available depending on the product chosen. It is a simple and effective foresight tool. Banks greatly facilitate this initial administrative process.
Only the legal representative manages the money. The child remains a passive beneficiary without power of action.
But before the child can get his first euros, the parents keep a Total control on each movement.
The pivotal role of legal representatives before 12 years
The parents hold the total liability for funds deposited. They themselves make deposits and withdrawals. No banking act is possible without their direct intervention.
The use of money must be used interest of the minor only. This concerns the education or daily maintenance of the child. However, the law strictly regulates this management by guardians.
Parents manage daily :
- Deposit of cheques
- Withdrawal
- Management of family stables
Changes in rights and autonomy from 12 to 17 years
If early childhood is marked by exclusive parental management, entry to college triggers the first concrete financial freedoms.
The Young Booklet and the first steps at age 12
At the age of 12, Young Booklet offers attractive remuneration. The agreement of the parents remains compulsory for the opening. This is a first step in saving.
Opening of a current account and 16 year old card
It's the ideal age for managing its first income. Summer jobs often feed this account.
Management of ceilings and cards with systematic authorisation
Cards with systematic authorisation check the balance of the account before allowing each payment. This avoids spending above the available balance and provides a reassuring framework for parents.
Parents set payment limits. These limits adjust from a mobile application.
What documents are provided and who is legally responsible?
Beyond age, success of the opening is based on a solid administrative record and a clear understanding of legal commitments.
List of proofs required by situation
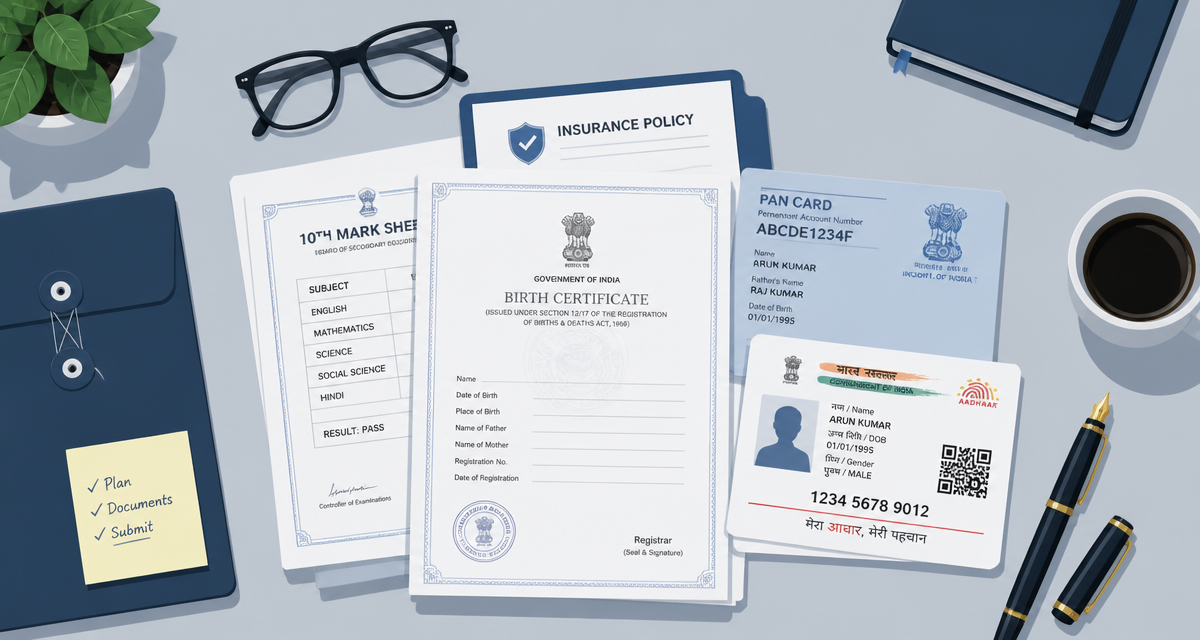
Open a bank account From what age can we do it? From birth, but with the right supporting documents. Provide identification of the minor and guardian. A recent proof of domicile is required. The family record proves filiation.
Here are the Documents to be prepared for your appointment:
- Valid ID card or passport
- Electricity bill less than 3 months
- Birth certificate extract
Procedures in the event of separation or parental disagreement
In the event of separation, the agreement of one parent is often sufficient. However, the other may object formally. The bank then requires both signatures.
If the conflict persists, Family Court Judge. It always favours the financial interest of the child. The procedures are longer.
3 criteria for choosing your child's bank
Once the legal rules are assimilated, it remains to select the institution that will best accompany Learning from your teenager.
Comparison between traditional and neobank banks
| Type of bank | Maintenance costs | Major advantage | Target audience |
|---|---|---|---|
| Traditional bank | Sometimes included in a group offer | Presence of physical agencies | Families (need for advice) |
| Banque en ligne | Often free | Reduced annual costs | Autonomous youth |
| New bank for minors | Low or non-existent | Speed of the mobile app | 10-18 years |
Educating budget management through mobile applications
Modern applications fluidize money management. The child visualizes his spending in real time. It can create specific pools.
It is necessary to distinguish pocket money from allowances. The income of a student job requires more rigour.
Recourse to account in case of refusal
A bank may refuse to open without justification. In this case, enter the Bank of France immediately. She designate a place of business For you. This free procedure guarantees access to basic banking services.
Schedule a certificate of refusal in writing. This document is essential for launching the legal process.
From birth for savings or from 12 years for autonomy, each step secures your child's future. Gather the proofs now to open a bank account and initiate this vital financial education. Give him today the keys to responsible management ensuring its independence tomorrow.