
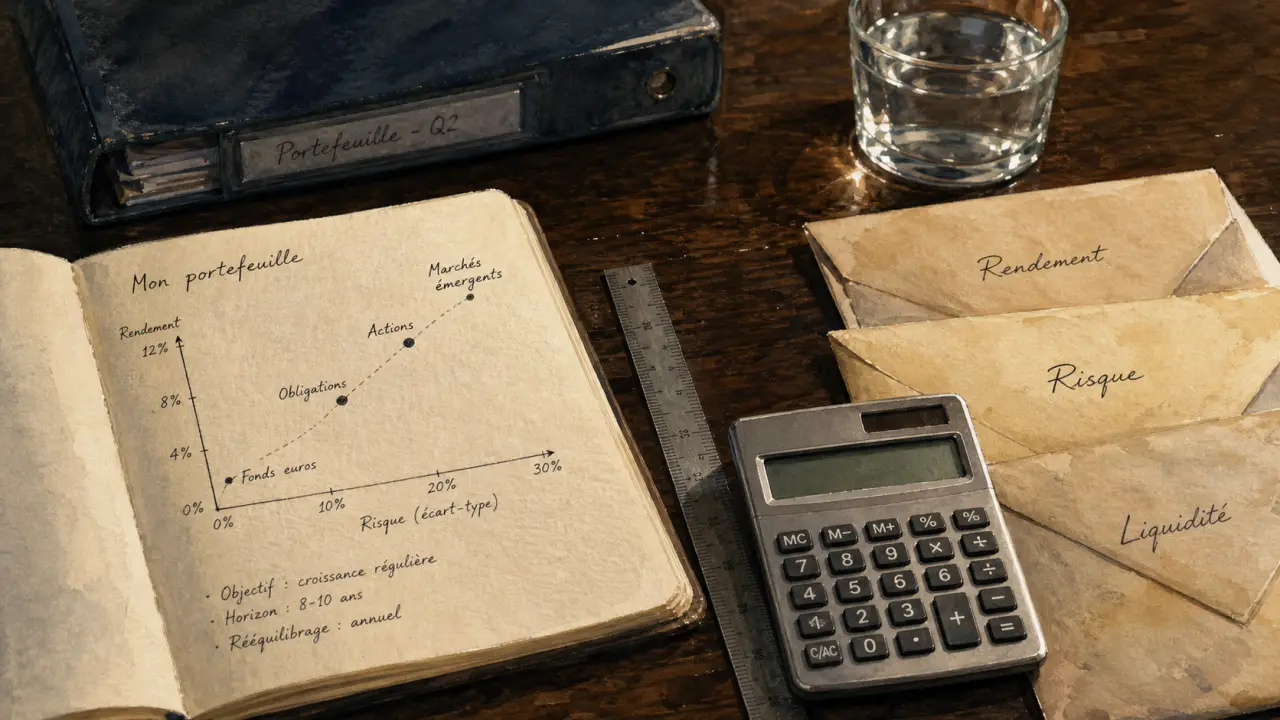

Aim for a 10 % placement per year is possible, but this performance is not neutral. At this level, the investor leaves secure savings to enter into risk, long term, volatility and sometimes block funds. The real question, therefore, is not just what product can bring in 10%, but under what conditions this yield can be achieved, and with what possible loss in front.
10% per year: a realistic goal, but rarely guaranteed
An annual yield of 10% attracts because it almost doubles a capital in just over seven years, excluding taxation. But we must distinguish three concepts that are often confused: displayed yield, the expected return and the return actually received after any costs, taxes and losses.
Secured investments do not play in this category. Guaranteed capital investments can range up to about 5 % in the best configurations, while euro funds, SCPIs or prudent media generally remain below this threshold. A risk-free rate around 3 % Often serves as a benchmark: beyond that, the additional remuneration almost always corresponds to an additional risk taking.
The 10% figure can therefore serve as a portfolio target, but not as a promise. It can be reached in certain years, exceeded over favorable periods, and then greatly reduced by a bad market sequence. An investor aiming at this level must accept that performance is not linear. A year at +18% can be followed by a negative year, without this being abnormal for a support exposed to risk.
Investments capable of approaching or exceeding 10% per year
Listed shares: the historical engine, with real shocks
Actions remain one of the most coherent supports for looking for high performance over long periods. IEIF indicates a TRI 15.1 % over 40 years for shares, a figure that shows the power of this active class when it is kept for a long time. Over the 15 to 20 year horizons, the annual returns of listed shares are often mentioned in a range of 5-7 %, depending on the markets, periods and costs.
Understanding the risk-return relationship of your financial investments · Learn how to assess the risks and prospects of your investments with the financial market authority's educational advice.
To target 10%, it is generally necessary to accept a dynamic exposure: international actions, growth sectors, small and medium-sized capitalizations, or more offensive active management. The reverse is clear: valuation can decline sharply in the short term. The investor must therefore have a long horizon and avoid investing the money he needs quickly.
The actions promise nothing stable. They require patience, diversification and discipline. In return, they remain one of the few investments capable of achieving a higher return than simply maintaining purchasing power over time.
Private equity: high yield, low liquidity
Private equity, or risk capital, involves investing in unlisted companies. Its average yield is given to 13.3% per year over 10 yearsThis makes him a natural candidate when it comes to 10% placement per year. It can be accessed via specialised funds, certain units of life insurance account or dedicated vehicles according to the investor profile.
Its main constraint is the liquidity. Funds may be blocked for several years, sometimes with limited visibility on the real value of the participations between two valuation periods. It is therefore not a cash investment, but a tool of wealth diversification for only part of the capital.
Private equity also requires a true acceptance of the cycle. The average reported return does not tell us about the trajectory, nor about the actual time before the investments are recovered. It is a relevant medium for long-term capital, not short-term savings.
Structured products, crowdfunding and cryptocurrency: conditional yield
Structured products can display attractive coupons through an index, action or basket mechanism. They sometimes offer partial capital protection, but this protection depends on specific conditions. The facial rate must never be read alone: look at the protective barrier, the maximum duration, the risk of early recall, the costs and the unfavourable scenario.
Real estate or entrepreneurial crowdfunding may also target high returns, but there is a risk of delay, default or capital loss. Cryptocurrency can generate spectacular performance, but with extreme volatility and technological, regulatory or platform risk. They should not be confused with a regular investment with predictable returns.
These solutions may complement a portfolio, but require accurate reading of subscription documents. The potential return is worthless if access conditions, duration or actual risk are not understood from the outset.
Compare options before investing
Return is not enough to classify an investment. Four criteria must be met: capital guarantee, holding horizon, liquidity and complexity. A medium that potentially earns 10% but blocks funds eight years does not meet the same need as an investment available at any time.
| Support | Potential yield | Principal risk | Adapted Horizon |
|---|---|---|---|
| Listed shares | High, variable by period | Volatility and capital loss | Long term |
| Private equity | 13.3% per year over 10 years | Blocking of funds and selecting companies | Very long term |
| Structured product | Conditional coupon | Poorly understood unfavourable scenario | Long-term medium |
| SCPI | Generally less than 5 % | Real estate market and liquidity | Long term |
| Euro funds | Less than dynamic investments | Limited performance | Short to medium term |
| Guaranteed capital | Up to about 5 % | Capped performance | Short to medium term |
A good reading is to think of his wallet as a corridor. It is not a question of choosing a single door at the end of the corridor, but of organising areas of passage between safety, efficiency and availability. Upon entry, precautionary savings must remain liquid. In the centre, balanced supports absorb foreseeable needs. Basically, more risky investments can look for performance, as they have time to cross cycles.
This image helps avoid a frequent mistake: placing all its capital on the medium that promises the best rate, without wondering when the money will have to come out. Good comparison is not just about performance. It also focuses on time, flexibility and the level of loss that can be sustained.
Warning signs of performance promises
"guaranteed" capital and high yield rarely go together
An investment that promises 10% per year with guaranteed capital must trigger immediate verification. In finance, the guarantee has a cost: if the capital is actually protected, the return is usually lower or very framed. When both are presented as certain, read the small lines or abstain.
Some talk about the confusion between partial protection, guarantee at expiry and absence of risk. For example, a structured product can protect capital until an index drops beyond a defined threshold. If this threshold is crossed, the loss can become real. The word protection does not therefore have the same value as Guarantee.
The right reflex is to look for the exact mechanics of the product, not its only commercial promise. The higher the reported yield, the more attention should be paid to exit conditions, thresholds and adverse scenarios.
Fees, taxation and liquidity change net return
Gross return is not what the investor retains. Entry, management, performance or arbitration fees can significantly reduce performance. Taxation depends on the envelope used: securities account, life insurance, PEA, PER or specialised fund. Before comparing two investments, we must therefore reason in return likely netNot in marketing.
Liquidity is just as important. An investment may seem profitable on paper, but become binding if the exit is impossible, expensive or dependent on an inactive secondary market. This constraint is particularly present in private equity, some SCPI and part of crowdfunding.
The same gross rate can therefore produce two very different experiments depending on the duration of immobilization and the costs. That's why an attractive performance must always be read with the output context, not just with the coupon displayed.
Build a prudent strategy to target 10%
To search for 10% a year without turning its heritage into a bet, diversification is essential. It involves the allocation of risks between several asset classes, geographical areas, durations and liquidity levels. The objective is not to eliminate the possible loss, but to prevent a single failure from compromising the entire portfolio.
- Keeping savings available before investing in volatile or blocked media.
- Limit the share of highly risky assets such as cryptocurrency, crowdfunding or unlisted funds.
- Check the approval of intermediaries and consult the lists and warnings of the AMF or ACPR in case of doubt.
- Compare net return, after fees, taxes and actual capitalisation.
- Simulate multiple scenarios : favourable, medium and unfavourable, to measure the impact of a temporary fall or defect.
A beginner investor can first aim for a simple architecture: a secure base, a diversified stock pocket, and then a limited share in more offensive media. An experienced investor, with a long horizon and a high loss capacity, will be able to integrate private equity or structured products, provided that they clearly understand how they work.
The 10 % placement per year exists mainly as an overall yield objective, not as a miracle product. Supports capable of achieving this demand time, selection and true risk tolerance. The best decision is to look for performance without buying a promise: understand the mechanism, measure the possible loss, then invest only the capital share compatible with this horizon.